Home Asking Price Index, October 2020: oversupply halts price rises
Asking prices in England and Wales rose just 0.1% in September, as new sales instructions surged 32% year on year across mainland UK.
This is the October 2020 edition of the Home Asking Price Index, released on 13 October 2020, under the headline:
Oversupply Halts Price Rises
The headlines and summary below are the report's own words, with the key figures as it published them, followed by the report's charts and regional tables as printed.
Headlines
- Asking prices go sideways as the market strains under the sheer volume of new stock.
- The mix-adjusted average asking price for England and Wales posts a mere 0.1% rise since the September reading, while the year-on-year rise slipped to 3.5%.
- Supply of new sales instructions for mainland UK is overwhelming (up 32% in September compared to September 2019).
- Excessive supply in Greater London continues and now risks a severe market correction (new listings up 87% in September compared to September 2019).
- Despite surging supply the current stock count for England and Wales remains lower than in October 2019 by 4.6%.
- Scottish vendors continue to show exceptional confidence (third month out of a prolonged lockdown) with a further massive hike in the average asking price of 1.8% since last month, making the annualised growth a heady 8.9%.
- The best-performing English region is Yorkshire, showing year-on-year price growth amounting to an annualised gain of 8.6%.
- Another cautious monthly rise of 0.3% takes the East of England (the UK's worst-performing region) firmly into positive growth year-on-year (+1.3%), while the first monthly falls post-lockdown are seen in the South East (0.5%) and South West (0.4%).
- 11.6% more properties on the market were reduced in price last month compared to September 2019, suggesting that vendors' confidence is waning and patience ebbing. Moreover, the average price cut is now 19.4% higher than a year ago.
- Overall supply in the UK rental sector is 5.5% down year-on-year. However, this figure obscures huge regional disparity. Severe shortages are to be found in most English regions and in Wales. Meanwhile, the Greater London area shows a vast increase in properties available to rent (+59% year-on-year).
Summary
The recently announced record levels of mortgage approvals will keep pace with supply in most parts of the UK in the near term but not where oversupply is greatest. London's stock levels have been inflated by 50% since April and, thanks to September's record number of new listings, the sum total of new listings from April to September inclusive is around 10% more than for the same period in 2019. The September total of new instructions in Greater London is the largest we have seen since June 2008.
Home prices are looking increasingly fragile in the southern regions due to the deluge of new listings over recent months. Persistent oversupply post-lockdown has triggered asking price corrections in the South West and the South East this month. Perhaps surprisingly, London prices managed to nudge up 0.1% since last month despite an overwhelming flood of new inventory (up 87%, Sept vs. Sept 2019). This suggests that, for the time being, most vendors are hopeful rather than realistic. However, not all sellers are in denial about the current state of oversupply as indicated by the number of properties on the market with slashed prices; this has risen to a 16-month high during the month of September.
The annualised mix-adjusted average price growth across England and Wales is currently +3.5%; in Sept 2019, the annualised rate of increase of home prices was -0.1%.
Key figures
| Measure | Figure |
|---|---|
| Monthly change in asking prices (England & Wales) | +0.1% |
| Annual change in asking prices (England & Wales) | +3.5% |
| New sales instructions (mainland UK, YoY) | +32% |
| Unsold stock change (England & Wales, YoY) | -4.6% |
| Price reductions increase (YoY) | +11.6% |
| Average price cut increase (YoY) | +19.4% |
| UK rental sector supply change (YoY) | -5.5% |
Figures are for England and Wales unless the report states otherwise, as published in the edition.
Charts from the report
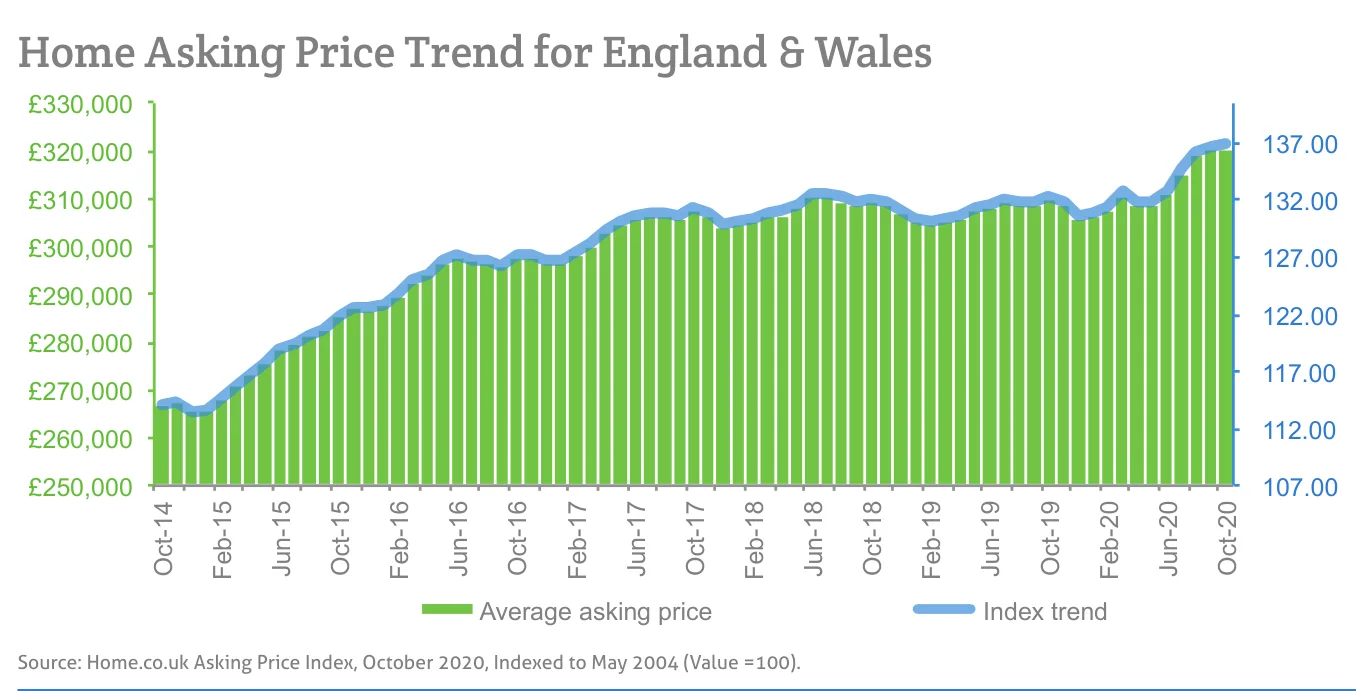
Source: Home.co.uk Asking Price Index, October 2020, Indexed to May 2004 (Value =100).
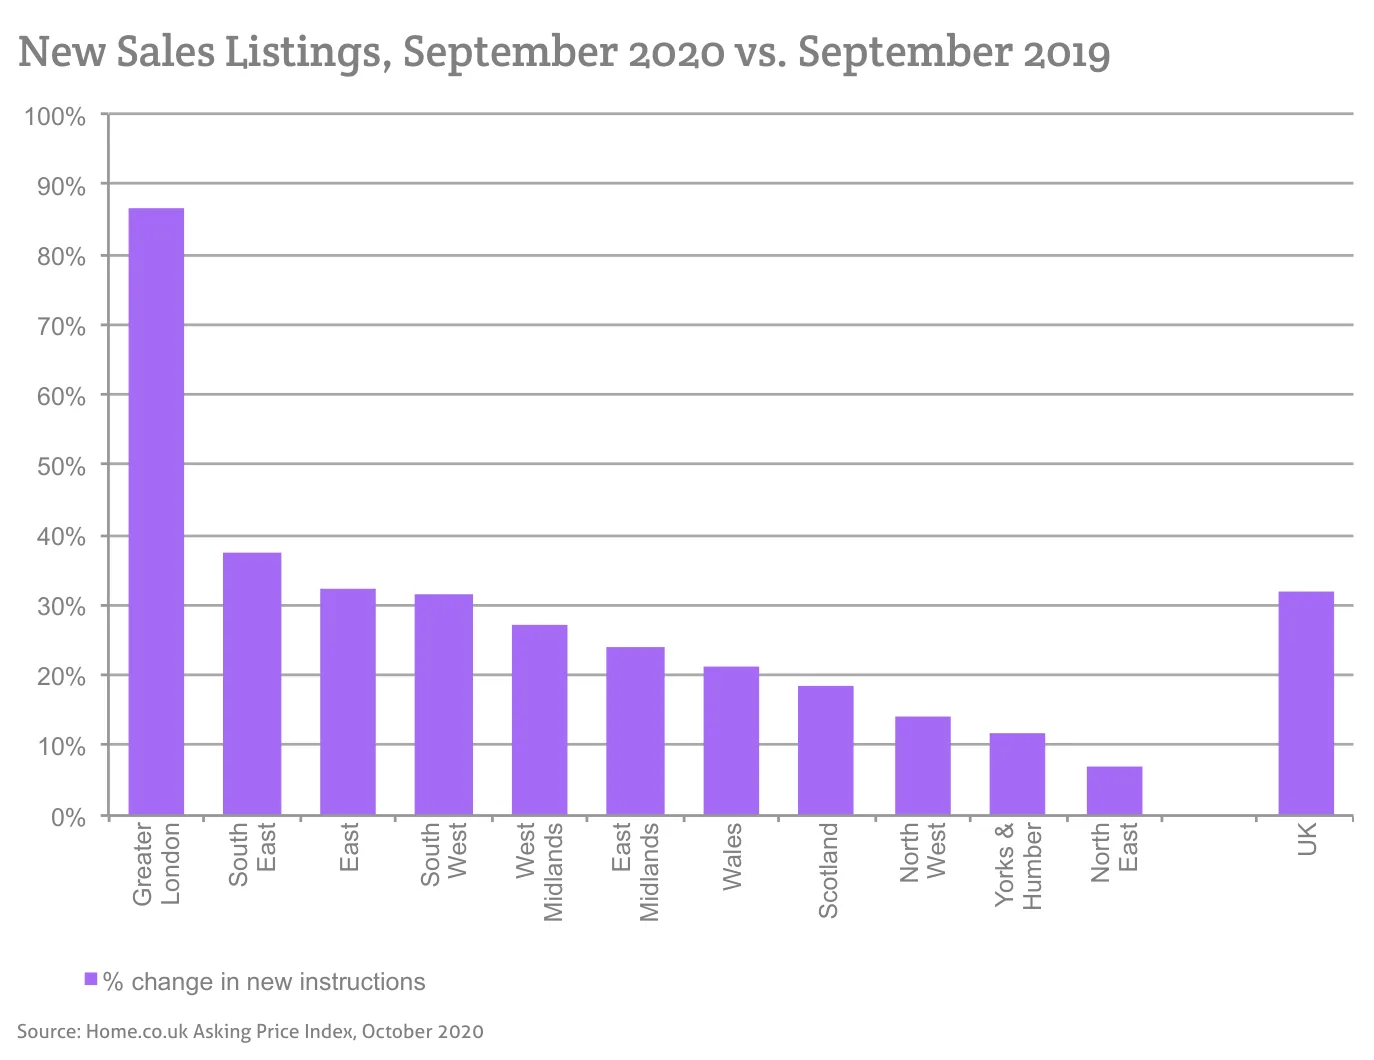
Source: Home.co.uk Asking Price Index, October 2020
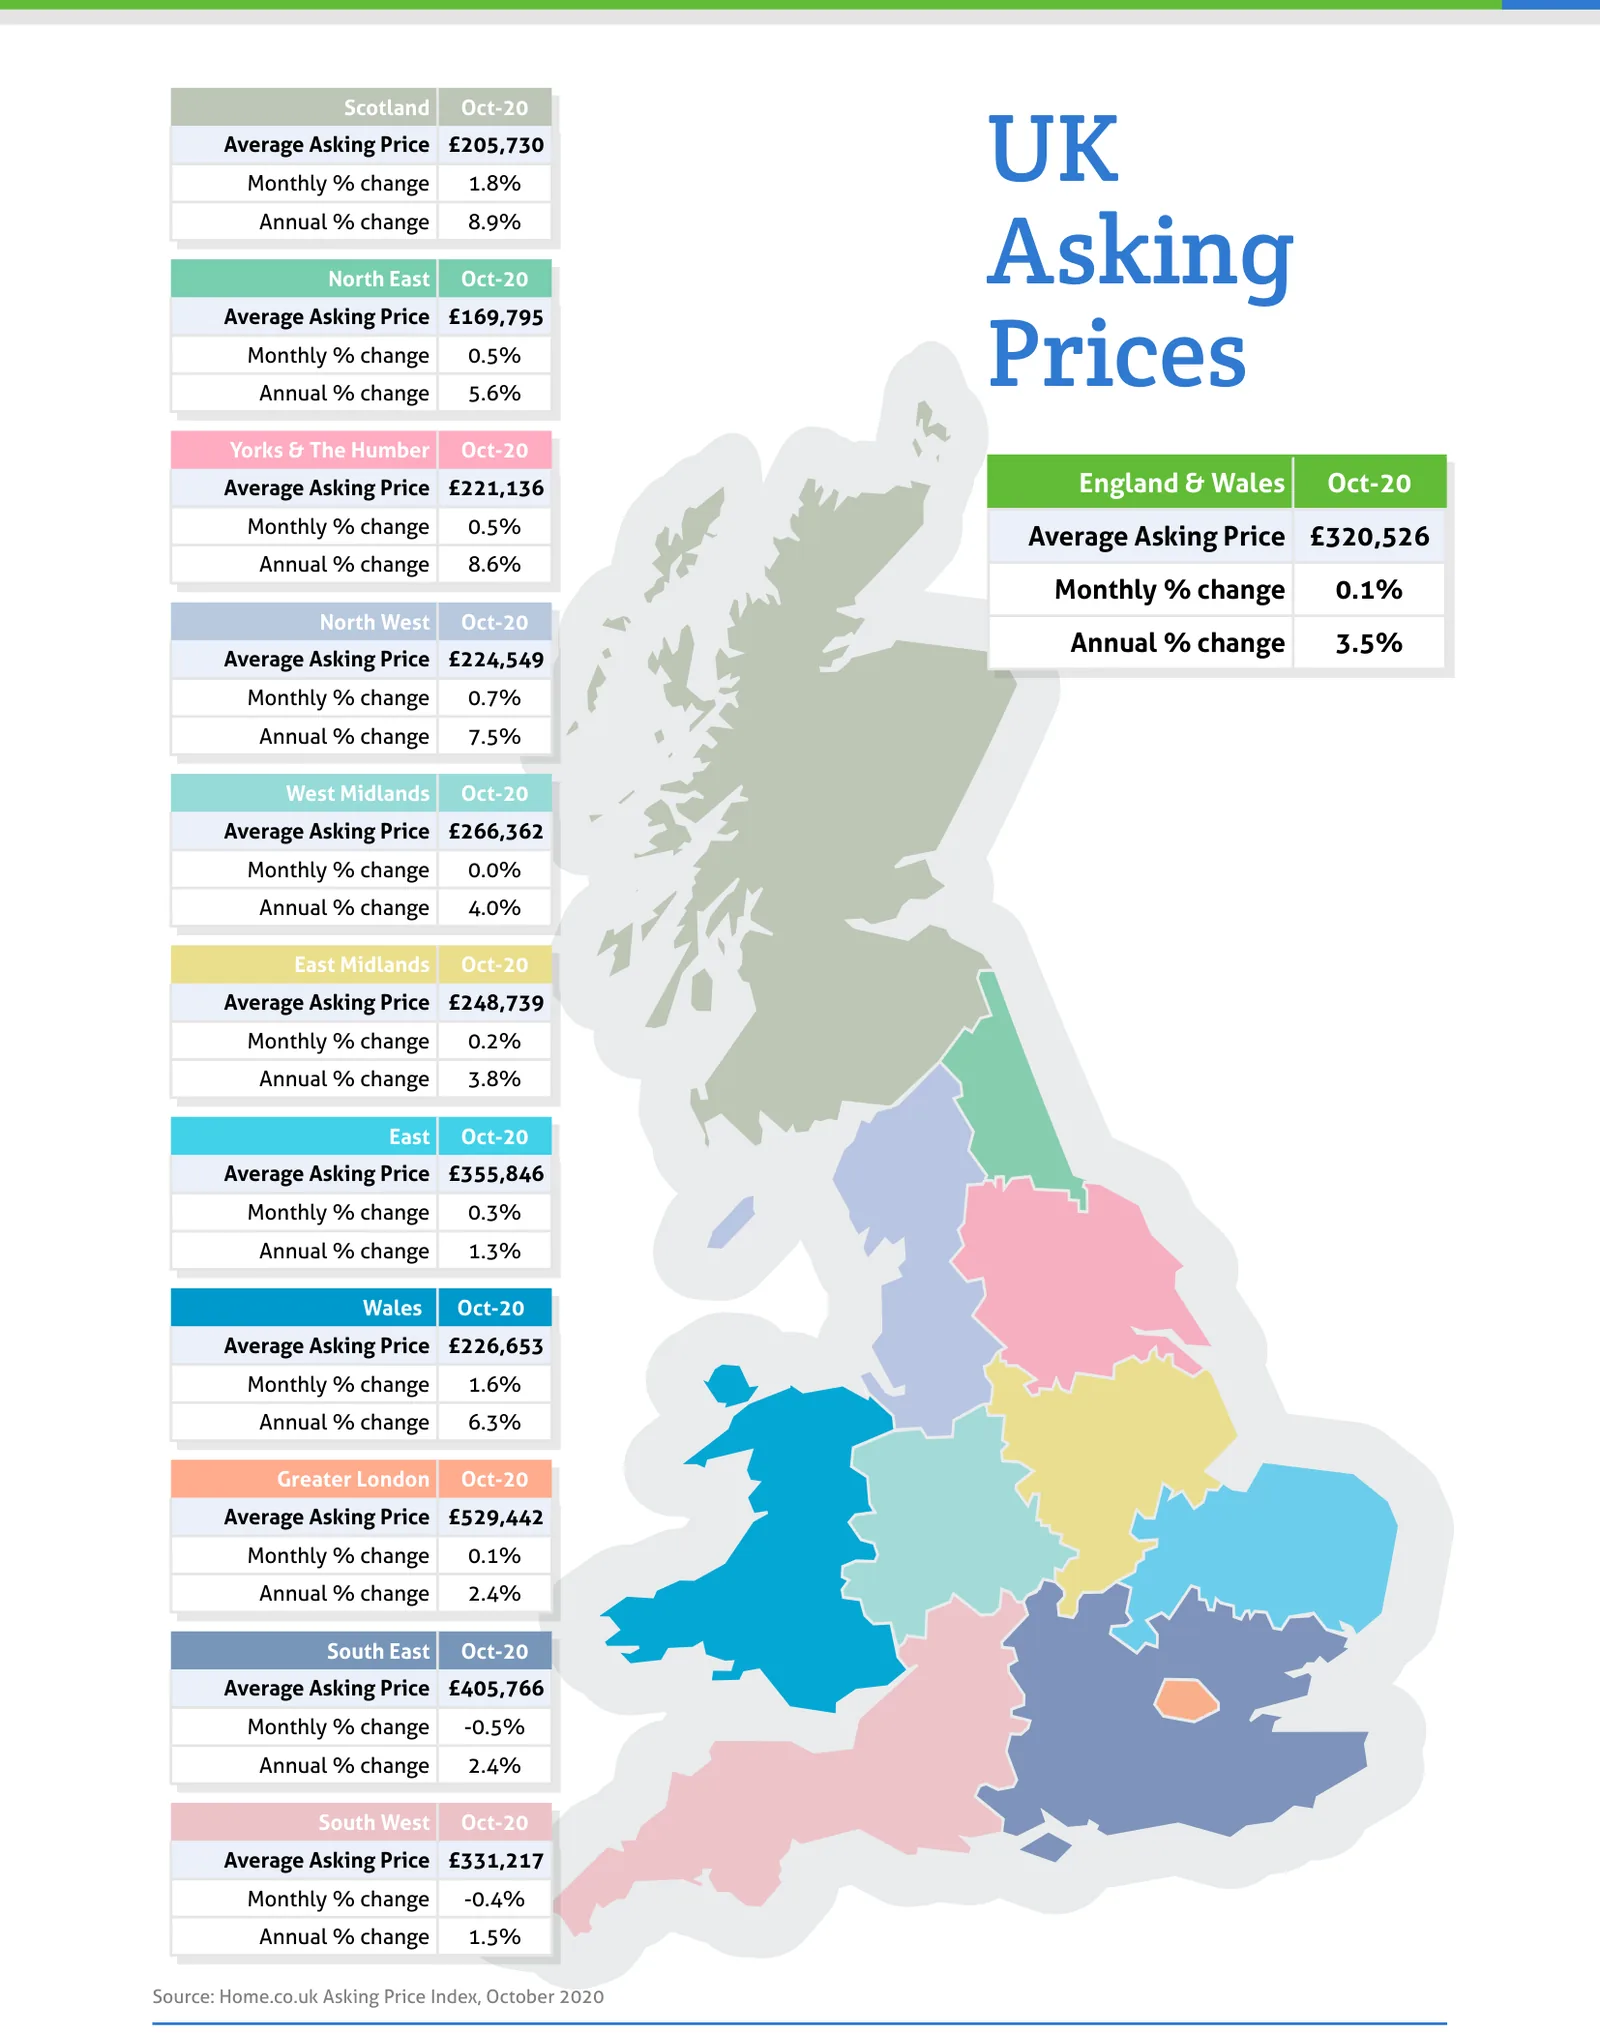
Source: Home.co.uk Asking Price Index, October 2020
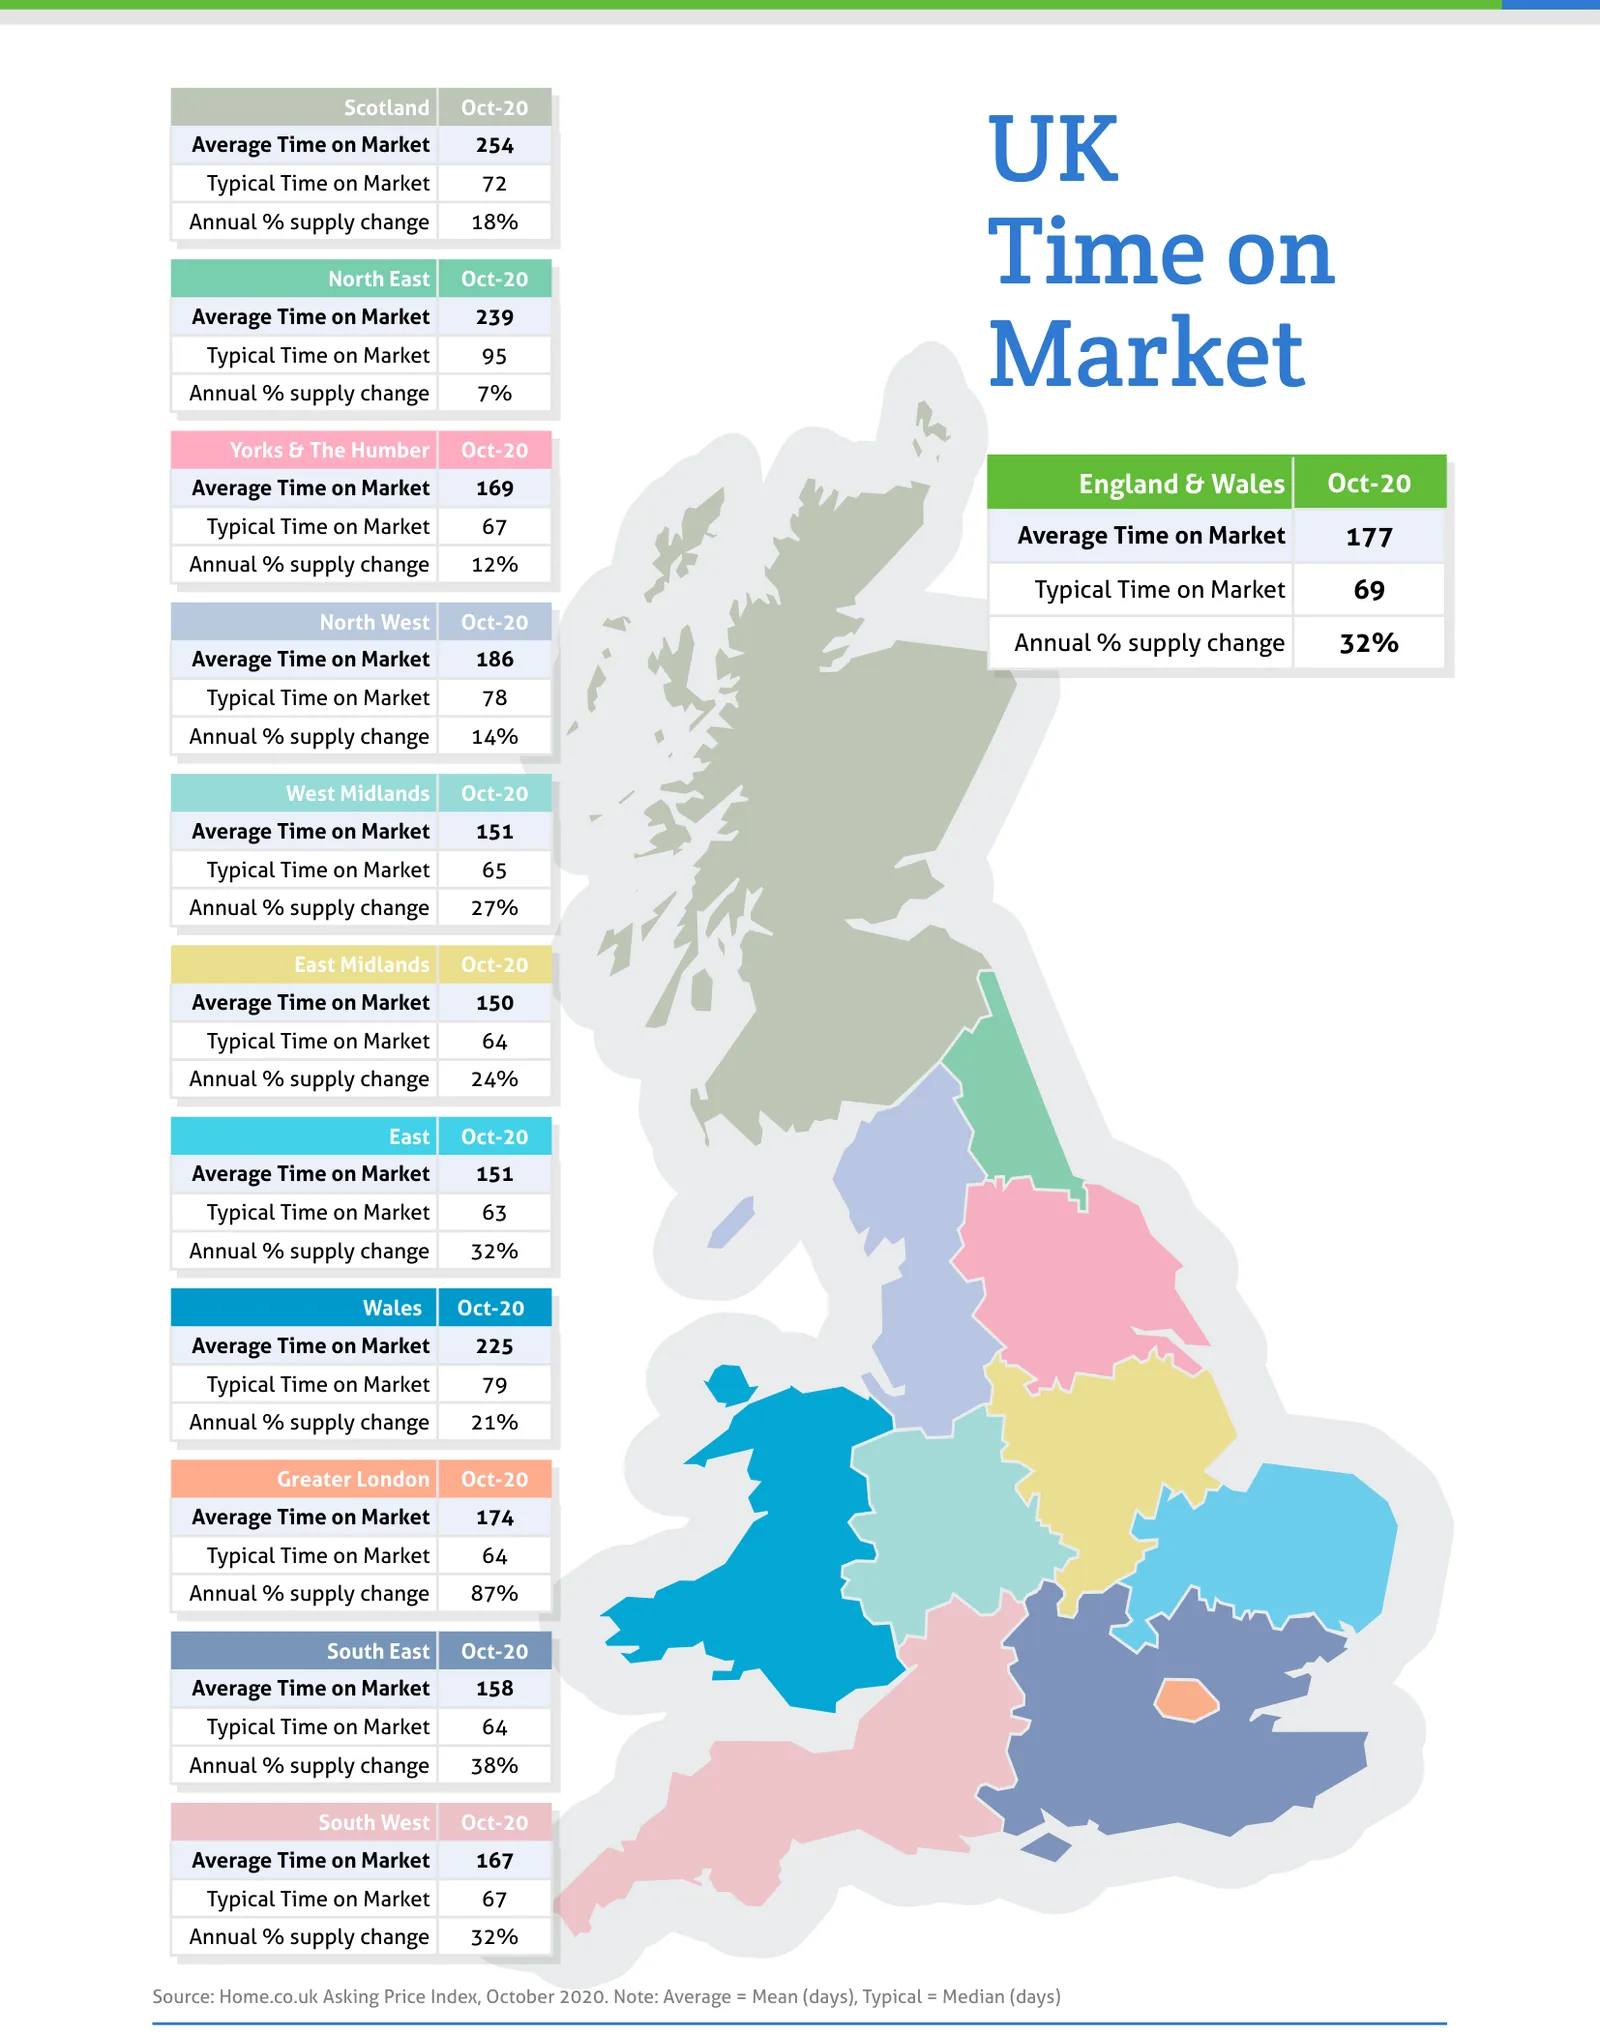
Source: Home.co.uk Asking Price Index, October 2020. Note: Average = Mean (days), Typical = Median (days)
Regional tables
UK Asking Prices, Oct-20
| Region | Average Asking Price | Monthly % change | Annual % change |
|---|---|---|---|
| Scotland | £205,730 | 1.8% | 8.9% |
| North East | £169,795 | 0.5% | 5.6% |
| Yorks & The Humber | £221,136 | 0.5% | 8.6% |
| England & Wales | £320,526 | 0.1% | 3.5% |
| North West | £224,549 | 0.7% | 7.5% |
| West Midlands | £266,362 | 0.0% | 4.0% |
| East Midlands | £248,739 | 0.2% | 3.8% |
| East | £355,846 | 0.3% | 1.3% |
| Wales | £226,653 | 1.6% | 6.3% |
| Greater London | £529,442 | 0.1% | 2.4% |
| South East | £405,766 | -0.5% | 2.4% |
| South West | £331,217 | -0.4% | 1.5% |
UK Time on Market, Oct-20
| Region | Average Time on Market | Typical Time on Market | Annual % supply change |
|---|---|---|---|
| Scotland | 254 | 72 | 18% |
| North East | 239 | 95 | 7% |
| Yorks & The Humber | 169 | 67 | 12% |
| England & Wales | 177 | 69 | 32% |
| North West | 186 | 78 | 14% |
| West Midlands | 151 | 65 | 27% |
| East Midlands | 150 | 64 | 24% |
| East | 151 | 63 | 32% |
| Wales | 225 | 79 | 21% |
| Greater London | 174 | 64 | 87% |
| South East | 158 | 64 | 38% |
| South West | 167 | 67 | 32% |
From the director's commentary
"We are witnessing an unprecedented rebalancing of the UK property market. During the fourteen years I've been studying and reporting on the UK housing market, I've not seen anything remotely like the current level of disparity between London and the regions."
Doug Shephard, Director at Home.co.uk
Read the full October 2020 edition (PDF, 7 pages)
About the Home Asking Price Index
The Home Asking Price Index measures the change in the prices sellers ask for residential property across England, Wales and Scotland. Today it is computed every month from around half a million advertised homes and is mix-adjusted, so a change in what happens to be on the market does not move the figure; earlier editions state the sample they were built from. Because an asking price is set months before a sale completes, the index runs around five months ahead of completed-sale measures such as the UK House Price Index.
Every edition in the archive, back to October 2006, is listed on the index page. How we measure the UK property market explains the listing data behind it, and today's figures by area are on house prices and rental prices.
Text and figures above are quoted from the October 2020 edition as published, with punctuation normalised for the web, and are not revised. Later editions may restate them.
More in What is happening to house prices: the Home guide
Thinking about your next move?
See what your home's worth in seconds, with the UK's longest-running property data behind it.
Get an instant valuation