Home Asking Price Index, July 2024: market activity increases despite burdensome Bank Rate
Asking prices in England and Wales rose 0.2% in July 2024, up 0.7% year on year, while new instructions increased 4% compared with June 2023.
This is the July 2024 edition of the Home Asking Price Index, released on 12 July 2024, under the headline:
Market Activity Increases Despite Burdensome Bank Rate
The headlines and summary below are the report's own words, with the key figures as it published them, followed by the report's charts and regional tables as printed.
Headlines
- Asking prices nudged up 0.2% during the last month across England and Wales (the sixth consecutive monthly rise) and are now up 0.7% compared to July 2023.
- The unsold sales stock count for England and Wales increased again during the last month to reach a 10-year high for July. Nearly 4,000 properties were added to agents' portfolios, making the current total 489,086.
- Prices increased again in all English regions (except the North West) and Wales during the last month. The mix-adjusted average was trimmed by 0.5% in Scotland and by 0.2% in the North West. Prices remained unchanged in the South West. Vendors in the North East were the most bullish, raising their prices by 0.9%.
- Despite the relatively large amount of stock for sale, market momentum remains relatively healthy as indicated by both the Typical Time on Market (median) for unsold property being seven days less than in July 2019 and our Market Turnover Indicator. However, the current median time on market for unsold property in England and Wales is six days more than in July last year.
- The total number of new instructions entering the market during June 2024 was 4% more than during June 2023.
- The North East is the new regional property market growth leader with a year-on-year gain of 4.8%, while the South West is now the worst performing region with a loss of -1.2% over the same period.
- The annualised national growth figure for asking rents has slowed further to just 2.5%. However, the North East and Wales continue to lead the regional growth table, indicating rises of 14.5% and 12.8% respectively year-on-year. Meanwhile, the decline in Greater London rents has slowed to -1.2%.
- The London boroughs of Redbridge and Havering are the current growth leaders with annualised rental growth of 13.0% and 10.1% respectively.
Summary
Key market indicators show that, despite lacklustre performances in the southern markets, the UK property market is in much better shape overall than in 2019. This is clearly remarkable and perhaps counterintuitive given the current higher levels of stock for sale and substantially higher borrowing costs. However, during the same 5-year period, UK rents have risen by 44.6% and this meteoric rise has provided enormous support for the sales market. Moreover, this support has a regional bias with respect to gross rental yields which are higher in the North.
Overall home price rises are being kept in check by high stock levels and stubbornly high mortgage costs. However, considerable regional variation is apparent. While Greater London, adjacent regions and the South West remain in recovery mode, the northern, Scottish and Welsh markets have more than made up for lost ground following the shock price drop in December 2022 and continue to thrive.
Clearly, without this vast support from the rental market, the sales market would be in a much worse state. Keir Starmer's new government needs to understand that rent fundamentally underpins the value of property and therefore future legislation regarding the lettings market should be very carefully considered. Indeed, activists' calls for rent controls and an end to contractual tenure casts dark shadows over the future of both the sales and rental markets.
Key figures
| Measure | Figure |
|---|---|
| Monthly change in asking prices | +0.2% |
| Annual change in asking prices | +0.7% |
| New instructions change (June 2024 vs June 2023) | 4% |
| Annualised asking rent growth (UK) | 2.5% |
| Monetary inflation (RPI ex. housing) | 1.3% |
Figures are for England and Wales unless the report states otherwise, as published in the edition.
Charts from the report
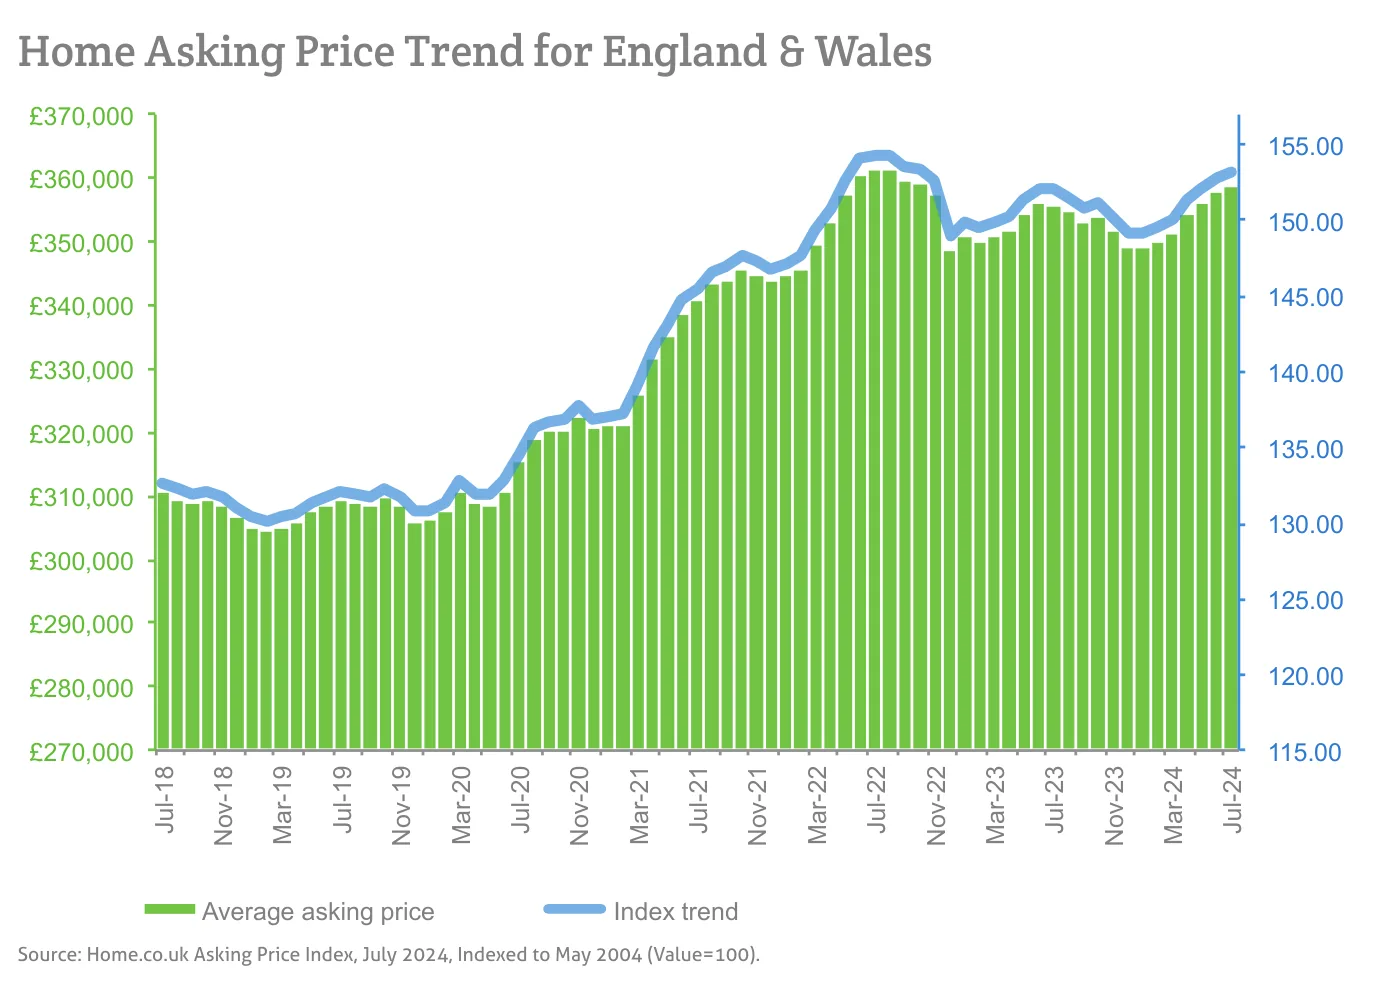
Source: Home.co.uk Asking Price Index, July 2024, Indexed to May 2004 (Value=100).
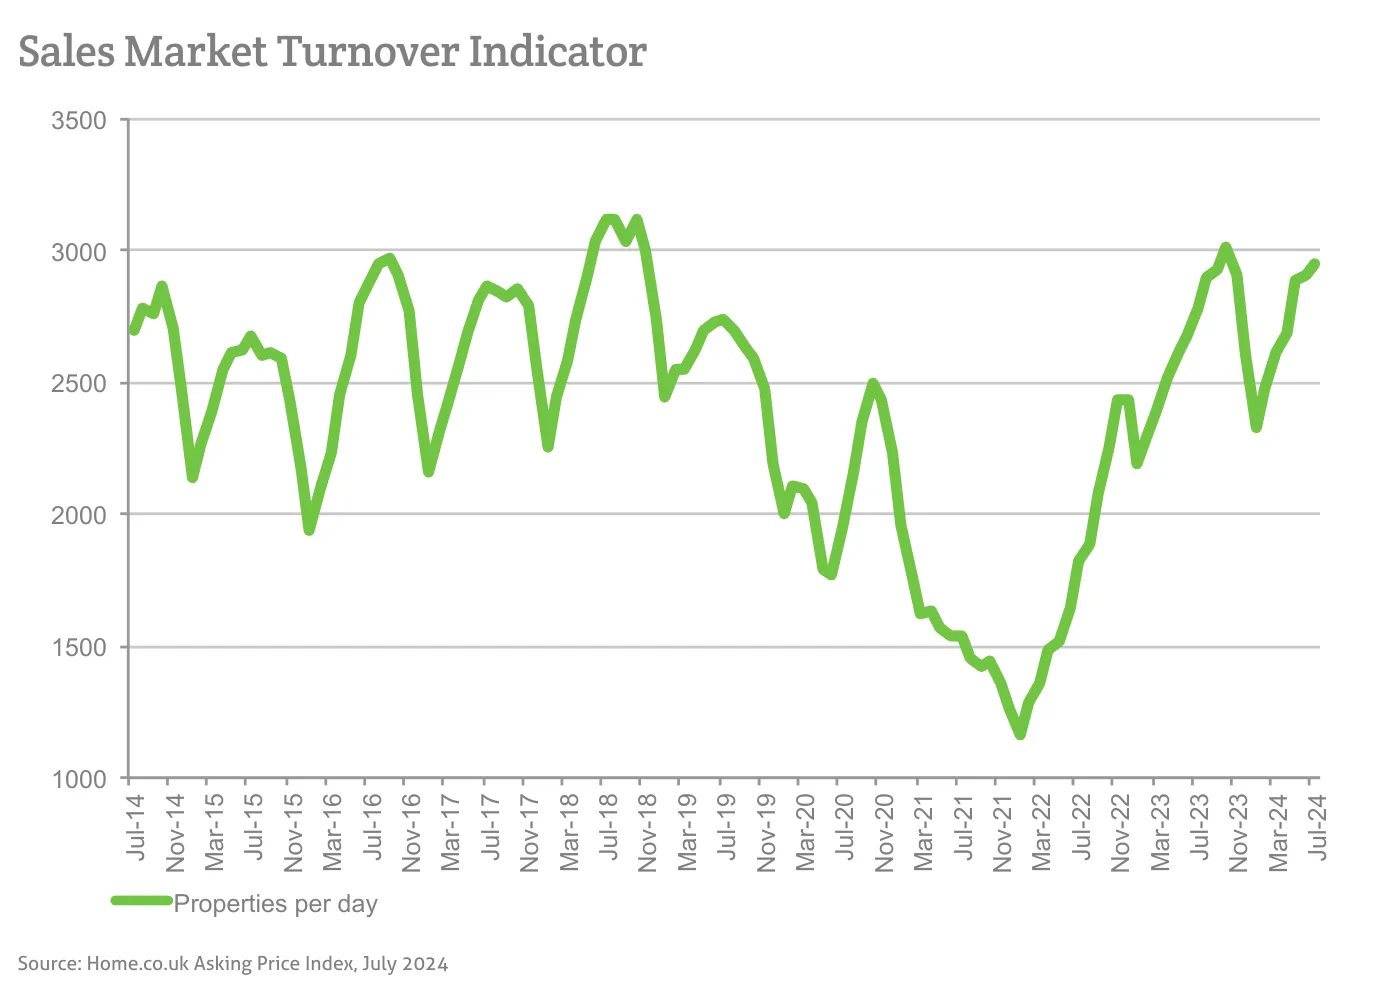
Source: Home.co.uk Asking Price Index, July 2024
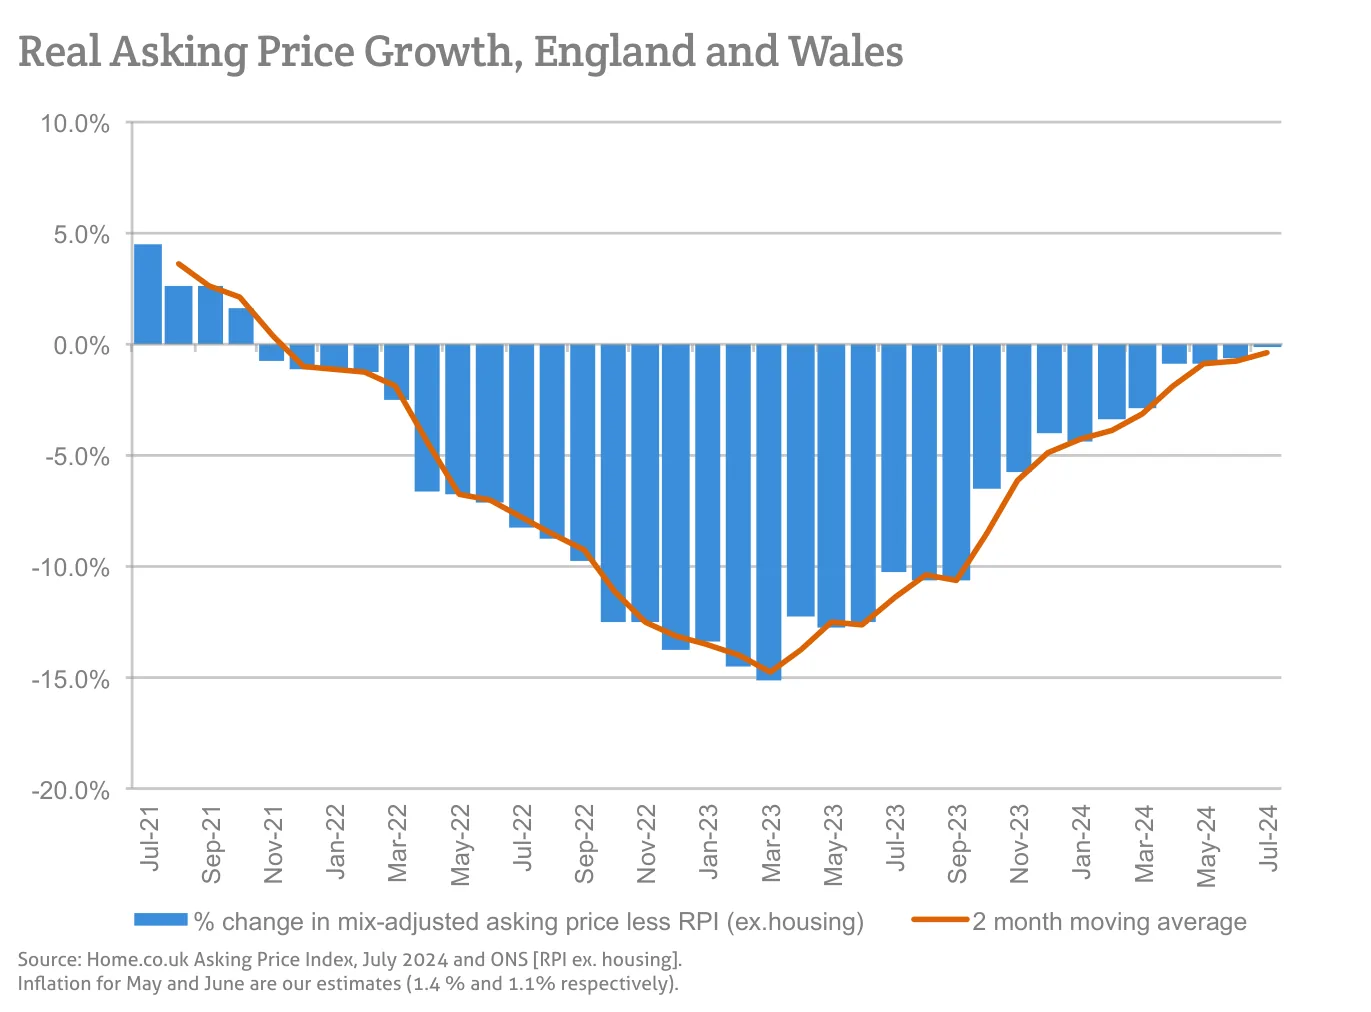
Source: Home.co.uk Asking Price Index, July 2024 and ONS [RPI ex. housing].
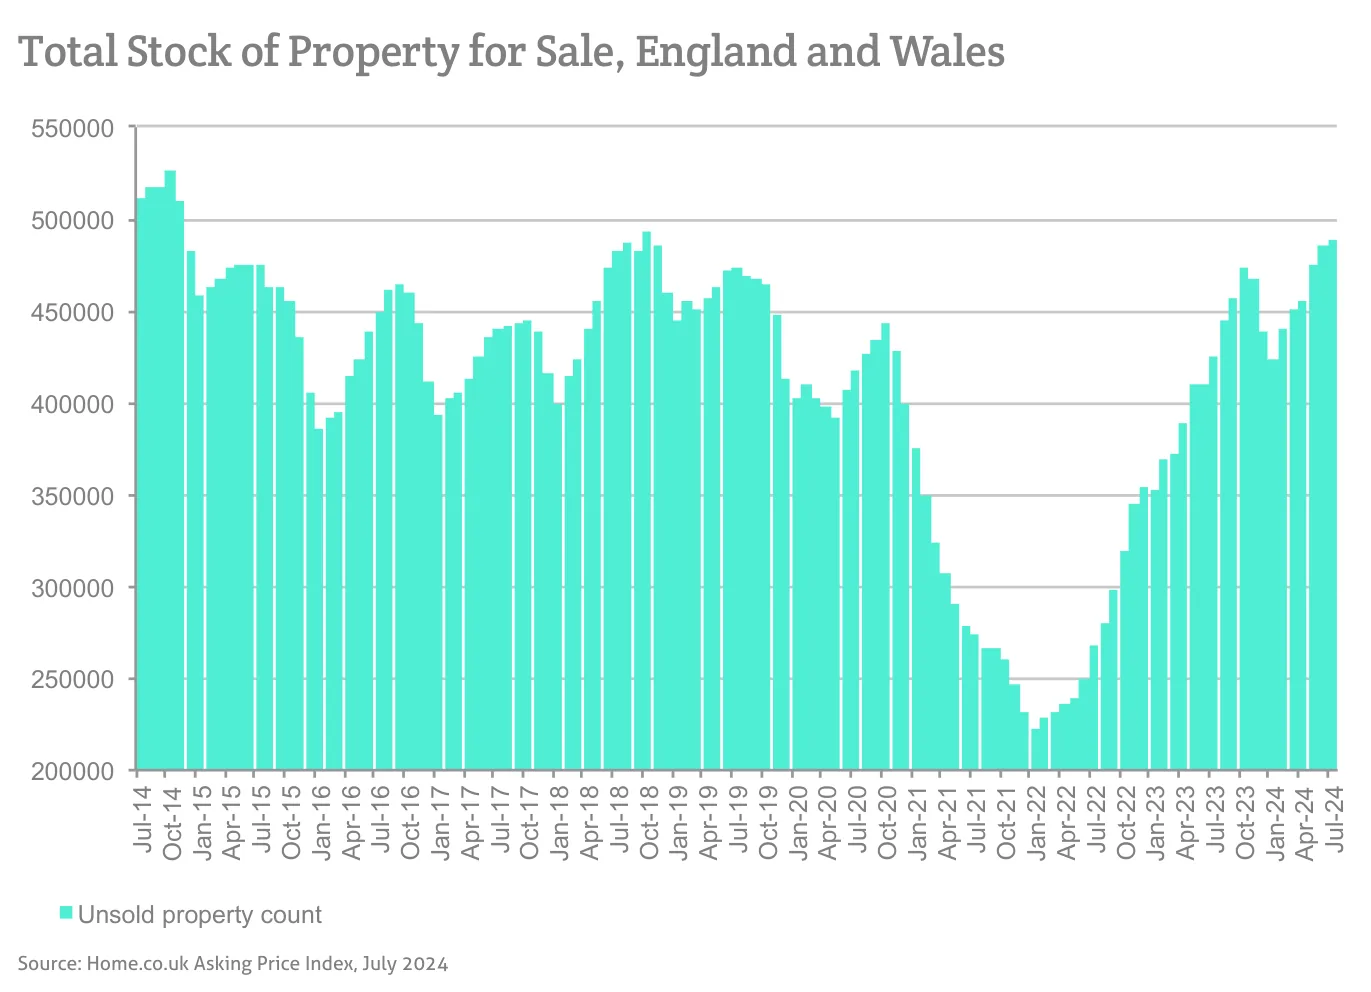
Source: Home.co.uk Asking Price Index, July 2024
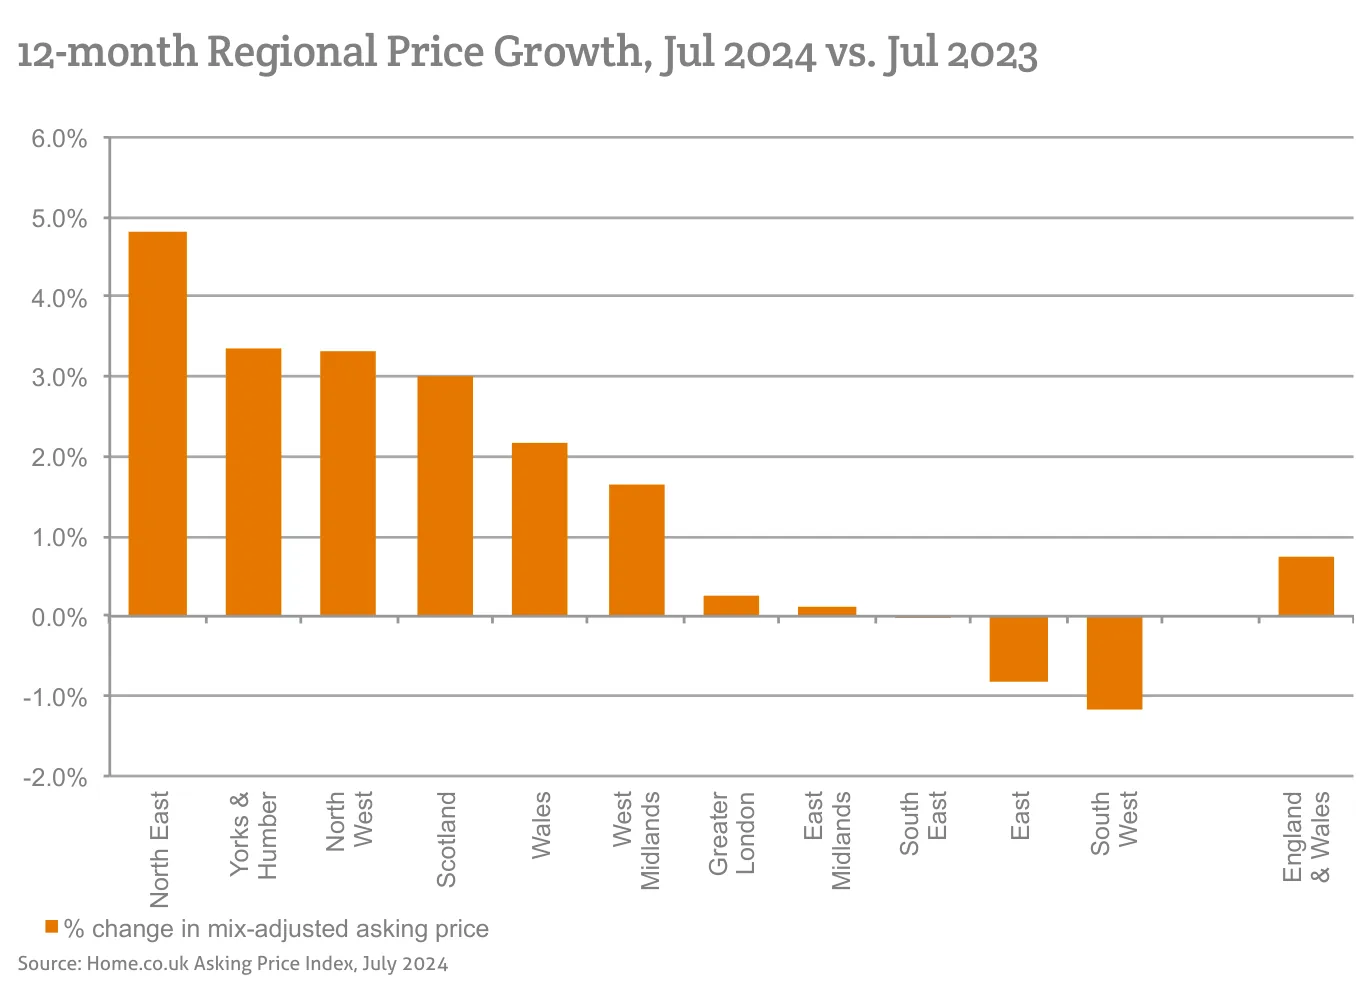
Source: Home.co.uk Asking Price Index, July 2024
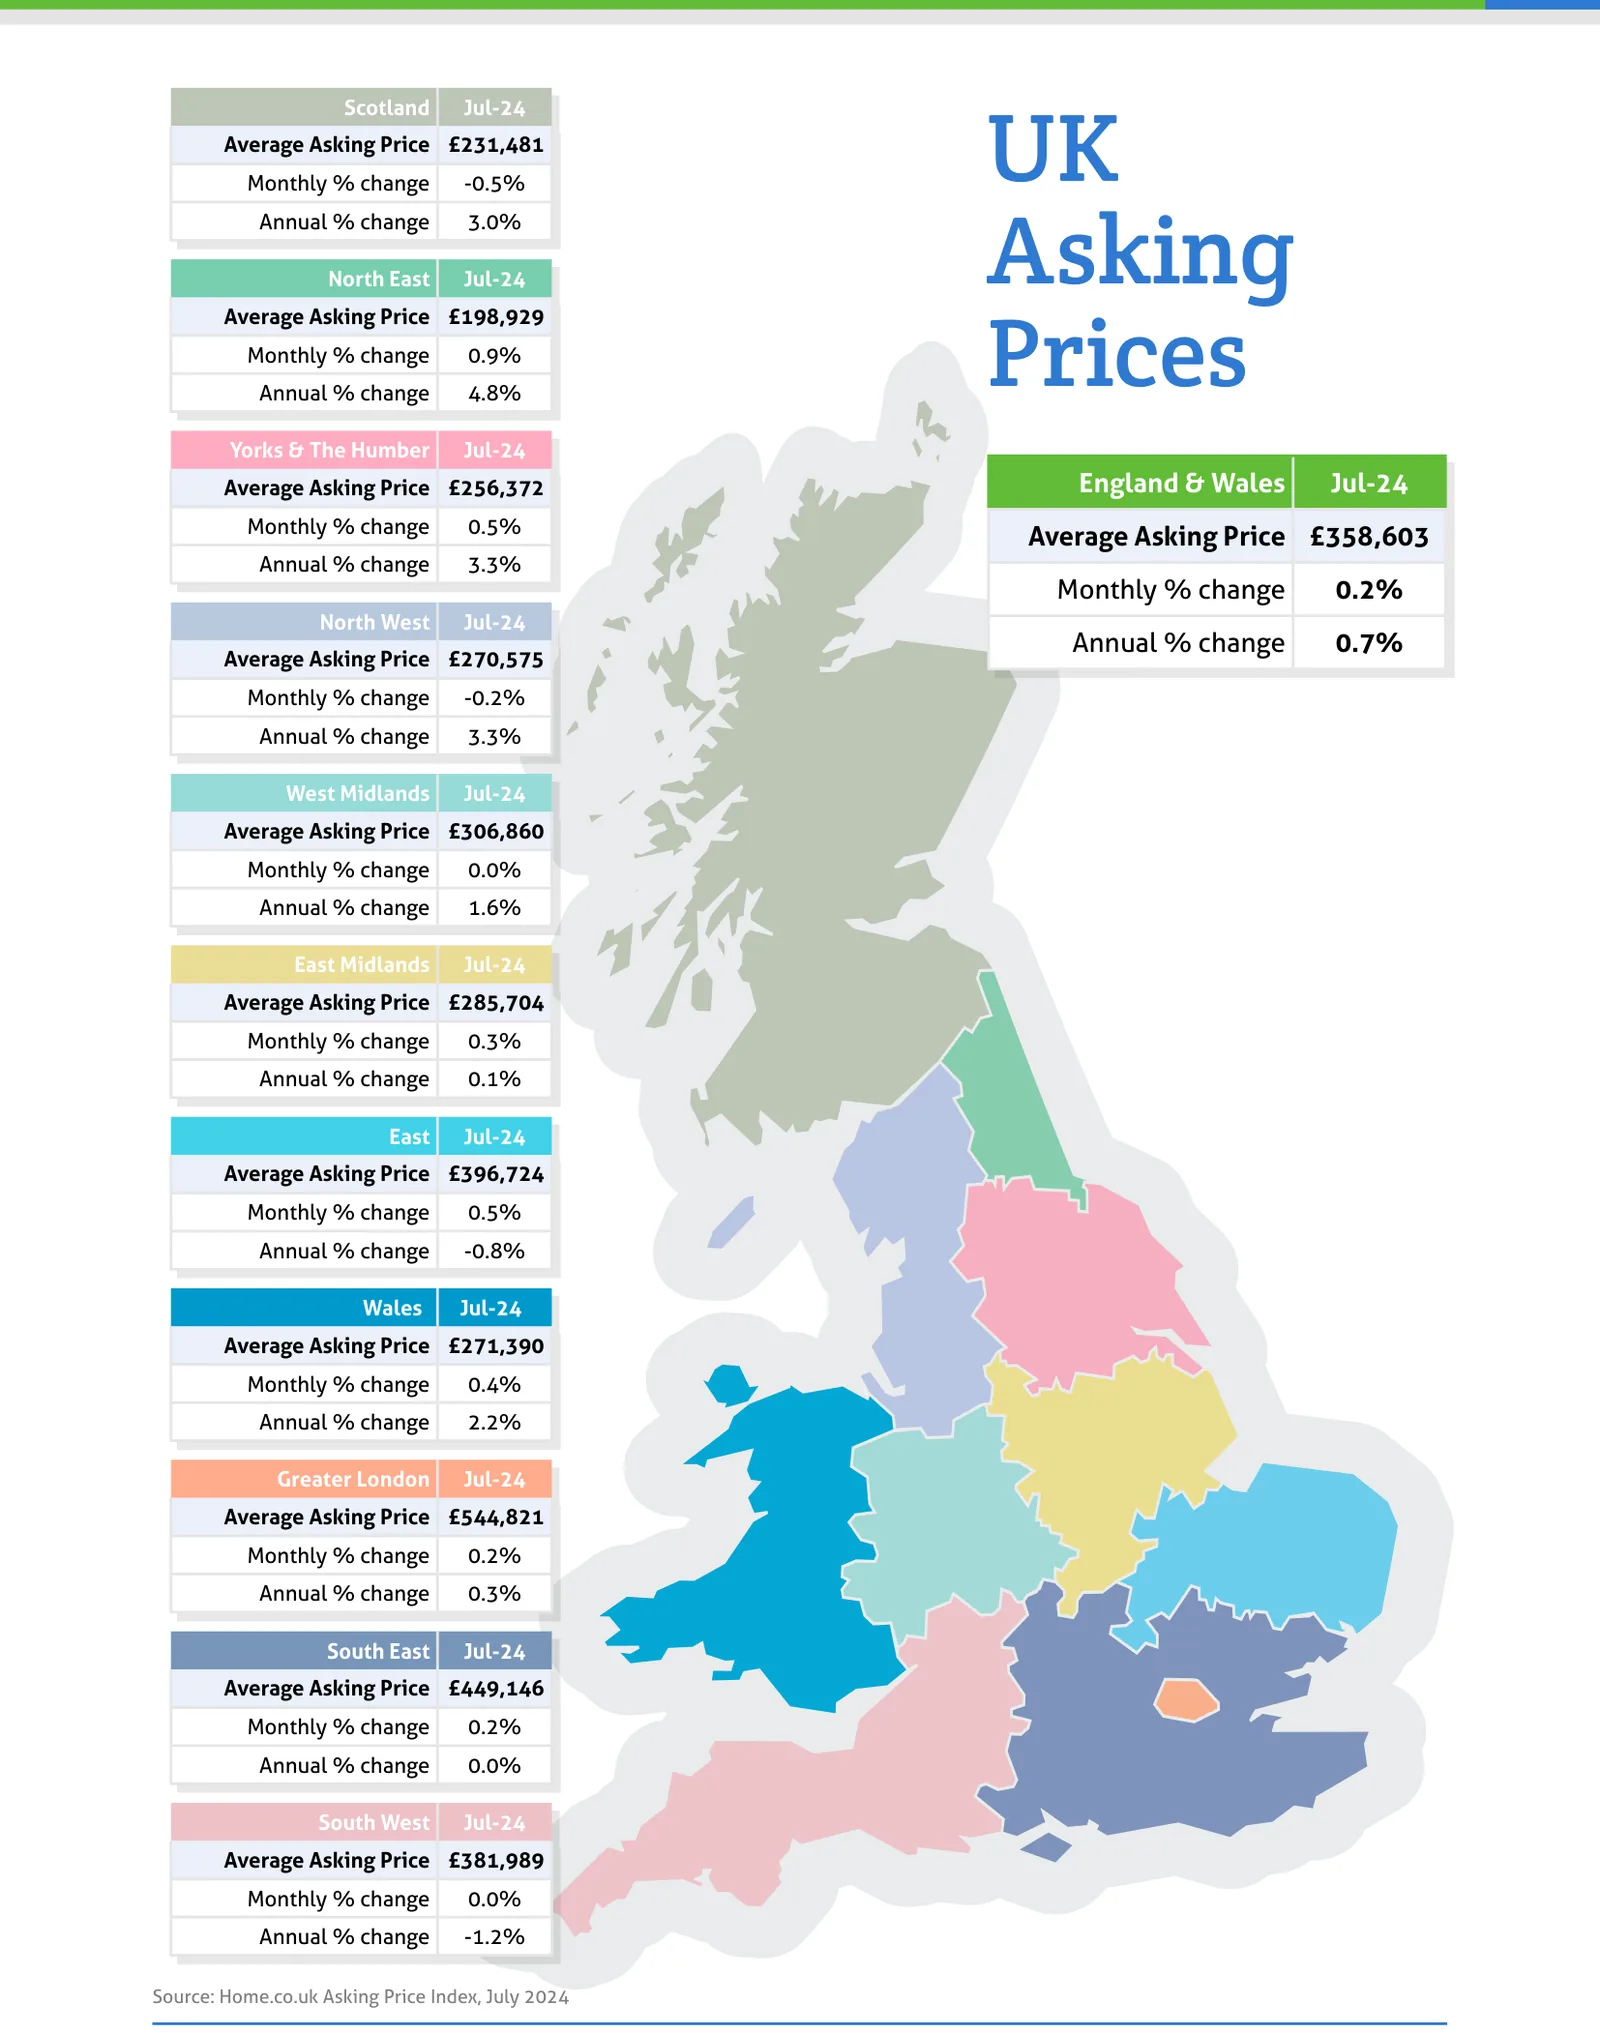
Source: Home.co.uk Asking Price Index, July 2024
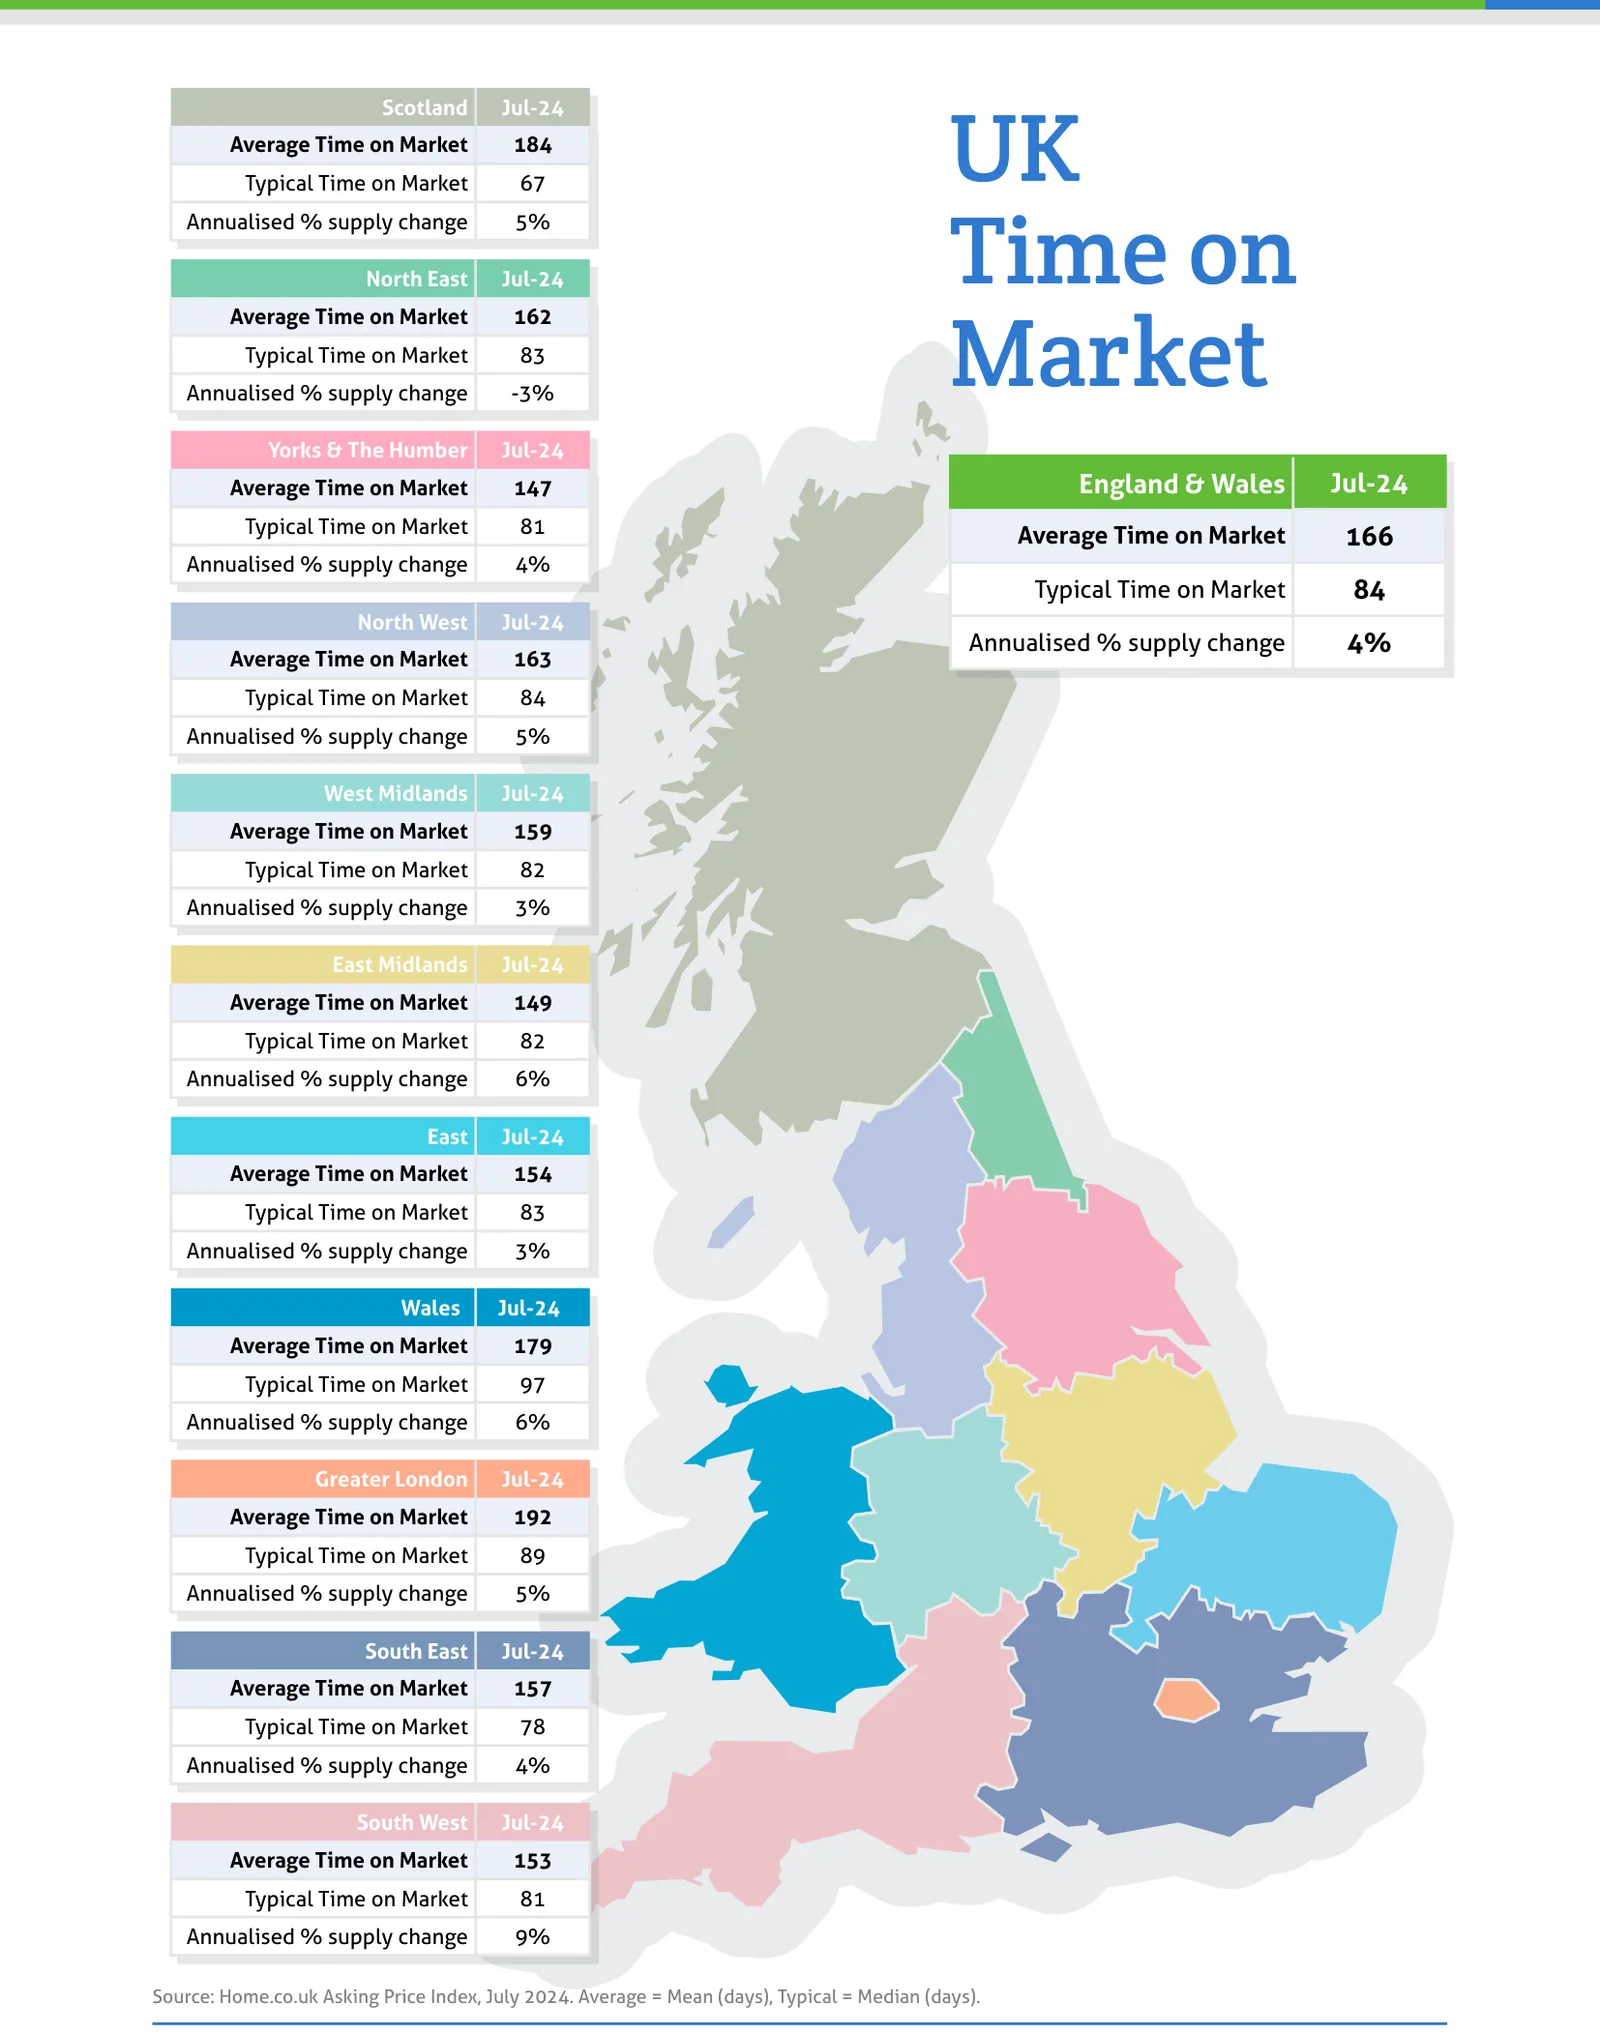
Source: Home.co.uk Asking Price Index, July 2024. Average = Mean (days), Typical = Median (days).
Regional tables
UK Asking Prices, Jul-24
| Region | Average Asking Price | Monthly % change | Annual % change |
|---|---|---|---|
| Scotland | £231,481 | -0.5% | 3.0% |
| North East | £198,929 | 0.9% | 4.8% |
| Yorks & The Humber | £256,372 | 0.5% | 3.3% |
| England & Wales | £358,603 | 0.2% | 0.7% |
| North West | £270,575 | -0.2% | 3.3% |
| West Midlands | £306,860 | 0.0% | 1.6% |
| East Midlands | £285,704 | 0.3% | 0.1% |
| East | £396,724 | 0.5% | -0.8% |
| Wales | £271,390 | 0.4% | 2.2% |
| Greater London | £544,821 | 0.2% | 0.3% |
| South East | £449,146 | 0.2% | 0.0% |
| South West | £381,989 | 0.0% | -1.2% |
UK Time on Market, Jul-24
| Region | Average Time on Market | Typical Time on Market | Annualised % supply change |
|---|---|---|---|
| Scotland | 184 | 67 | 5% |
| North East | 162 | 83 | -3% |
| Yorks & The Humber | 147 | 81 | 4% |
| England & Wales | 166 | 84 | 4% |
| North West | 163 | 84 | 5% |
| West Midlands | 159 | 82 | 3% |
| East Midlands | 149 | 82 | 6% |
| East | 154 | 83 | 3% |
| Wales | 179 | 97 | 6% |
| Greater London | 192 | 89 | 5% |
| South East | 157 | 78 | 4% |
| South West | 153 | 81 | 9% |
From the director's commentary
"In any case, reducing interest rates to around 2-3% would radically improve both the economy and the state of public finances."
Doug Shephard, Director at Home.co.uk
Read the full July 2024 edition (PDF, 11 pages)
About the Home Asking Price Index
The Home Asking Price Index measures the change in the prices sellers ask for residential property across England, Wales and Scotland. Today it is computed every month from around half a million advertised homes and is mix-adjusted, so a change in what happens to be on the market does not move the figure; earlier editions state the sample they were built from. Because an asking price is set months before a sale completes, the index runs around five months ahead of completed-sale measures such as the UK House Price Index.
Every edition in the archive, back to October 2006, is listed on the index page. How we measure the UK property market explains the listing data behind it, and today's figures by area are on house prices and rental prices.
Text and figures above are quoted from the July 2024 edition as published, with punctuation normalised for the web, and are not revised. Later editions may restate them.
More in What is happening to house prices: the Home guide
Thinking about your next move?
See what your home's worth in seconds, with the UK's longest-running property data behind it.
Get an instant valuation