Home Asking Price Index, February 2025: oversupply weighs heavy on pricing in London and the South
England and Wales asking prices fell 0.1% in February as oversupply in London and the South East dragged down pricing, leaving annual growth at 1.7%.
This is the February 2025 edition of the Home Asking Price Index, released on 19 February 2025, under the headline:
Oversupply Weighs Heavy on Pricing in London and the South
The headlines and summary below are the report's own words, with the key figures as it published them, followed by the report's charts and regional tables as printed.
Headlines
- The expected seasonal rise in the national average asking price failed to materialise during the last month due to weaker pricing in London, the South East and the South West. Overall, asking prices have slipped by 0.1% since the January reading across England and Wales. Annualised home price growth is now just 1.7% overall.
- The total number of new instructions entering the market during January 2025 was 10% more than during January 2024. Oversupply is indicated in London and the South East which both show the highest regional increases, up by 21% and 13% respectively.
- Pricing remains strong in the North with Yorkshire and Scotland posting the largest month-on-month gains of 0.8% and 0.6% respectively.
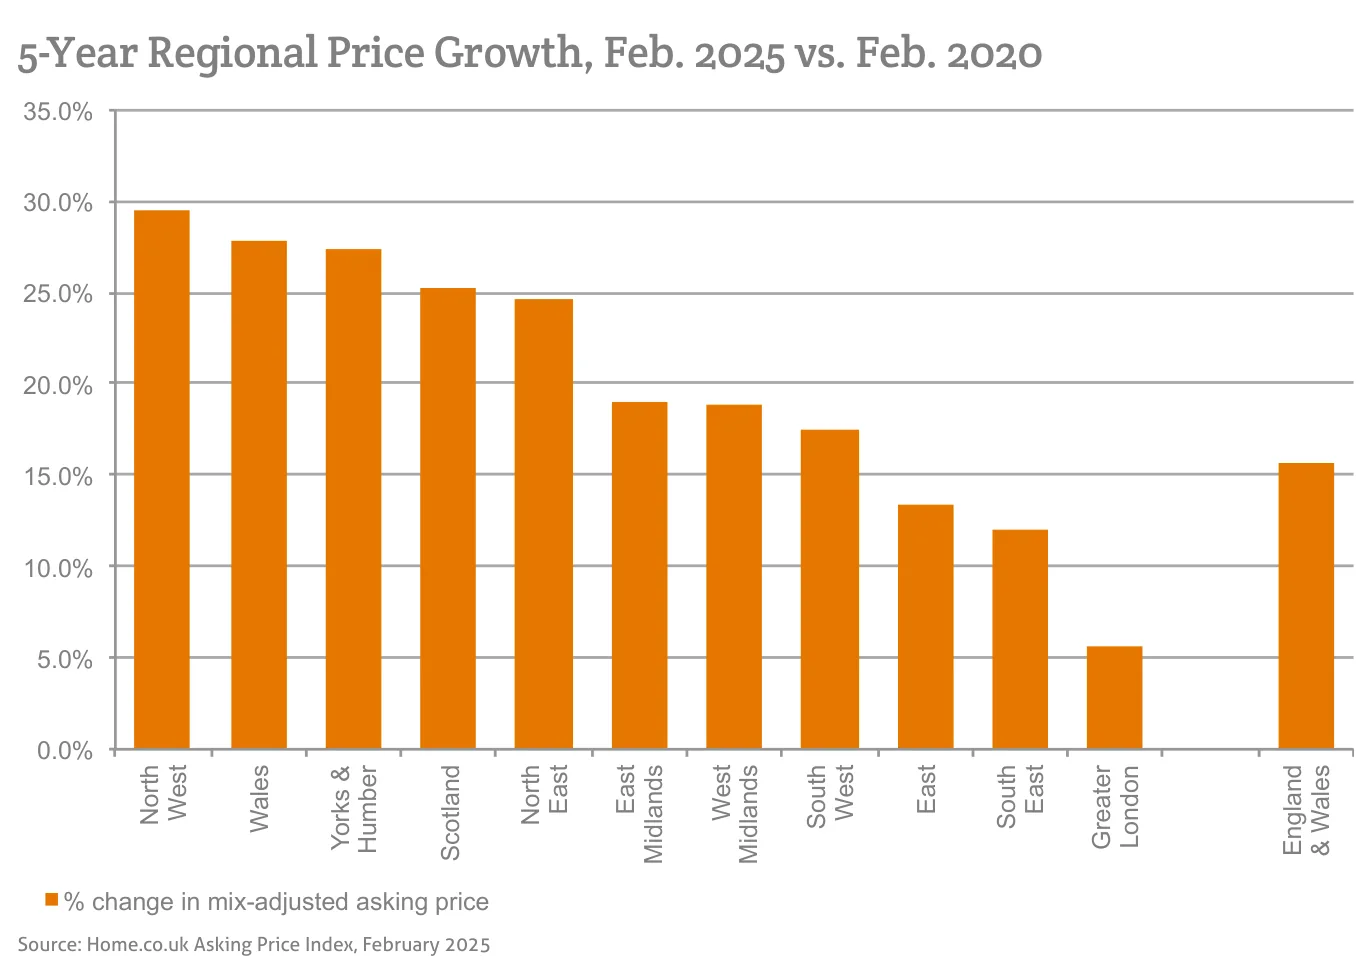
- The North East cedes its top position in regional property market growth to Yorkshire which becomes the new leader with a year-on-year gain of 5.2%. Meanwhile, the South East replaces the East of England as the worst regional performer with an annualised gain of just 0.1%.
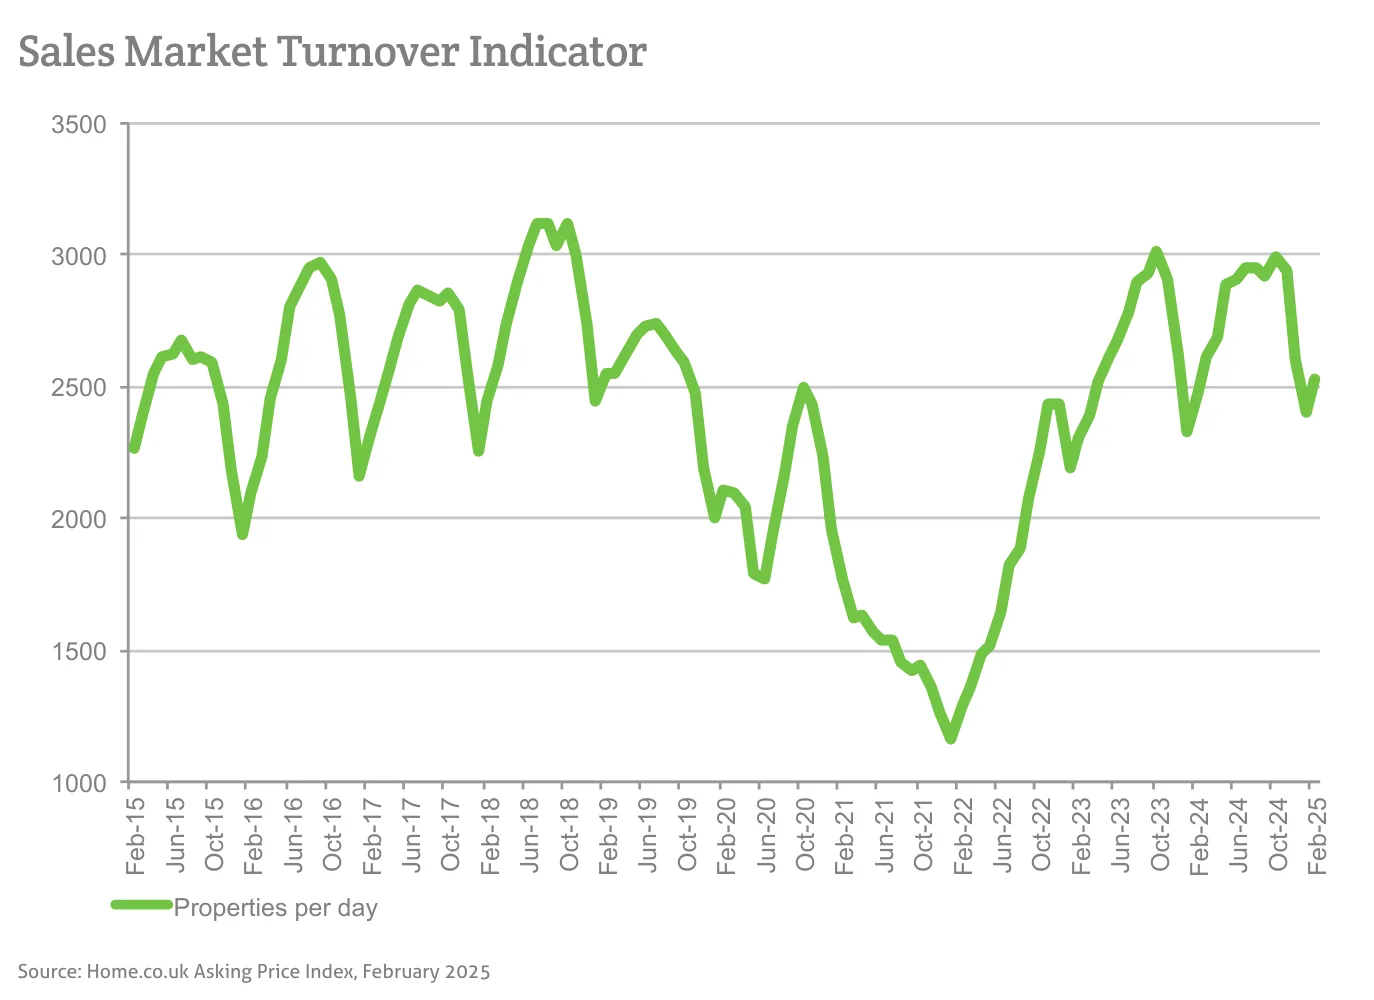
- For the time being, the UK property market continues to show significant momentum. Property turnover remains higher than the previous two February readings and the three February readings prior to the COVID event.
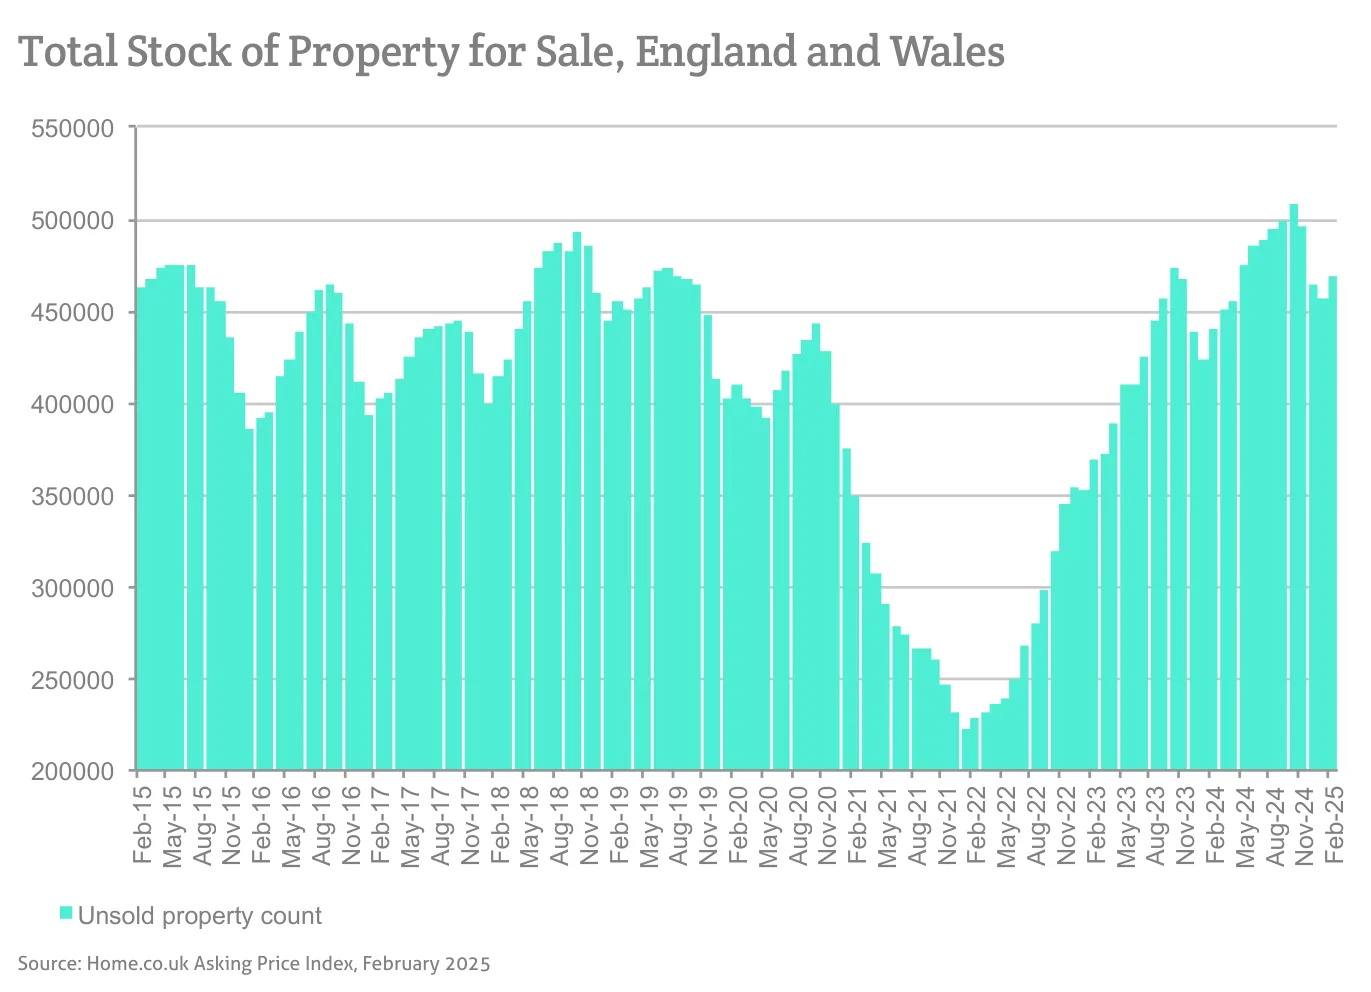
- The unsold sales stock count for England and Wales increased by around 13,000 properties during the last month, which is slightly above seasonal expectations. The current total of 469,279 is the largest February figure since 2013.
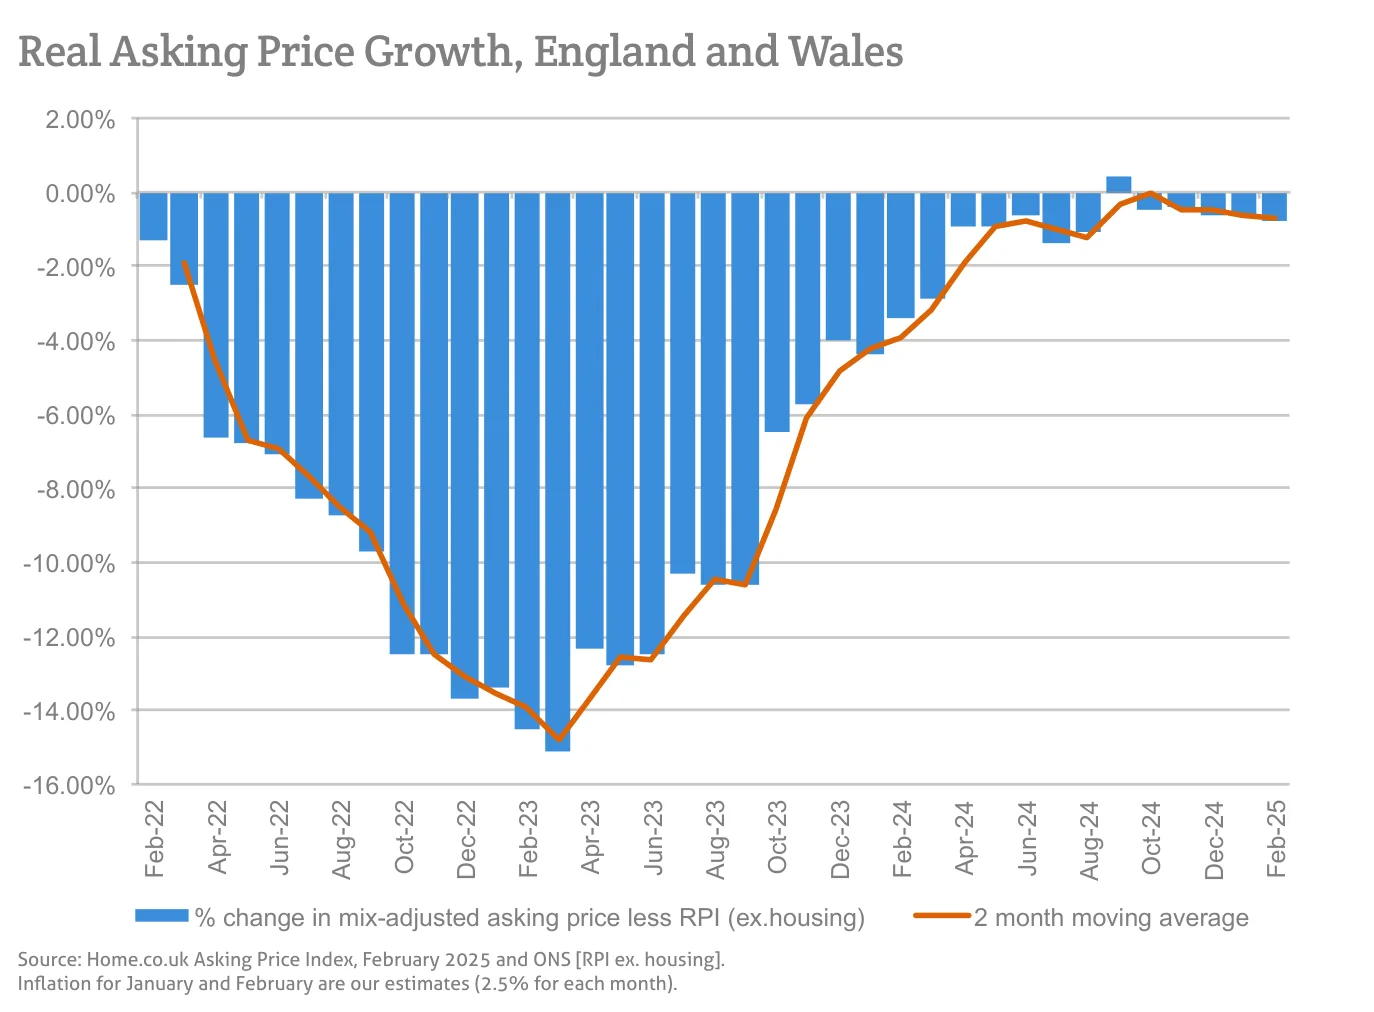
- Overall, price growth in the sales market continues to underperform relative to monetary inflation.
- At just 1.9%, annualised national growth in asking rents is also behind the rate of inflation. This mix-adjusted average is affected disproportionately by London's rent falls (-0.5%). However, the best performing region, the East Midlands, indicates 10.2% rental growth year-on-year.
- The City of London followed by Hounslow indicate the largest declines in asking rents of all London boroughs, with annualised rental falls of 18.9% and 7.7% respectively. Meanwhile, the best performers are Kingston-upon-Thames, Sutton and Wandsworth, with rents increasing by 8.9%, 8.8% and 8.3% respectively.
Summary
Reality bites as Greater London, the South East and the South West resort to competitive pricing in the face of a twelve-year high in stock levels. Contrary to seasonal expectations, the mix-adjusted national average asking price has dipped since last month, driven by significantly lower pricing in these three regions. Even the Bank of England's cut in the base rate, which was arguably already priced into mortgage rates, was not enough to bolster confidence in a property market plagued by increasing taxation and regulation. Consequently, vendors in these regions are increasingly willing to take a hit on their expectations in order to secure a sale.
In stark contrast, vendors in the North and Scotland are much more confident in their pricing. Among these top performing regions, Yorkshire indicated the largest monthly rise of 0.8%, seemingly a world apart from the pain felt in the South. Undoubtedly, the relative performance of the Private Rented Sector (PRS) is a key factor in the North-South divide. Yields remain significantly better in the North and this factor does not look set to change soon. In certain postal districts of London and the South East, rental yields are less than 3%; certainly not enough to pay a significant mortgage and all the other associated expenses. Meanwhile, savvy investors can find yields as high as 12% in certain postal districts, all of which are to be found in the North.
Key figures
| Measure | Figure |
|---|---|
| Monthly change in asking prices | -0.1% |
| Annual change in asking prices | +1.7% |
| New instructions growth (year-on-year) | +10% |
| Unsold sales stock total | 469,279 |
| Monthly increase in unsold stock | +13,000 |
| Annual asking rent growth | +1.9% |
Figures are for England and Wales unless the report states otherwise, as published in the edition.
Charts from the report
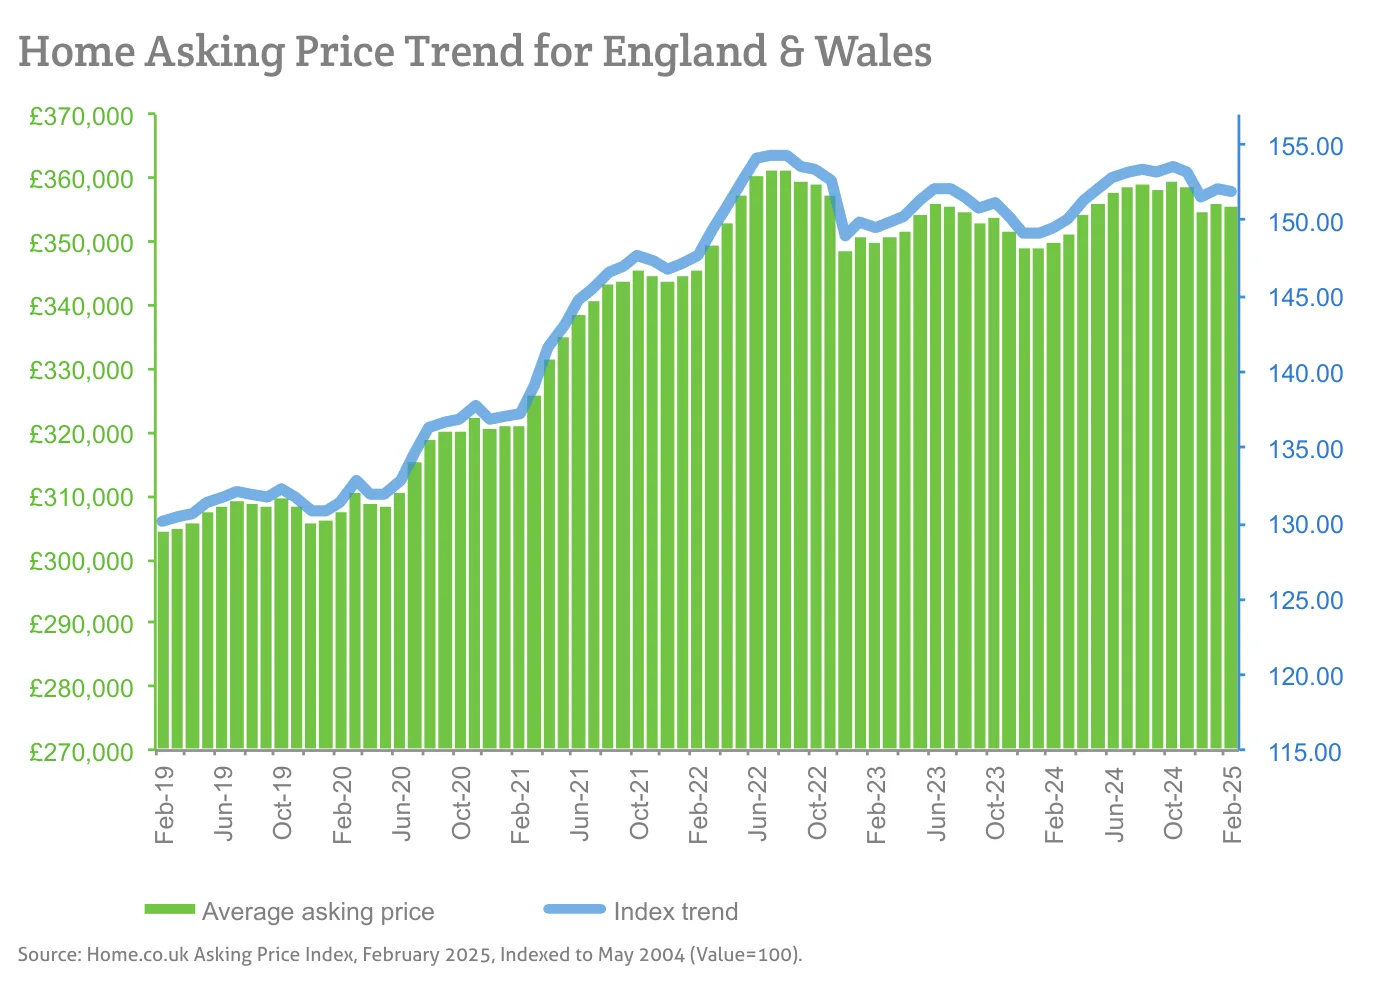
Source: Home.co.uk Asking Price Index, February 2025, Indexed to May 2004 (Value=100).
Source: Home.co.uk Asking Price Index, February 2025
Source: Home.co.uk Asking Price Index, February 2025 and ONS [RPI ex. housing].
Source: Home.co.uk Asking Price Index, February 2025
Source: Home.co.uk Asking Price Index, February 2025
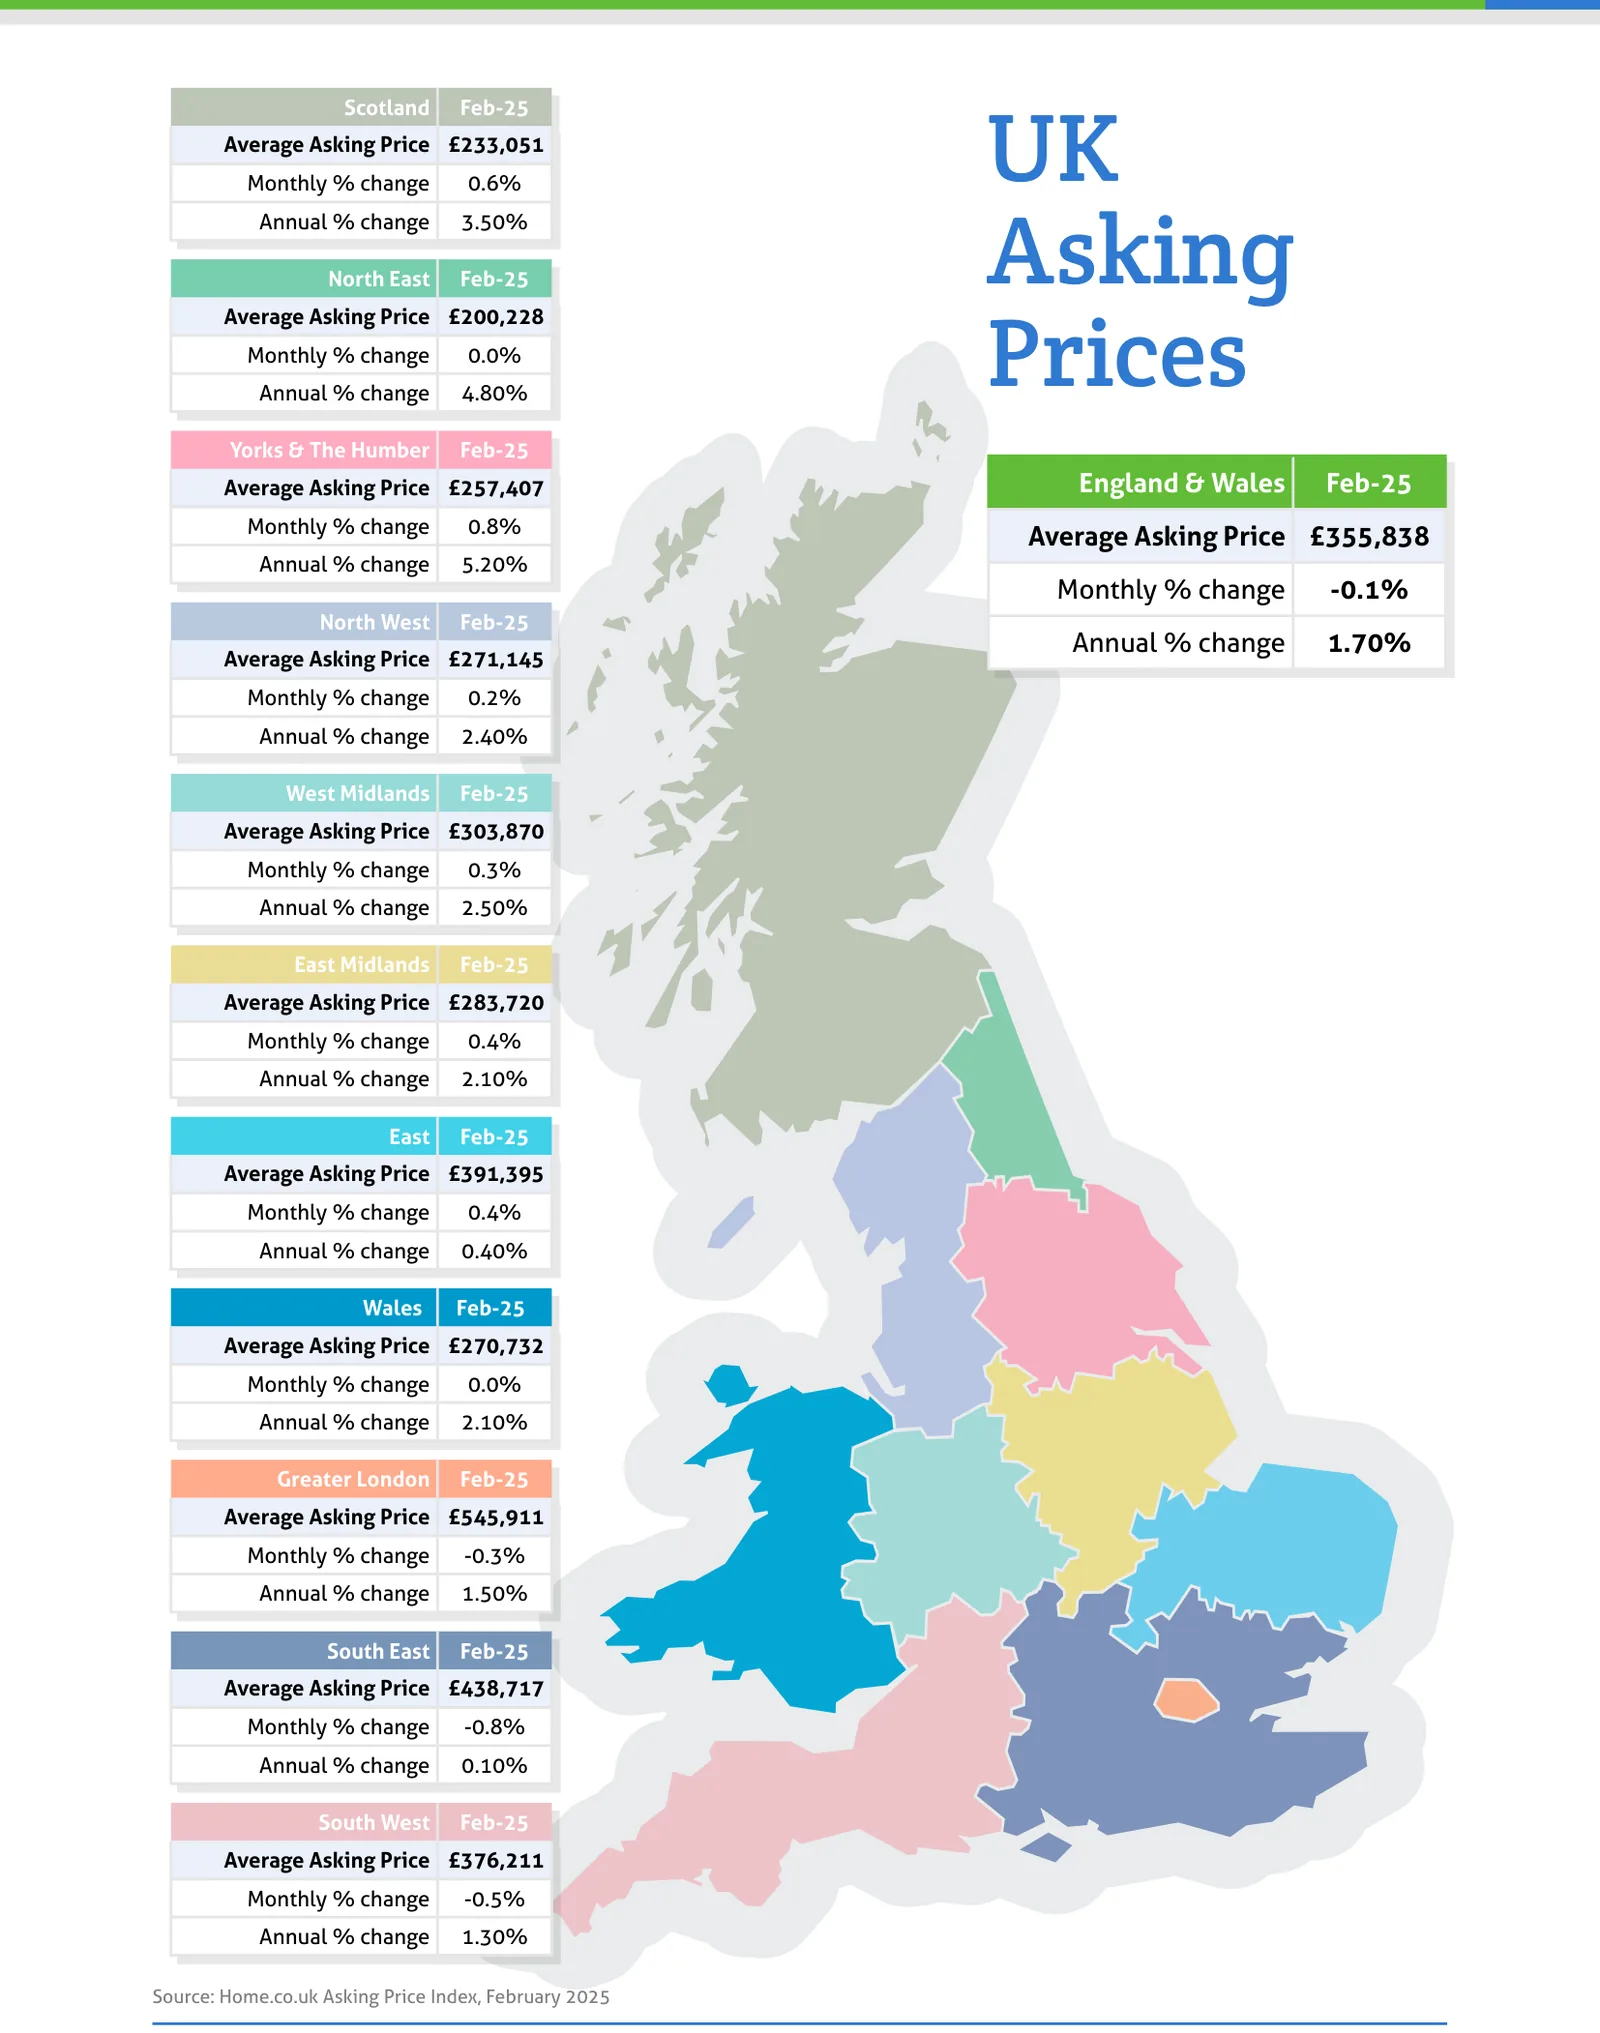
Source: Home.co.uk Asking Price Index, February 2025
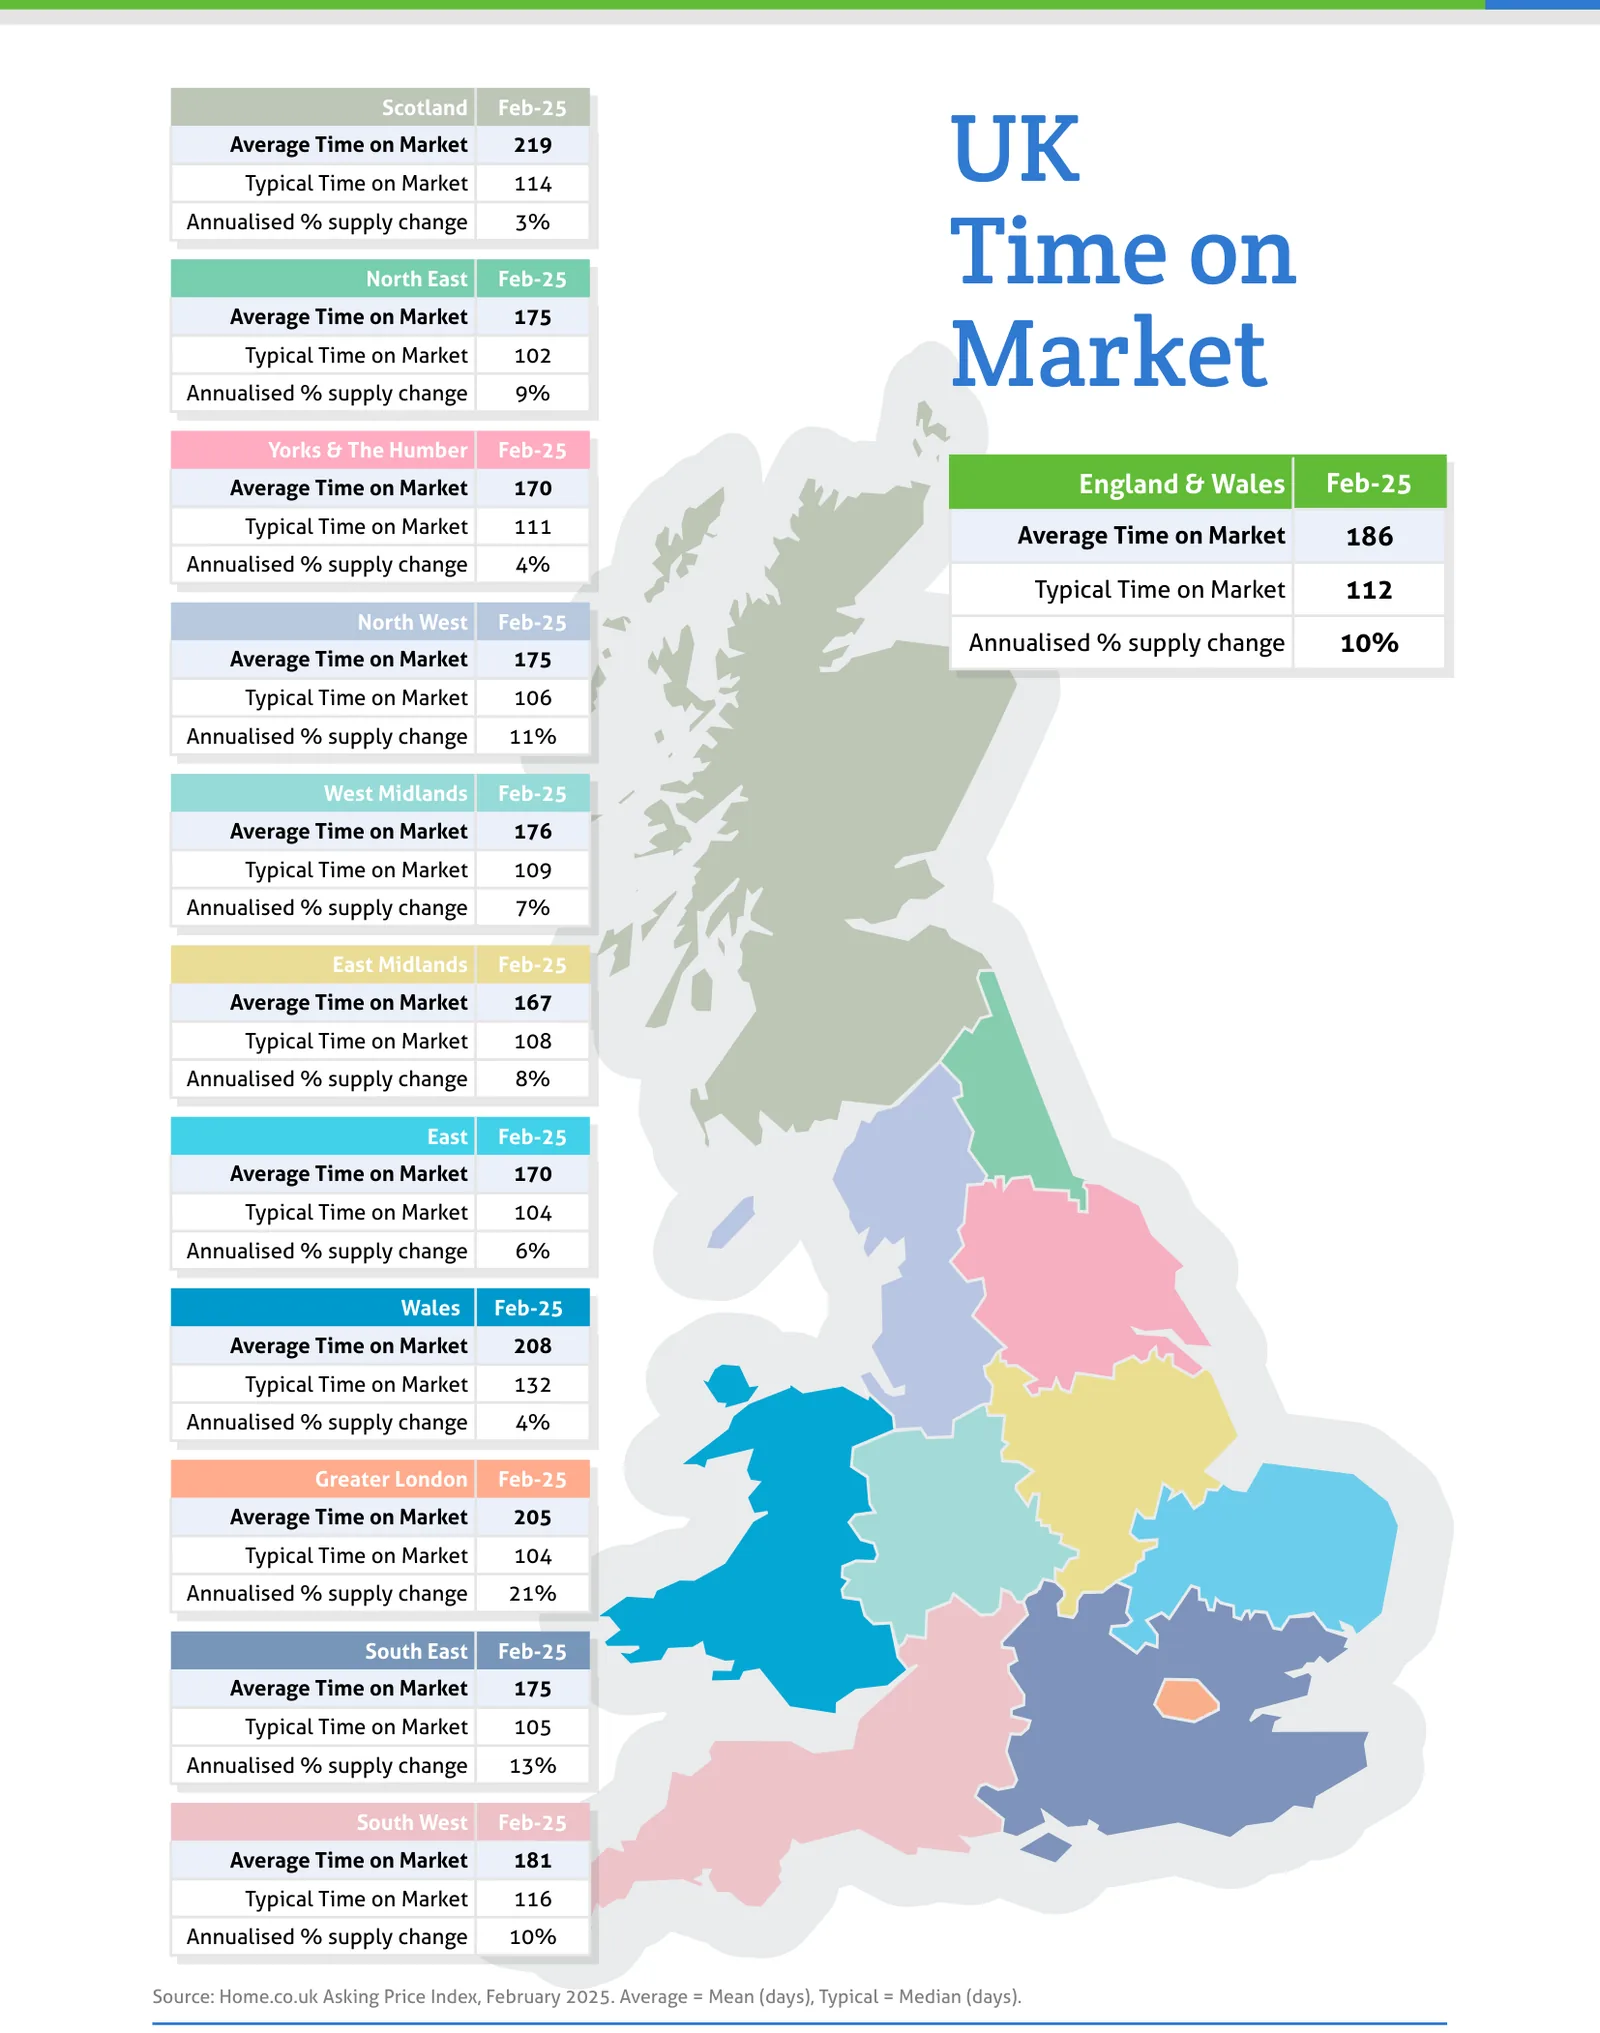
Source: Home.co.uk Asking Price Index, February 2025. Average = Mean (days), Typical = Median (days).
Regional tables
UK Asking Prices, Feb-25
| Region | Average Asking Price | Monthly % change | Annual % change |
|---|---|---|---|
| Scotland | £233,051 | 0.6% | 3.50% |
| North East | £200,228 | 0.0% | 4.80% |
| Yorks & The Humber | £257,407 | 0.8% | 5.20% |
| England & Wales | £355,838 | -0.1% | 1.70% |
| North West | £271,145 | 0.2% | 2.40% |
| West Midlands | £303,870 | 0.3% | 2.50% |
| East Midlands | £283,720 | 0.4% | 2.10% |
| East | £391,395 | 0.4% | 0.40% |
| Wales | £270,732 | 0.0% | 2.10% |
| Greater London | £545,911 | -0.3% | 1.50% |
| South East | £438,717 | -0.8% | 0.10% |
| South West | £376,211 | -0.5% | 1.30% |
UK Time on Market, Feb-25
| Region | Average Time on Market | Typical Time on Market | Annualised % supply change |
|---|---|---|---|
| Scotland | 219 | 114 | 3% |
| North East | 175 | 102 | 9% |
| Yorks & The Humber | 170 | 111 | 4% |
| England & Wales | 186 | 112 | 10% |
| North West | 175 | 106 | 11% |
| West Midlands | 176 | 109 | 7% |
| East Midlands | 167 | 108 | 8% |
| East | 170 | 104 | 6% |
| Wales | 208 | 132 | 4% |
| Greater London | 205 | 104 | 21% |
| South East | 175 | 105 | 13% |
| South West | 181 | 116 | 10% |
From the director's commentary
"The upshot of such a massive exodus from the PRS would be catastrophic for both the sales and rental markets. Such a tsunami of additional sales stock in just one year would completely crash the sales market and the squeeze on rental supply would drive rents through the roof."
Doug Shephard, Director at Home.co.uk
Read the full February 2025 edition (PDF, 11 pages)
About the Home Asking Price Index
The Home Asking Price Index measures the change in the prices sellers ask for residential property across England, Wales and Scotland. Today it is computed every month from around half a million advertised homes and is mix-adjusted, so a change in what happens to be on the market does not move the figure; earlier editions state the sample they were built from. Because an asking price is set months before a sale completes, the index runs around five months ahead of completed-sale measures such as the UK House Price Index.
Every edition in the archive, back to October 2006, is listed on the index page. How we measure the UK property market explains the listing data behind it, and today's figures by area are on house prices and rental prices.
Text and figures above are quoted from the February 2025 edition as published, with punctuation normalised for the web, and are not revised. Later editions may restate them.
More in What is happening to house prices: the Home guide
Thinking about your next move?
See what your home's worth in seconds, with the UK's longest-running property data behind it.
Get an instant valuation