Home Asking Price Index, February 2024: spring optimism permeates the market
Asking prices in England and Wales rose 0.2% month on month but remain 0.1% lower year-on-year, with unsold stock reaching 440,674 properties.
This is the February 2024 edition of the Home Asking Price Index, released on 14 February 2024, under the headline:
Spring Optimism Permeates the Market
The headlines and summary below are the report's own words, with the key figures as it published them, followed by the report's charts and regional tables as printed.
Headlines
- Asking prices show a spring lift of 0.2% since last month across England and Wales but are down year-on-year, albeit by a mere 0.1% vs. Feb 2023.
- Prices rose in six English regions and Scotland and Wales during the last month, indicating significant vendor optimism. Prices slipped marginally in just three regions, namely Greater London, the East Midlands and the South West.
- The total sales stock count for England and Wales has risen in line with seasonal expectations. The current total of unsold property is 440,674, around 16,800 more than last month.
- The number of new instructions entering the market during January 2024 was 14% more than during January 2023. This jump may be explained by greater current optimism when compared to the market chaos caused by the doomed Truss-Kwarteng mini-budget. Compared to pre-COVID January 2019, supply is slightly down (by 2%).
- The Typical Time on Market for unsold property in England and Wales remains unchanged since January, again typical for the time of year. The current median is 112 days; in pre-COVID February 2020, the same measure was 116 days.
- The North West remains the regional property market growth league table leader with a year-on-year gain of 3.9%. The East Midlands replaces the East of England as the worst performer at -2.1%.
- Rent growth across the UK continues to slow, dragged down by London, reducing the annualised change to just +3.8%. The North East is now the regional leader in rental growth at +14.1% year-on-year. Greater London rents continue to decline (-3.4%), making it the worst performing region due to oversupply of property to let.
- Rents continue to fall in the more expensive central boroughs. Growth in the capital has become increasingly negative overall and a total of thirteen prime boroughs now show year-on-year falls in asking rents, up from twelve last month. The worst performer is Kensington and Chelsea with a year-on-year decline of 11.9%.
Summary
2023 was a difficult and worrisome year for the property market and consequently many potential buyers stayed away, choosing to wait and see. There is reason, therefore, to believe that at least some of this pent-up demand will be unleashed on the market this year. Current Typical Time on Market figures are consistent with pre-COVID years and we expect large reductions in marketing times in March and April.
Home prices enjoy a spring lift in line with seasonal expectations as the market picks up pace. Pricing suggests cautious optimism on the part of vendors and expectations of rising demand. Stock levels remain relatively low when compared to 2019 and other pre-COVID years, and this provides positive support for pricing. Annualised growth in home market values for England and Wales was notably absent overall in 2023 but the stage is now set for a return to capital appreciation. The northern regions and Wales and Scotland are already ahead of the curve in this respect.
At the regional level, Typical Time on Market figures indicate that the North of England, Scotland and Wales all continue to thrive, with activity over and above the pre-COVID years. Moreover, this enhanced momentum correlates closely with positive annualised price growth in those regions.
Key figures
| Measure | Figure |
|---|---|
| Monthly change in asking prices | +0.2% |
| Annual change in asking prices | -0.1% |
| Total unsold stock | 440,674 |
| Change in new instructions (Jan 2024 vs Jan 2023) | +14% |
| Change in supply vs pre-COVID Jan 2019 | -2% |
| Typical Time on Market | 112 days |
| Typical Time on Market pre-COVID (Feb 2020) | 116 days |
| UK rent annual growth | +3.9% |
Figures are for England and Wales unless the report states otherwise, as published in the edition.
Charts from the report
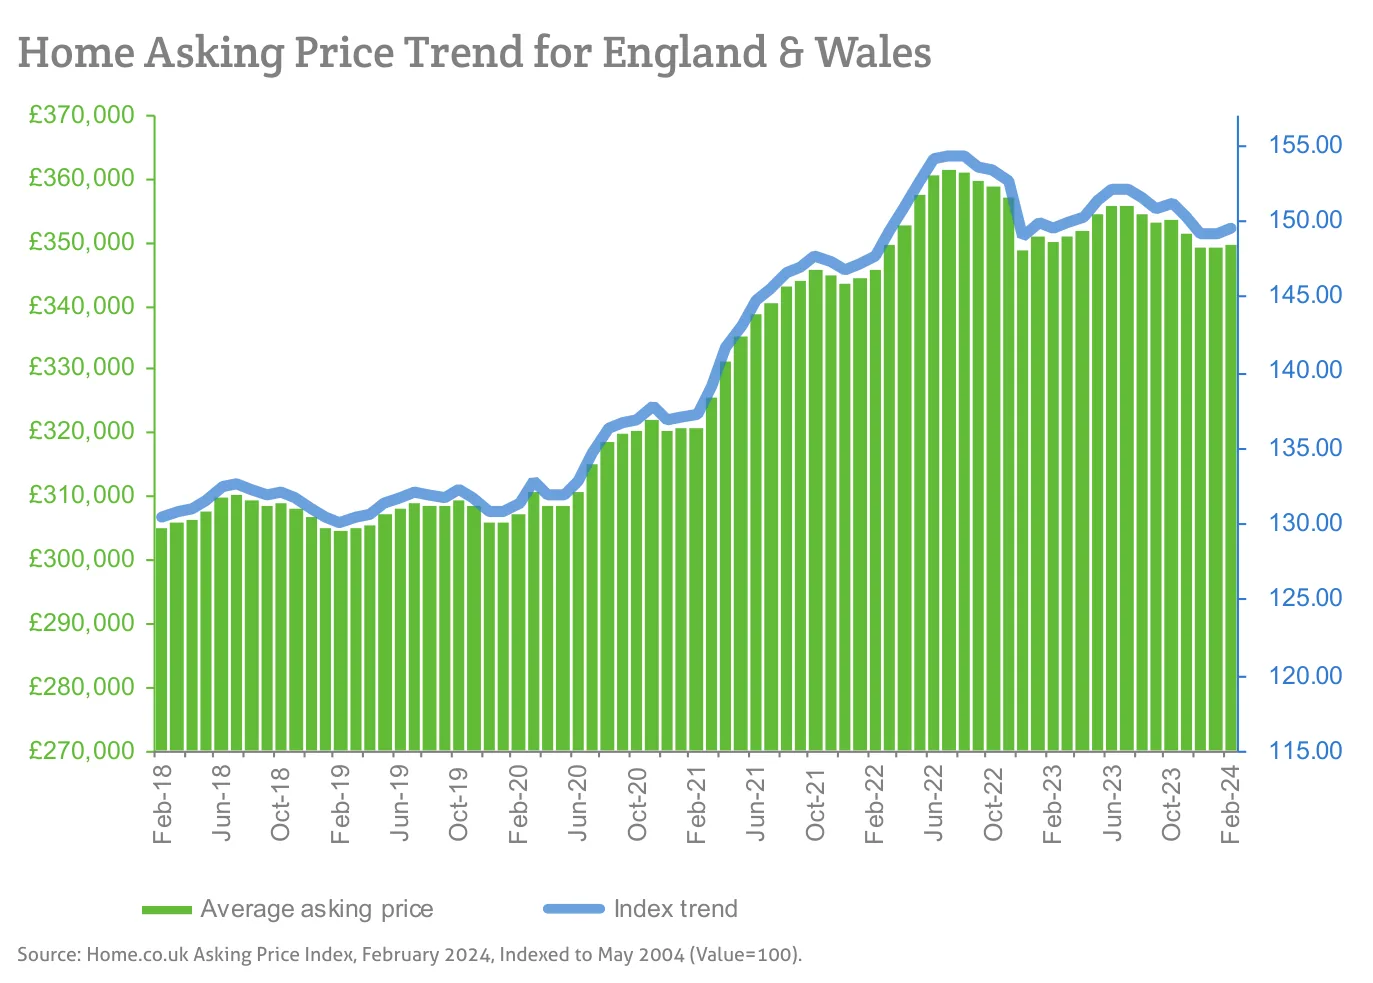
Source: Home.co.uk Asking Price Index, February 2024, Indexed to May 2004 (Value=100).
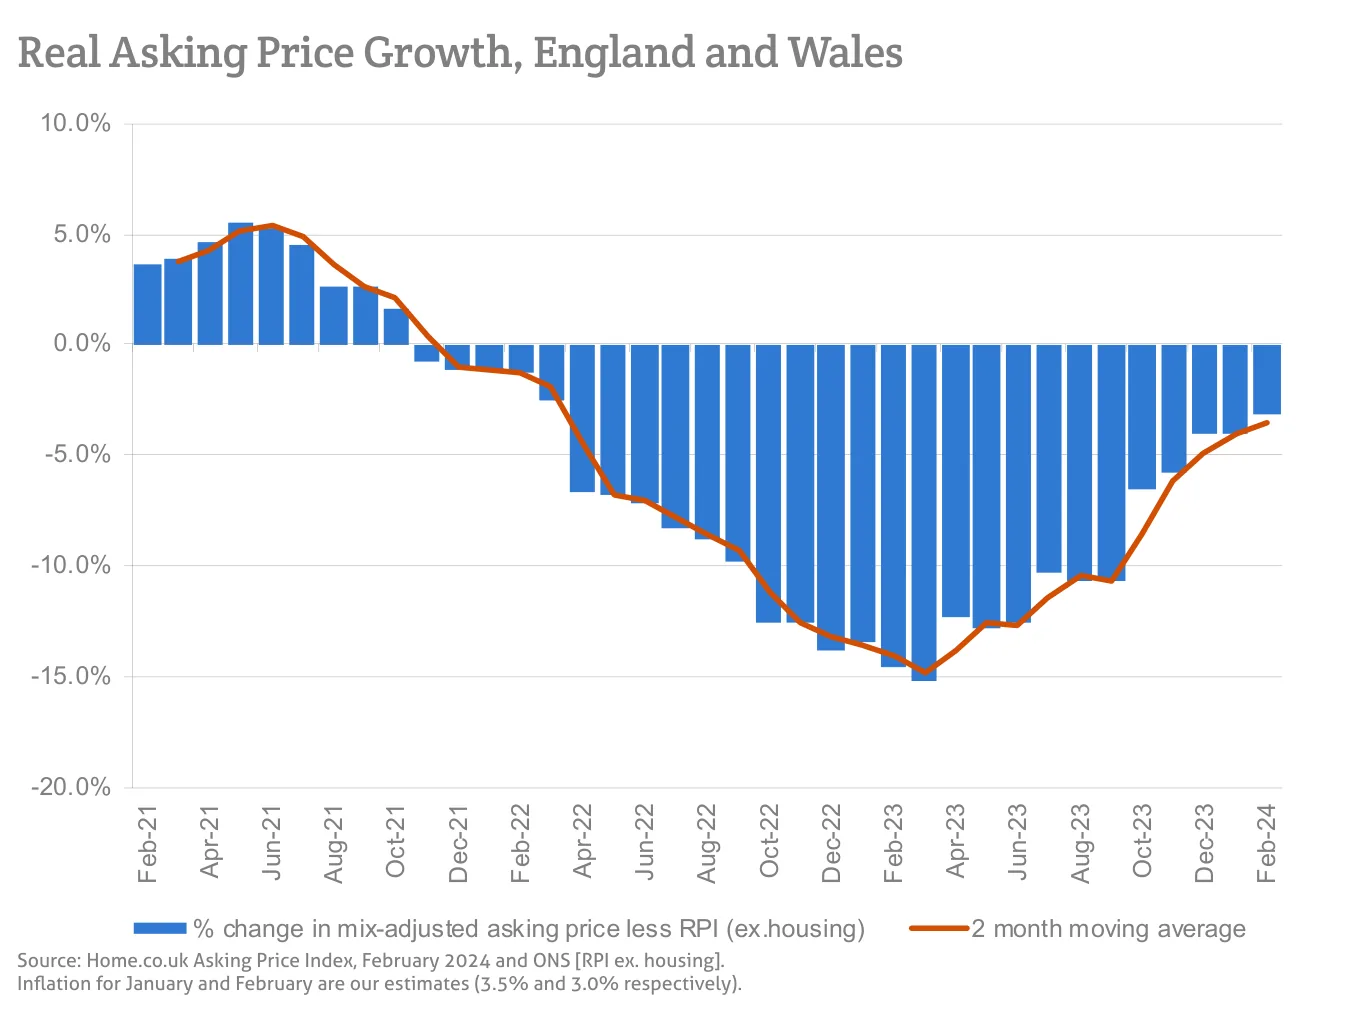
Source: Home.co.uk Asking Price Index, February 2024 and ONS [RPI ex. housing].
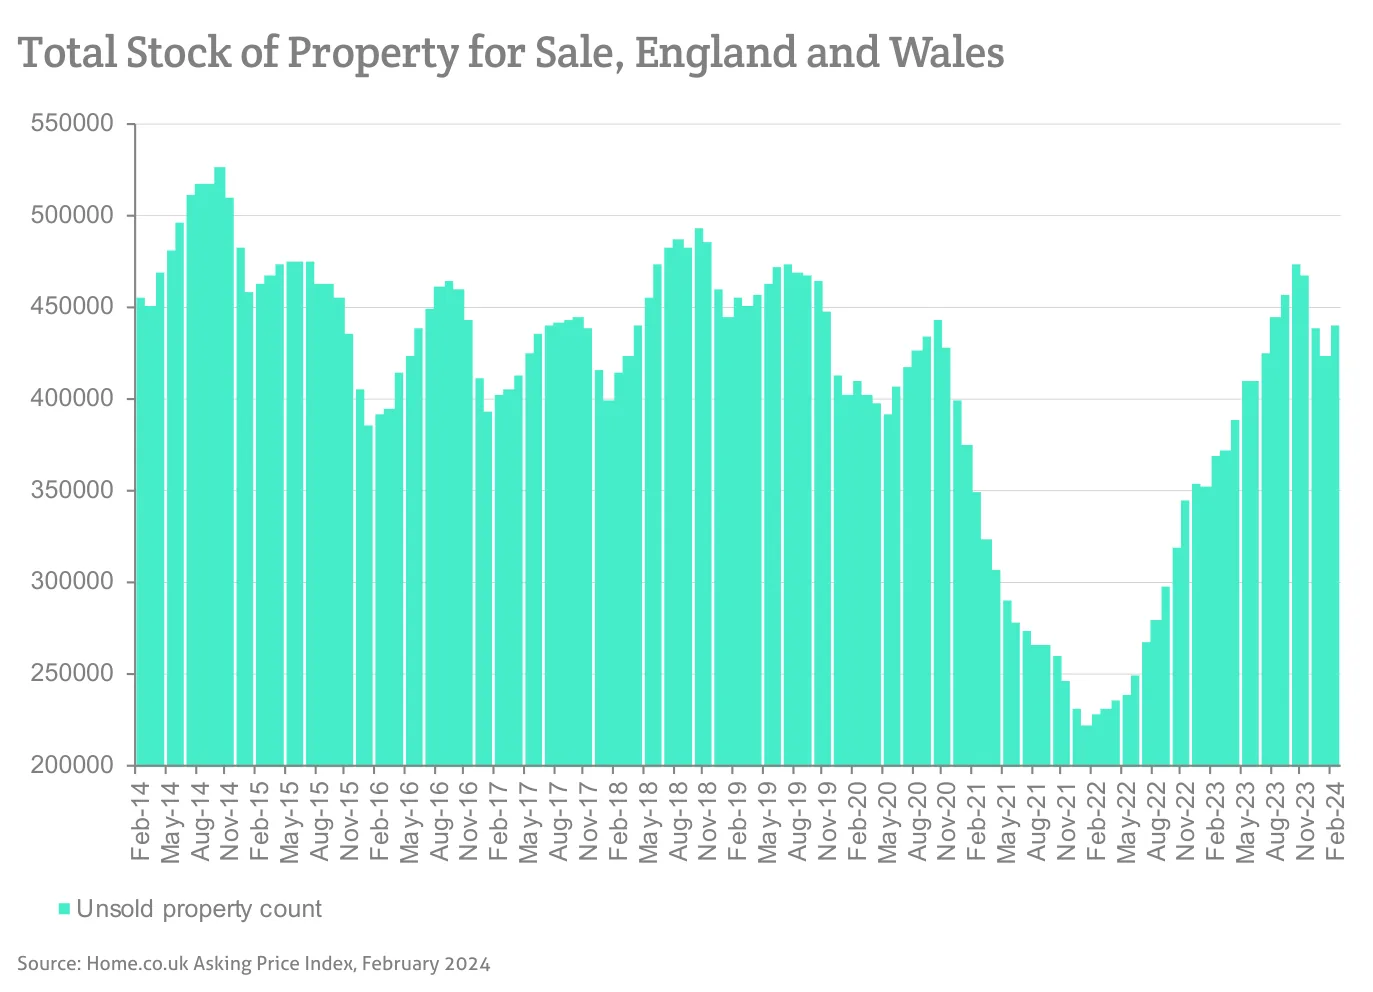
Source: Home.co.uk Asking Price Index, February 2024
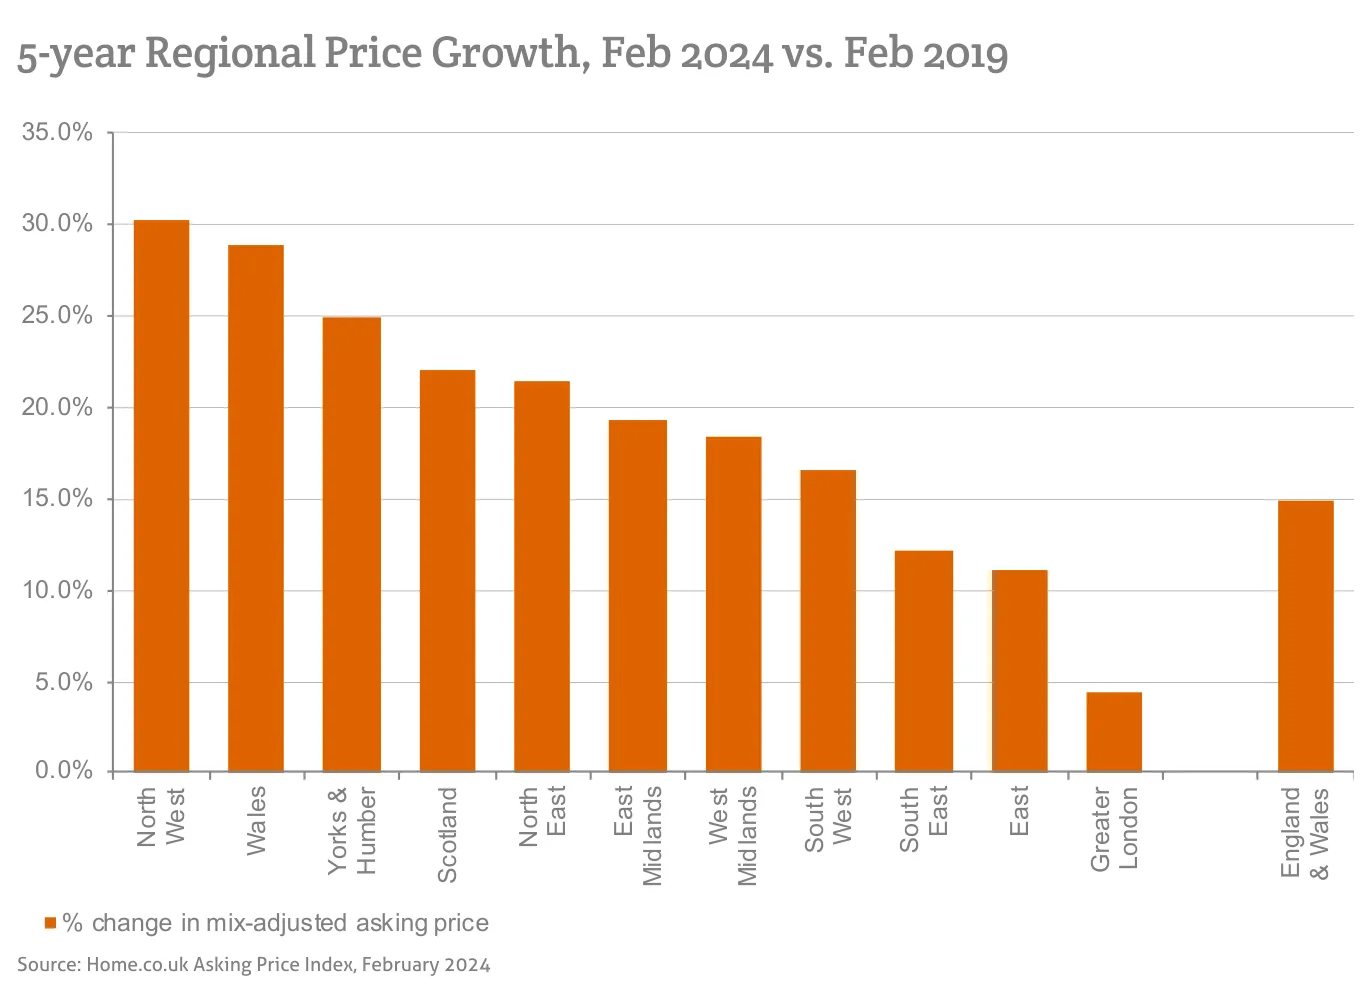
Source: Home.co.uk Asking Price Index, February 2024
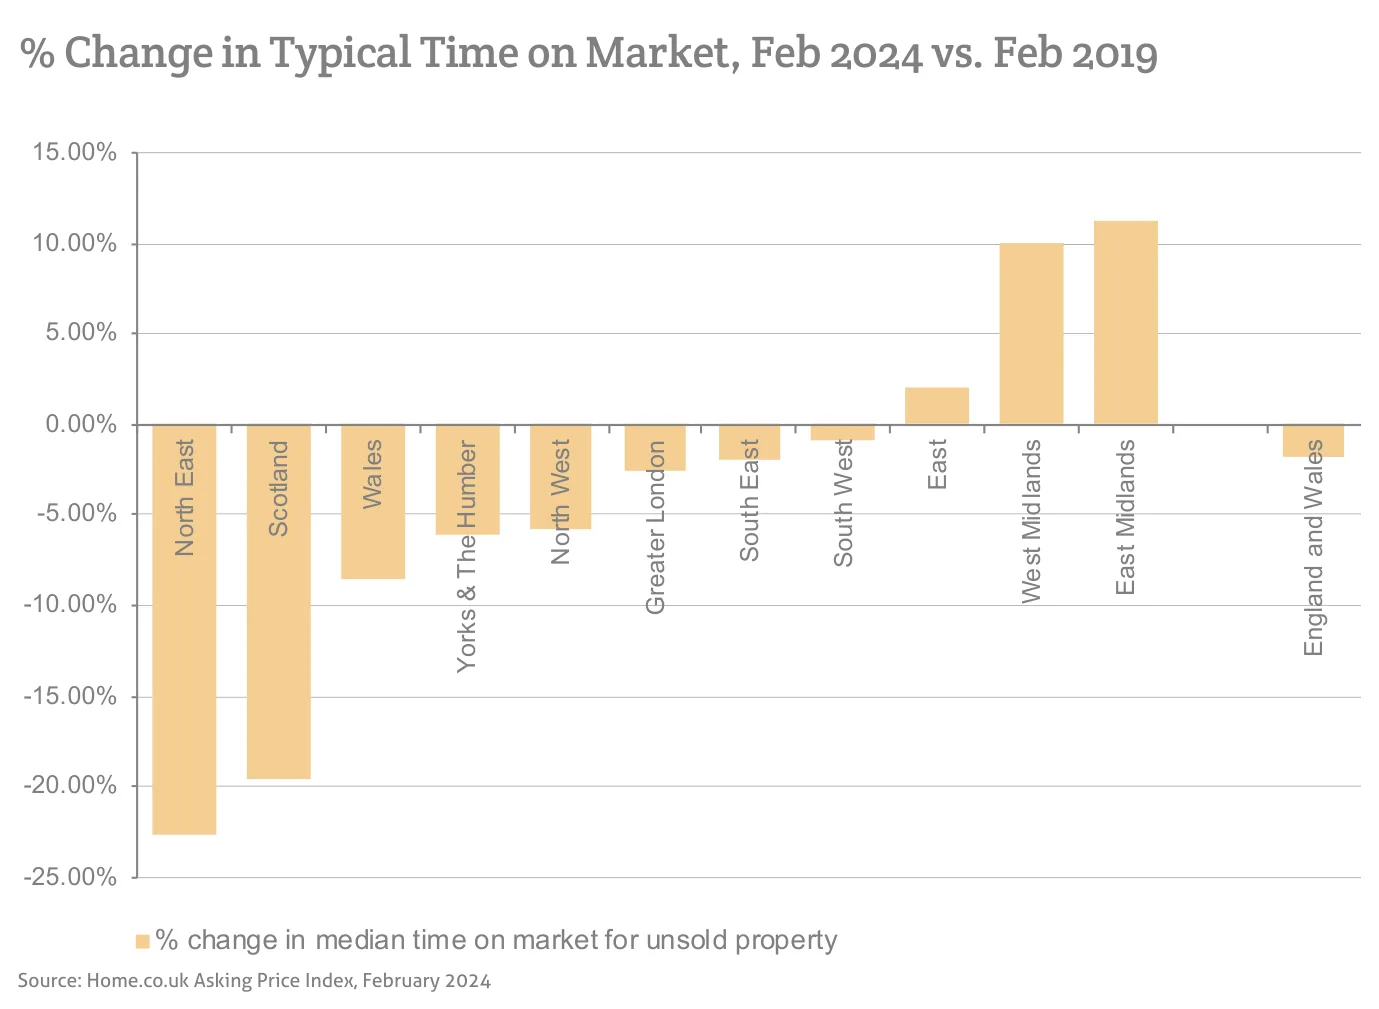
Source: Home.co.uk Asking Price Index, February 2024
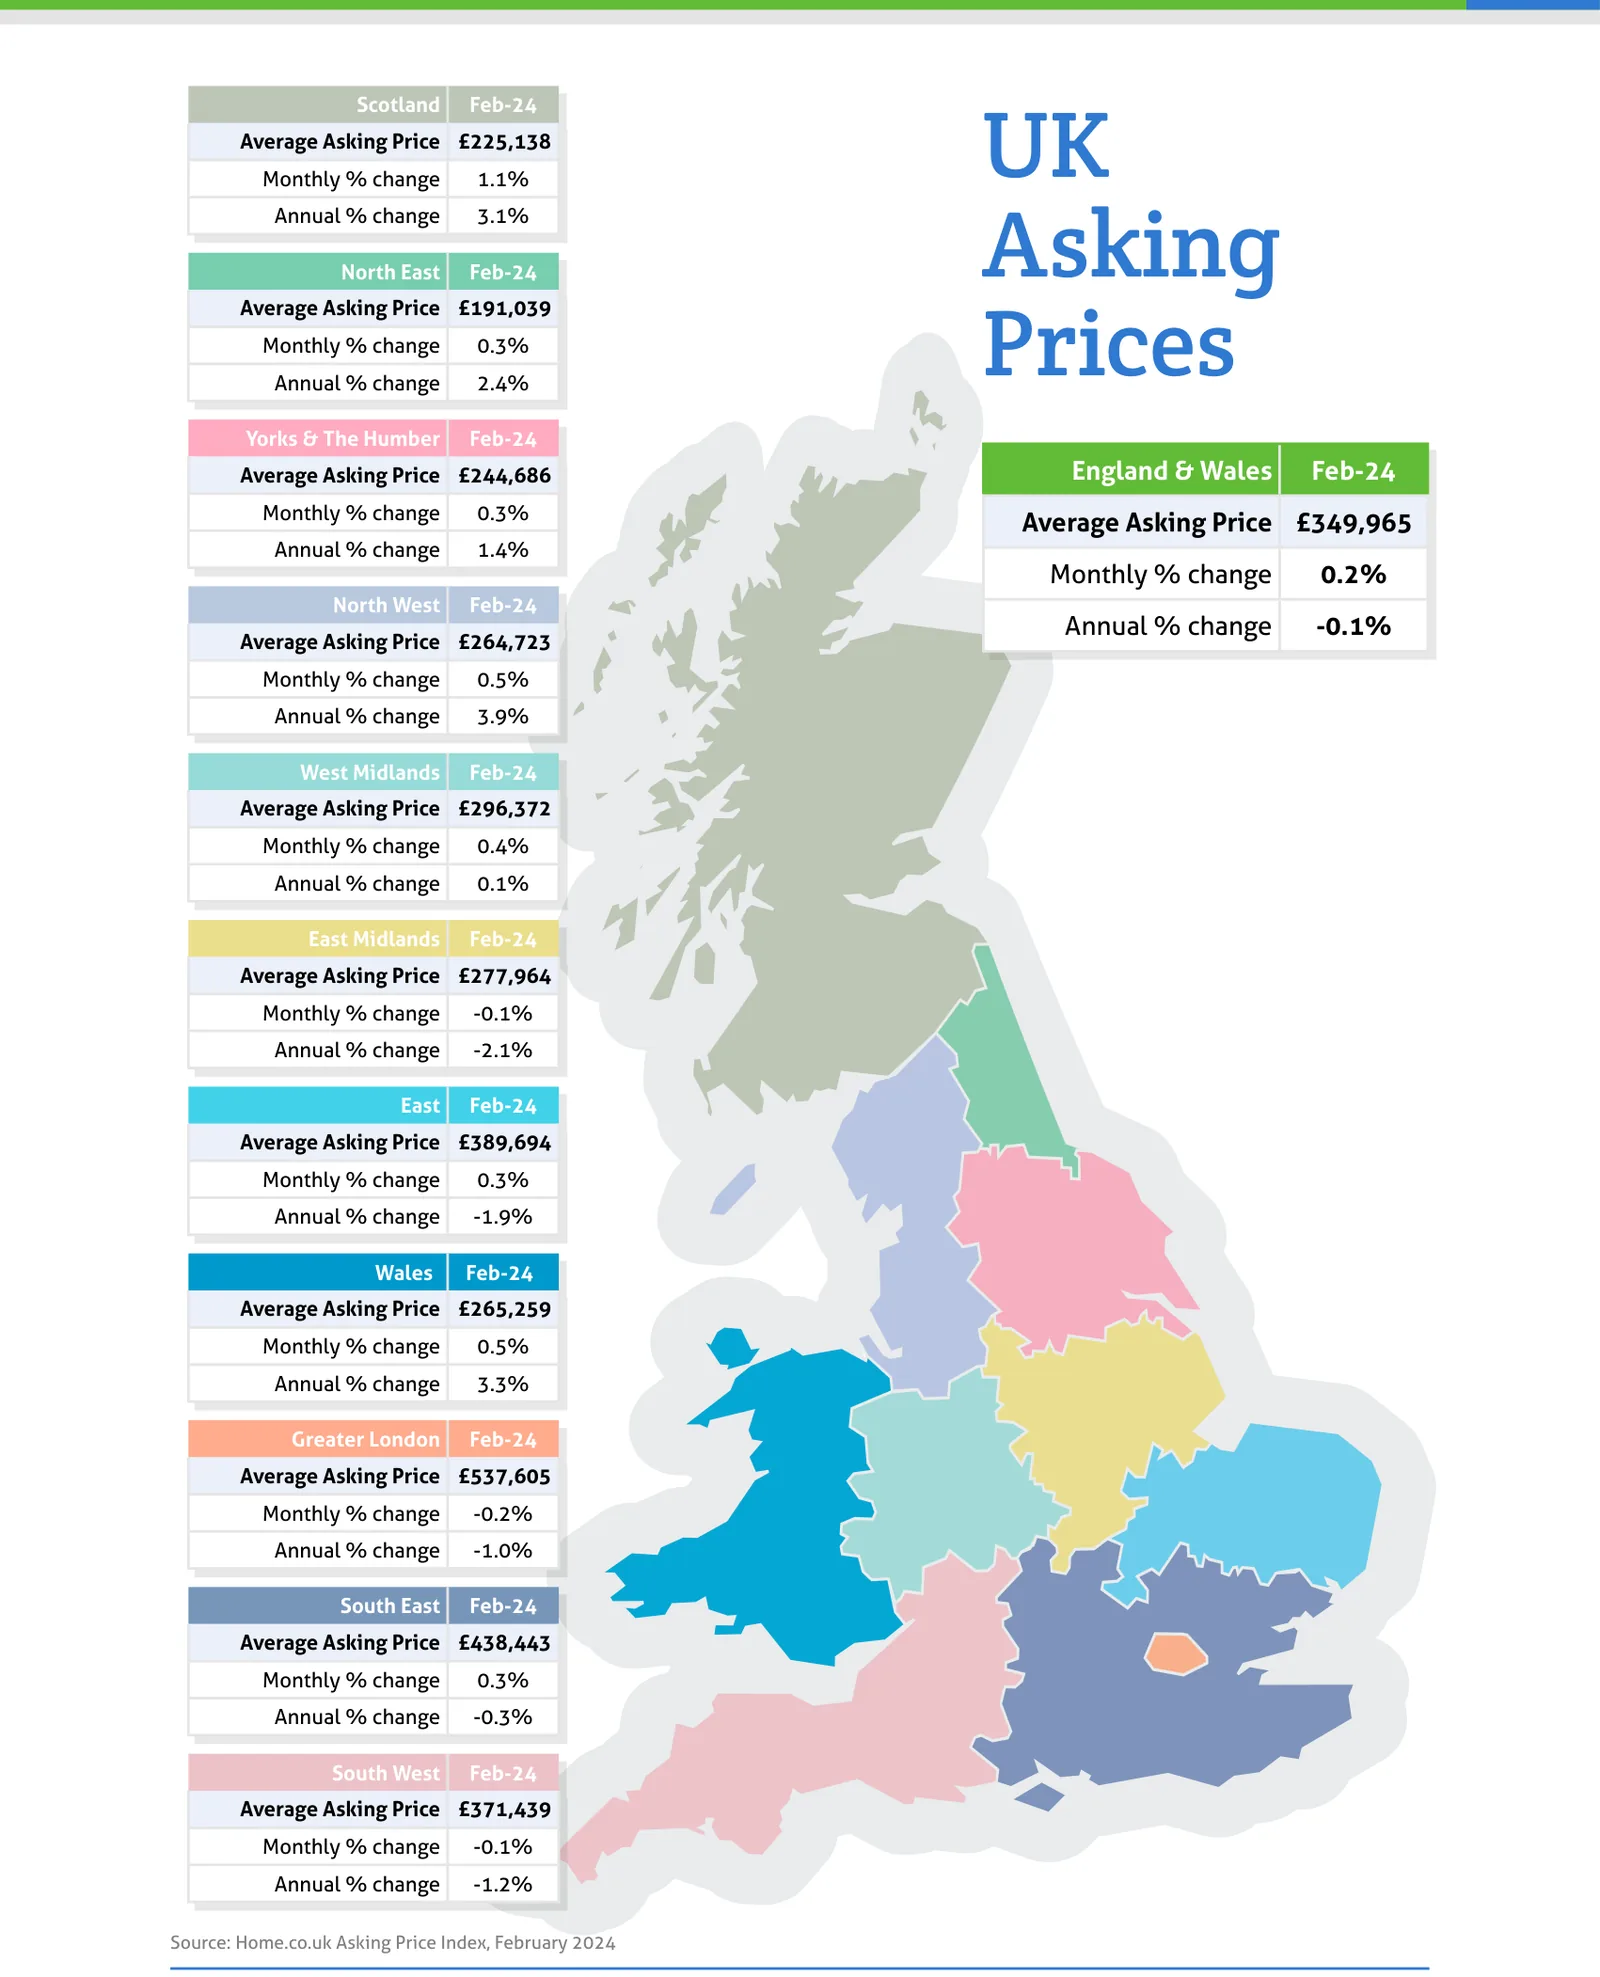
Source: Home.co.uk Asking Price Index, February 2024
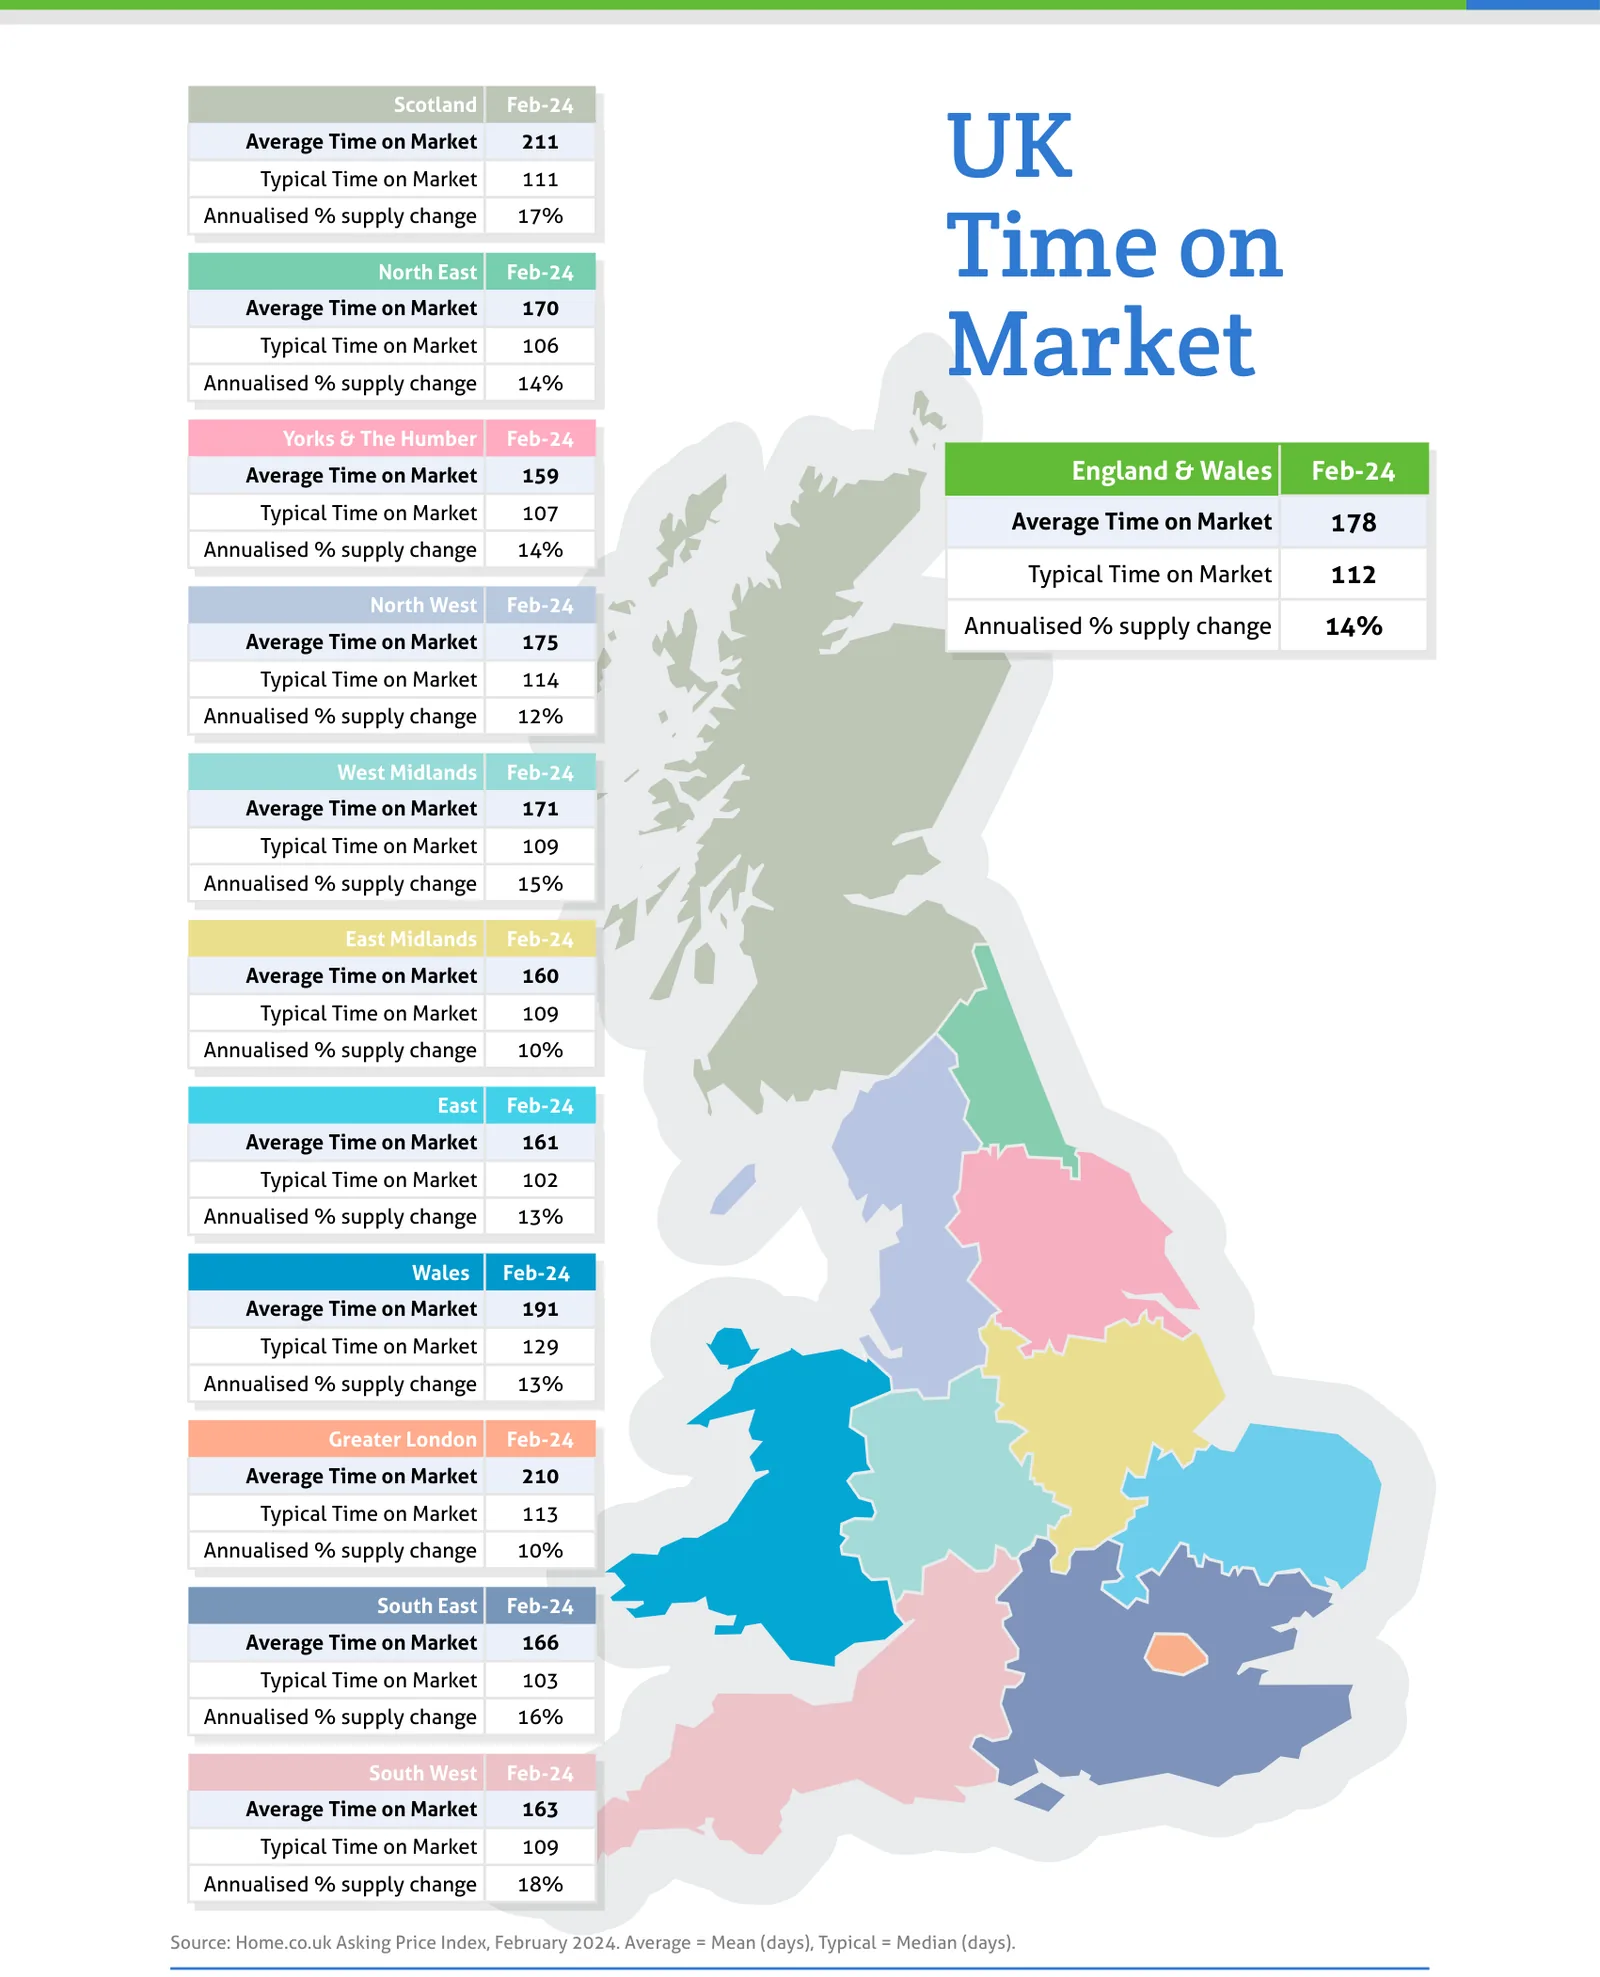
Source: Home.co.uk Asking Price Index, February 2024. Average = Mean (days), Typical = Median (days).
Regional tables
UK Asking Prices, Feb-24
| Region | Average Asking Price | Monthly % change | Annual % change |
|---|---|---|---|
| Scotland | £225,138 | 1.1% | 3.1% |
| North East | £191,039 | 0.3% | 2.4% |
| Yorks & The Humber | £244,686 | 0.3% | 1.4% |
| England & Wales | £349,965 | 0.2% | -0.1% |
| North West | £264,723 | 0.5% | 3.9% |
| West Midlands | £296,372 | 0.4% | 0.1% |
| East Midlands | £277,964 | -0.1% | -2.1% |
| East | £389,694 | 0.3% | -1.9% |
| Wales | £265,259 | 0.5% | 3.3% |
| Greater London | £537,605 | -0.2% | -1.0% |
| South East | £438,443 | 0.3% | -0.3% |
| South West | £371,439 | -0.1% | -1.2% |
UK Time on Market, Feb-24
| Region | Average Time on Market | Typical Time on Market | Annualised % supply change |
|---|---|---|---|
| Scotland | 211 | 111 | 17% |
| North East | 170 | 106 | 14% |
| Yorks & The Humber | 159 | 107 | 14% |
| England & Wales | 178 | 112 | 14% |
| North West | 175 | 114 | 12% |
| West Midlands | 171 | 109 | 15% |
| East Midlands | 160 | 109 | 10% |
| East | 161 | 102 | 13% |
| Wales | 191 | 129 | 13% |
| Greater London | 210 | 113 | 10% |
| South East | 166 | 103 | 16% |
| South West | 163 | 109 | 18% |
From the director's commentary
"The market is clearly on a much firmer footing now than in February 2023. As I mentioned last month, we could see a steady return to growth this year that would complete the market recovery if the government doesn't mess it up by trying to borrow and spend too much before the election."
Doug Shephard, Director at Home.co.uk
Read the full February 2024 edition (PDF, 10 pages)
About the Home Asking Price Index
The Home Asking Price Index measures the change in the prices sellers ask for residential property across England, Wales and Scotland. Today it is computed every month from around half a million advertised homes and is mix-adjusted, so a change in what happens to be on the market does not move the figure; earlier editions state the sample they were built from. Because an asking price is set months before a sale completes, the index runs around five months ahead of completed-sale measures such as the UK House Price Index.
Every edition in the archive, back to October 2006, is listed on the index page. How we measure the UK property market explains the listing data behind it, and today's figures by area are on house prices and rental prices.
Text and figures above are quoted from the February 2024 edition as published, with punctuation normalised for the web, and are not revised. Later editions may restate them.
More in What is happening to house prices: the Home guide
Thinking about your next move?
See what your home's worth in seconds, with the UK's longest-running property data behind it.
Get an instant valuation