Home Asking Price Index, December 2021: half the shelves are empty
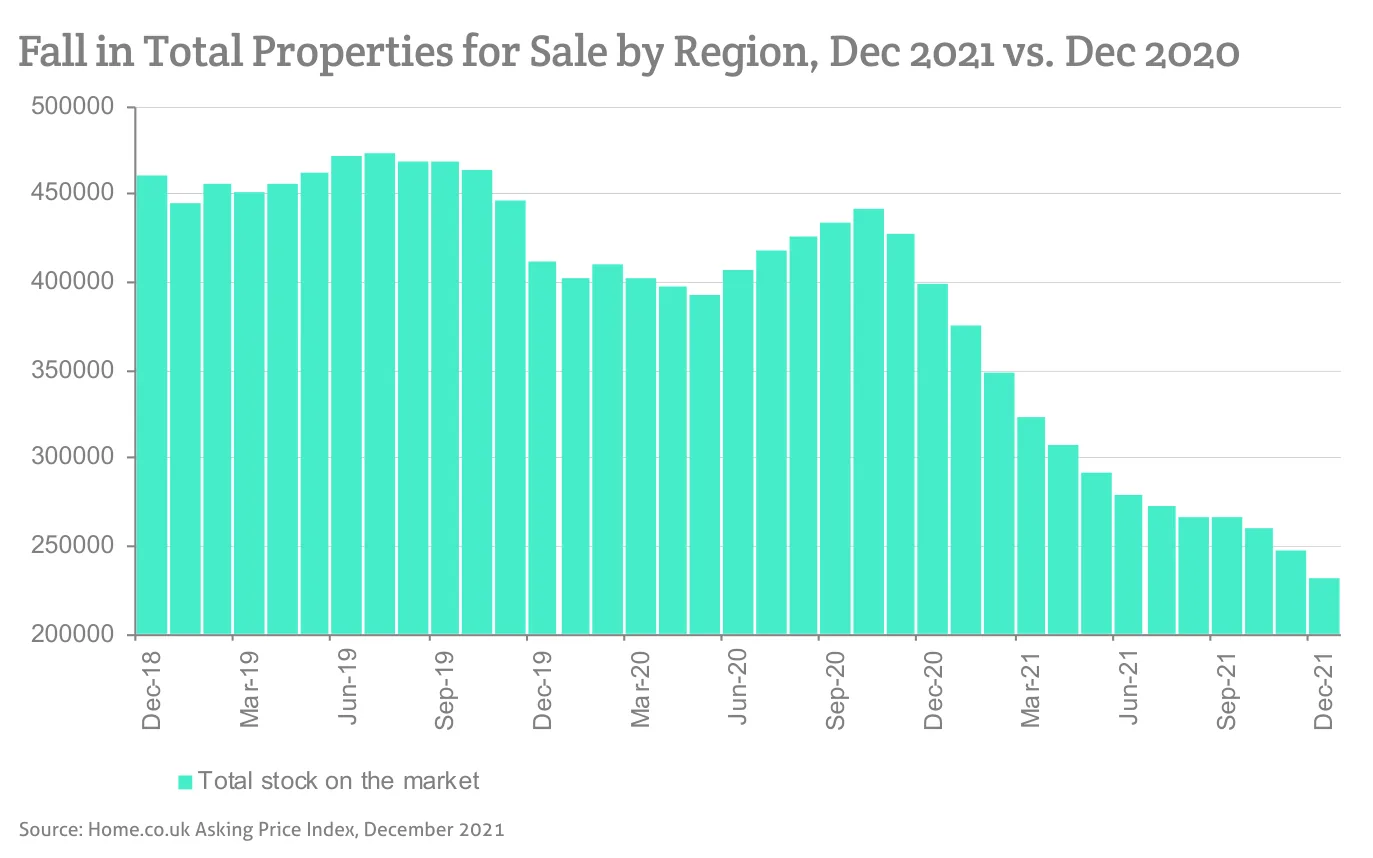
Unsold housing stock in England and Wales fell to a record low of 231,260 properties in December, down 42% year on year, while prices dipped 0.4% monthly.
This is the December 2021 edition of the Home Asking Price Index, released on 15 December 2021, under the headline:
Half the Shelves are Empty
The headlines and summary below are the report's own words, with the key figures as it published them, followed by the report's charts and regional tables as printed.
Headlines
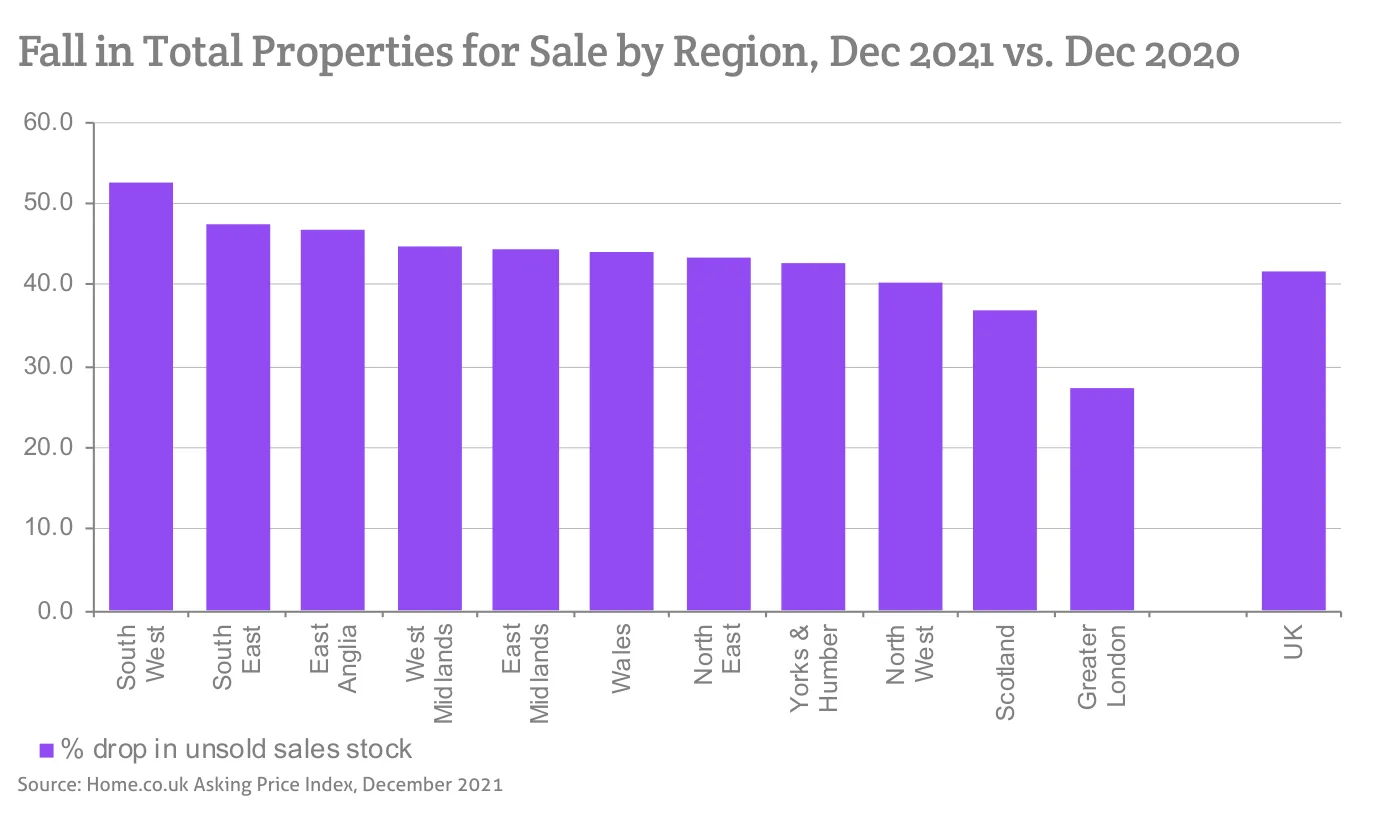
- The total stock of property for sale in England and Wales continues to plummet as demand outweighs supply, hitting a new record low of 231,260, 42.0% lower than in December 2020 and 49.8% less than in December 2018.
- Monthly supply of new instructions remains relatively low across the UK (-19% compared to the month of November 2020). Again, Greater London and the South East show the greatest contractions (33% and 28% respectively).
- Asking prices across England and Wales show a seasonal correction this month, dipping 0.4% since November, although the annualised average growth is up slightly at 6.9%. The greatest price corrections were in the East (-1.1%) and North East of England (-1.5%).
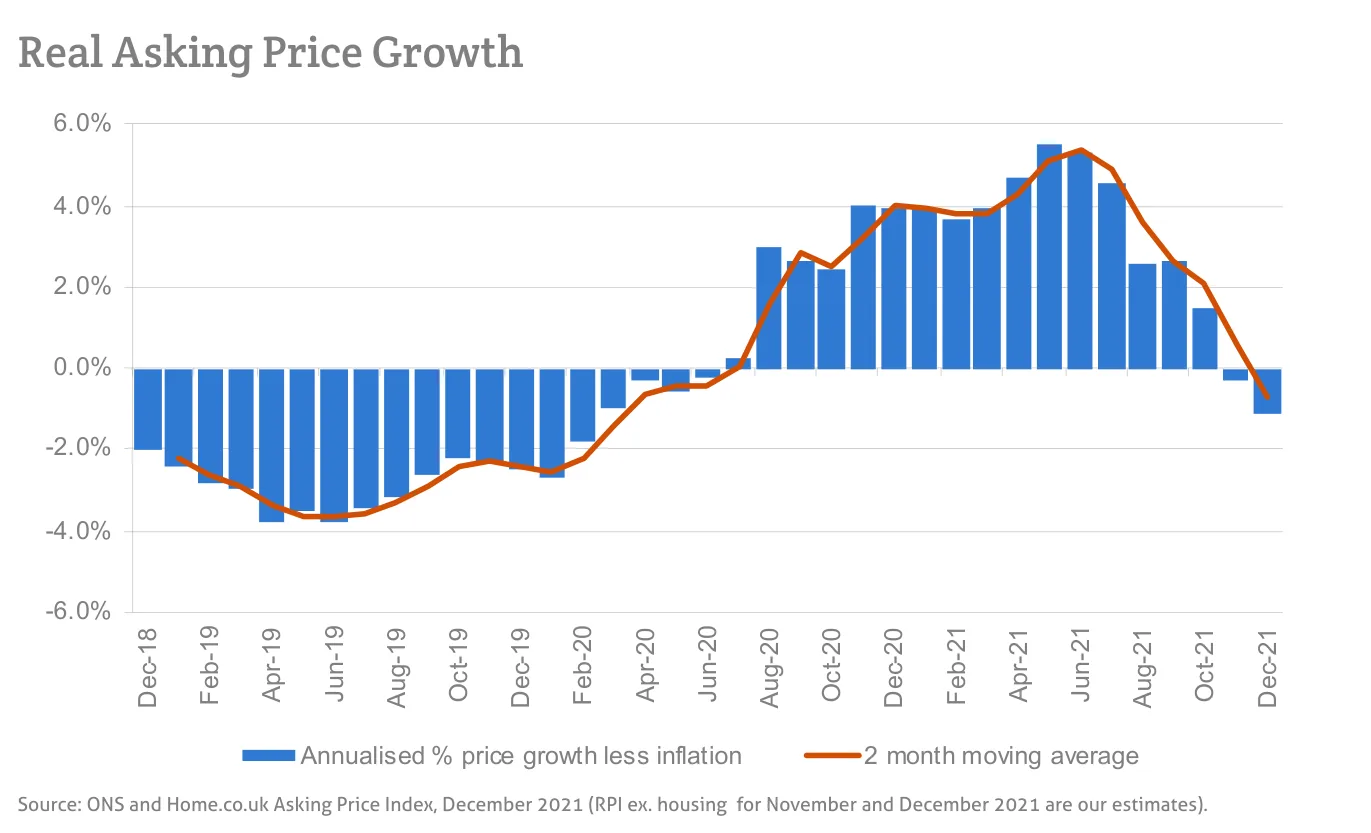
- Rampant inflation already makes real home price growth effectively zero and it is likely to be negative over the coming months.
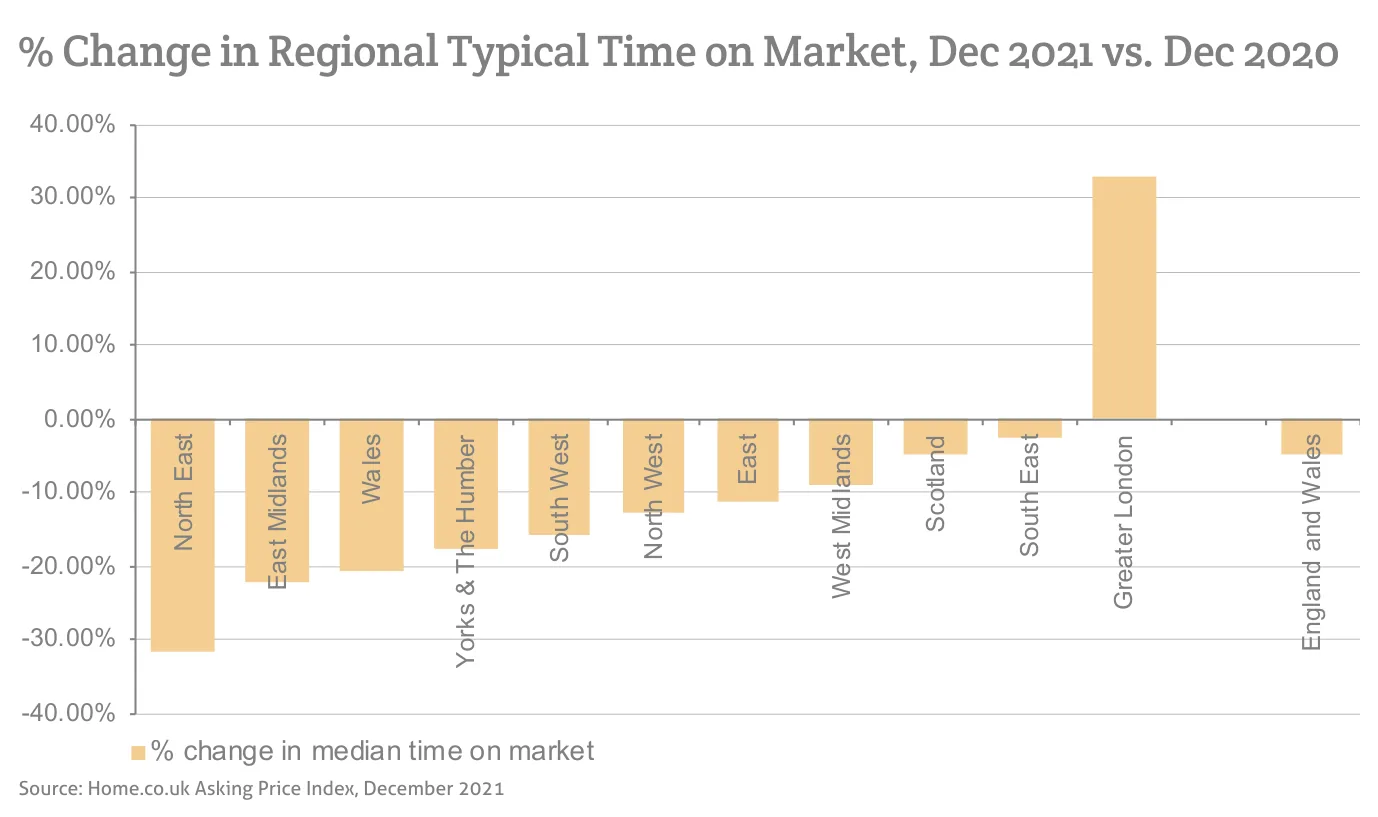
- The market shows exceptional momentum for the time of year with the Typical Time on Market for unsold property in England and Wales remaining at 80 days (median), contrary to seasonal expectations of a slowdown. Never in the history of this index has the typical property spent so little time on the market in December.
- Low supply and growing demand continue to create upward price pressure despite this month's seasonal correction. Prices in Greater London, the South West and Wales are unchanged since last month.
- The East of England property market continues to lead the 12-month regional price growth chart with an inflation-beating gain of 10.7%, closely followed by the East Midlands (+10.3%).
- The Greater London market performance improves further and now indicates 4.1% annualised growth, ahead of Scotland, the North East (now the worst performer) and Yorkshire.
- Rents in Greater London are up an annualised 23%, while the stock of properties being advertised to let is down by 63% over the same period.
- Rents in central London are going ballistic. The greatest rises in asking rents over the last twelve months are in the City (+107%), Kensington and Chelsea (+51.6%) and Tower Hamlets (+46.3%), indicating huge demand for upmarket city living.
- Supply of rental properties is diminishing in all English regions, Scotland and Wales (down 36% since December 2020). Rents are up an annualised 5.8% across the UK. However, rents are correcting in several regions following the reversal of the COVID-related London exodus although, due to scarcity, this is likely to be transitory.
- The largest annualised average rent hikes outside of London are in the East of England (+7.1%) and the South East (+5.0%).
Summary
An unprecedented level of scarcity continues to dominate the UK sales market. The total property count of unsold property plunged to a new record low this month. Demand, fuelled by ultra-low mortgage interest rates, has eaten away 42% of agents' inventories over just the last twelve months. In fact, property investment is seen by many as a no-brainer when interest rates are so much lower than inflation. The resulting 'free money' is available to anyone with a deposit.
Surging rents (and yields) in central London, coupled with 'free money' for borrowers, has triggered greater demand in the London sales market. Increasing demand has already reduced the total sales stock total in London by 28% since Dec 2020 and supply has nosedived compared to last year. For the time being, home price growth in Greater London is a sub-inflation 4.1% but this could change radically next year and may even catch up with the official rate of inflation.
Key figures
| Measure | Figure |
|---|---|
| Total unsold stock | 231,260 |
| Monthly change in asking prices | -0.4% |
| Annual change in asking prices | +6.9% |
| Typical Time on Market | 80 days |
| Change in new instructions | -19% |
| Change in rental supply | -36% |
| Annualised asking rent growth (UK) | +5.8% |
| Stock fall vs December 2020 | -42.0% |
Figures are for England and Wales unless the report states otherwise, as published in the edition.
Charts from the report
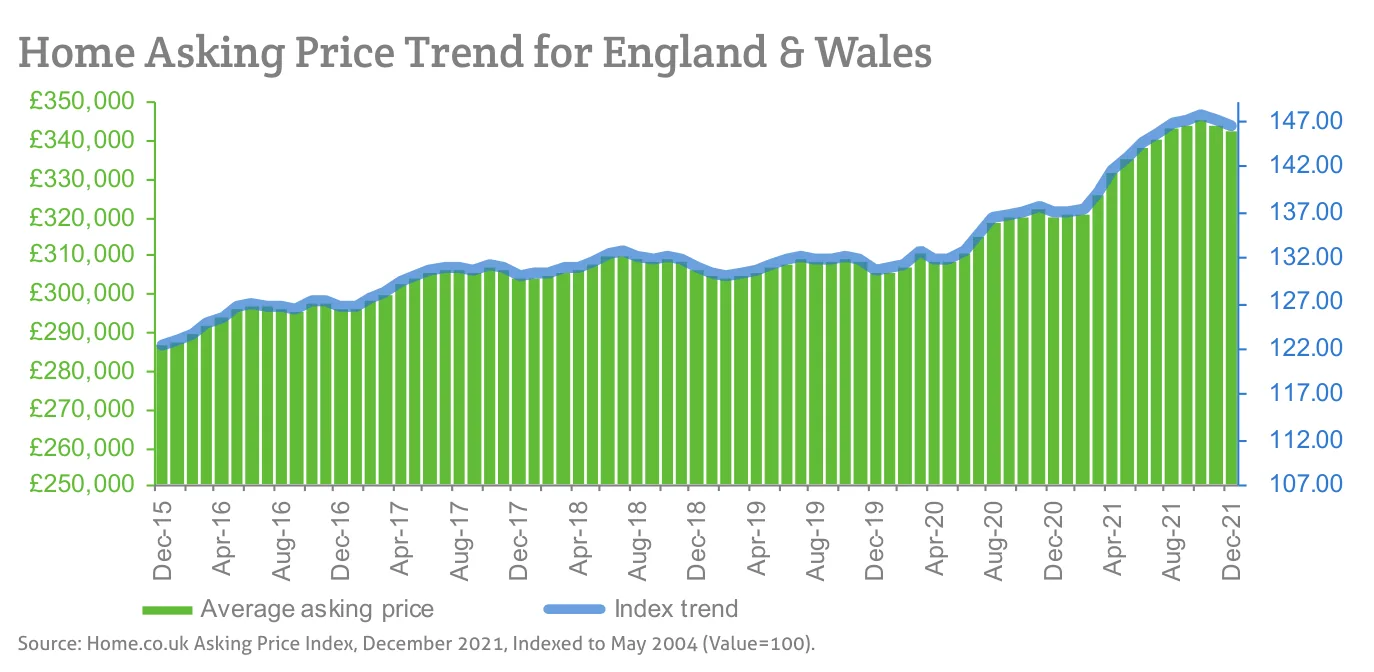
Source: Home.co.uk Asking Price Index, December 2021, Indexed to May 2004 (Value=100).
Source: Home.co.uk Asking Price Index, December 2021
Source: Home.co.uk Asking Price Index, December 2021
Source: ONS and Home.co.uk Asking Price Index, December 2021 (RPI ex. housing for November and December 2021 are our estimates).
Source: Home.co.uk Asking Price Index, December 2021
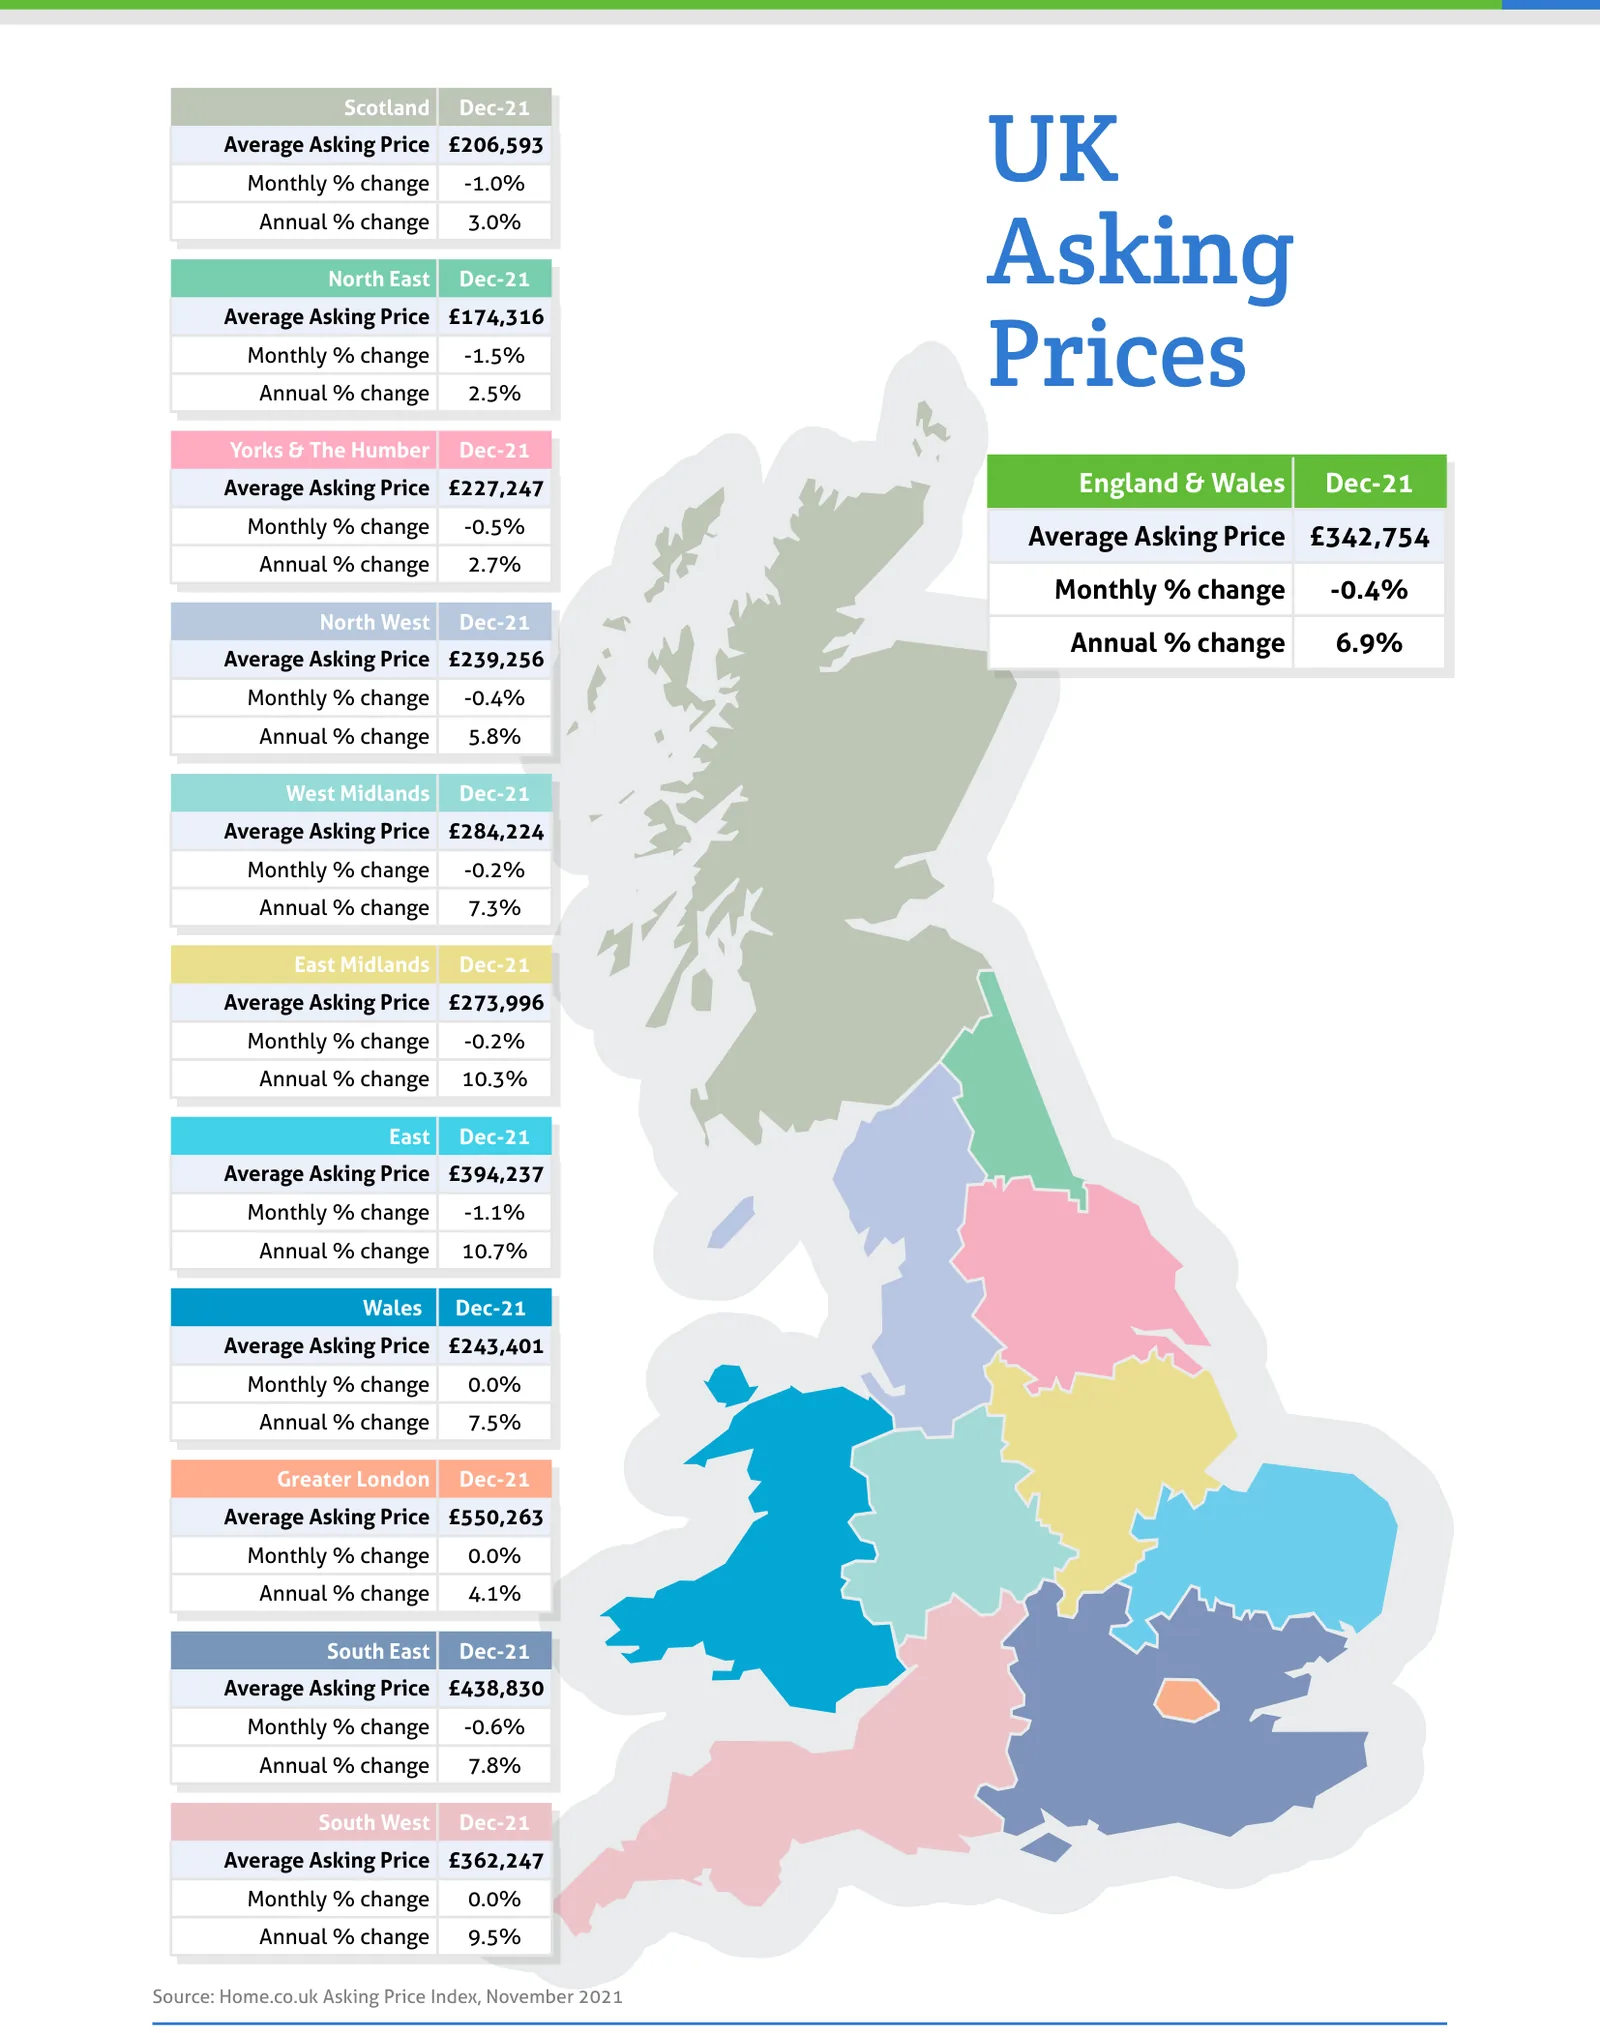
Source: Home.co.uk Asking Price Index, November 2021
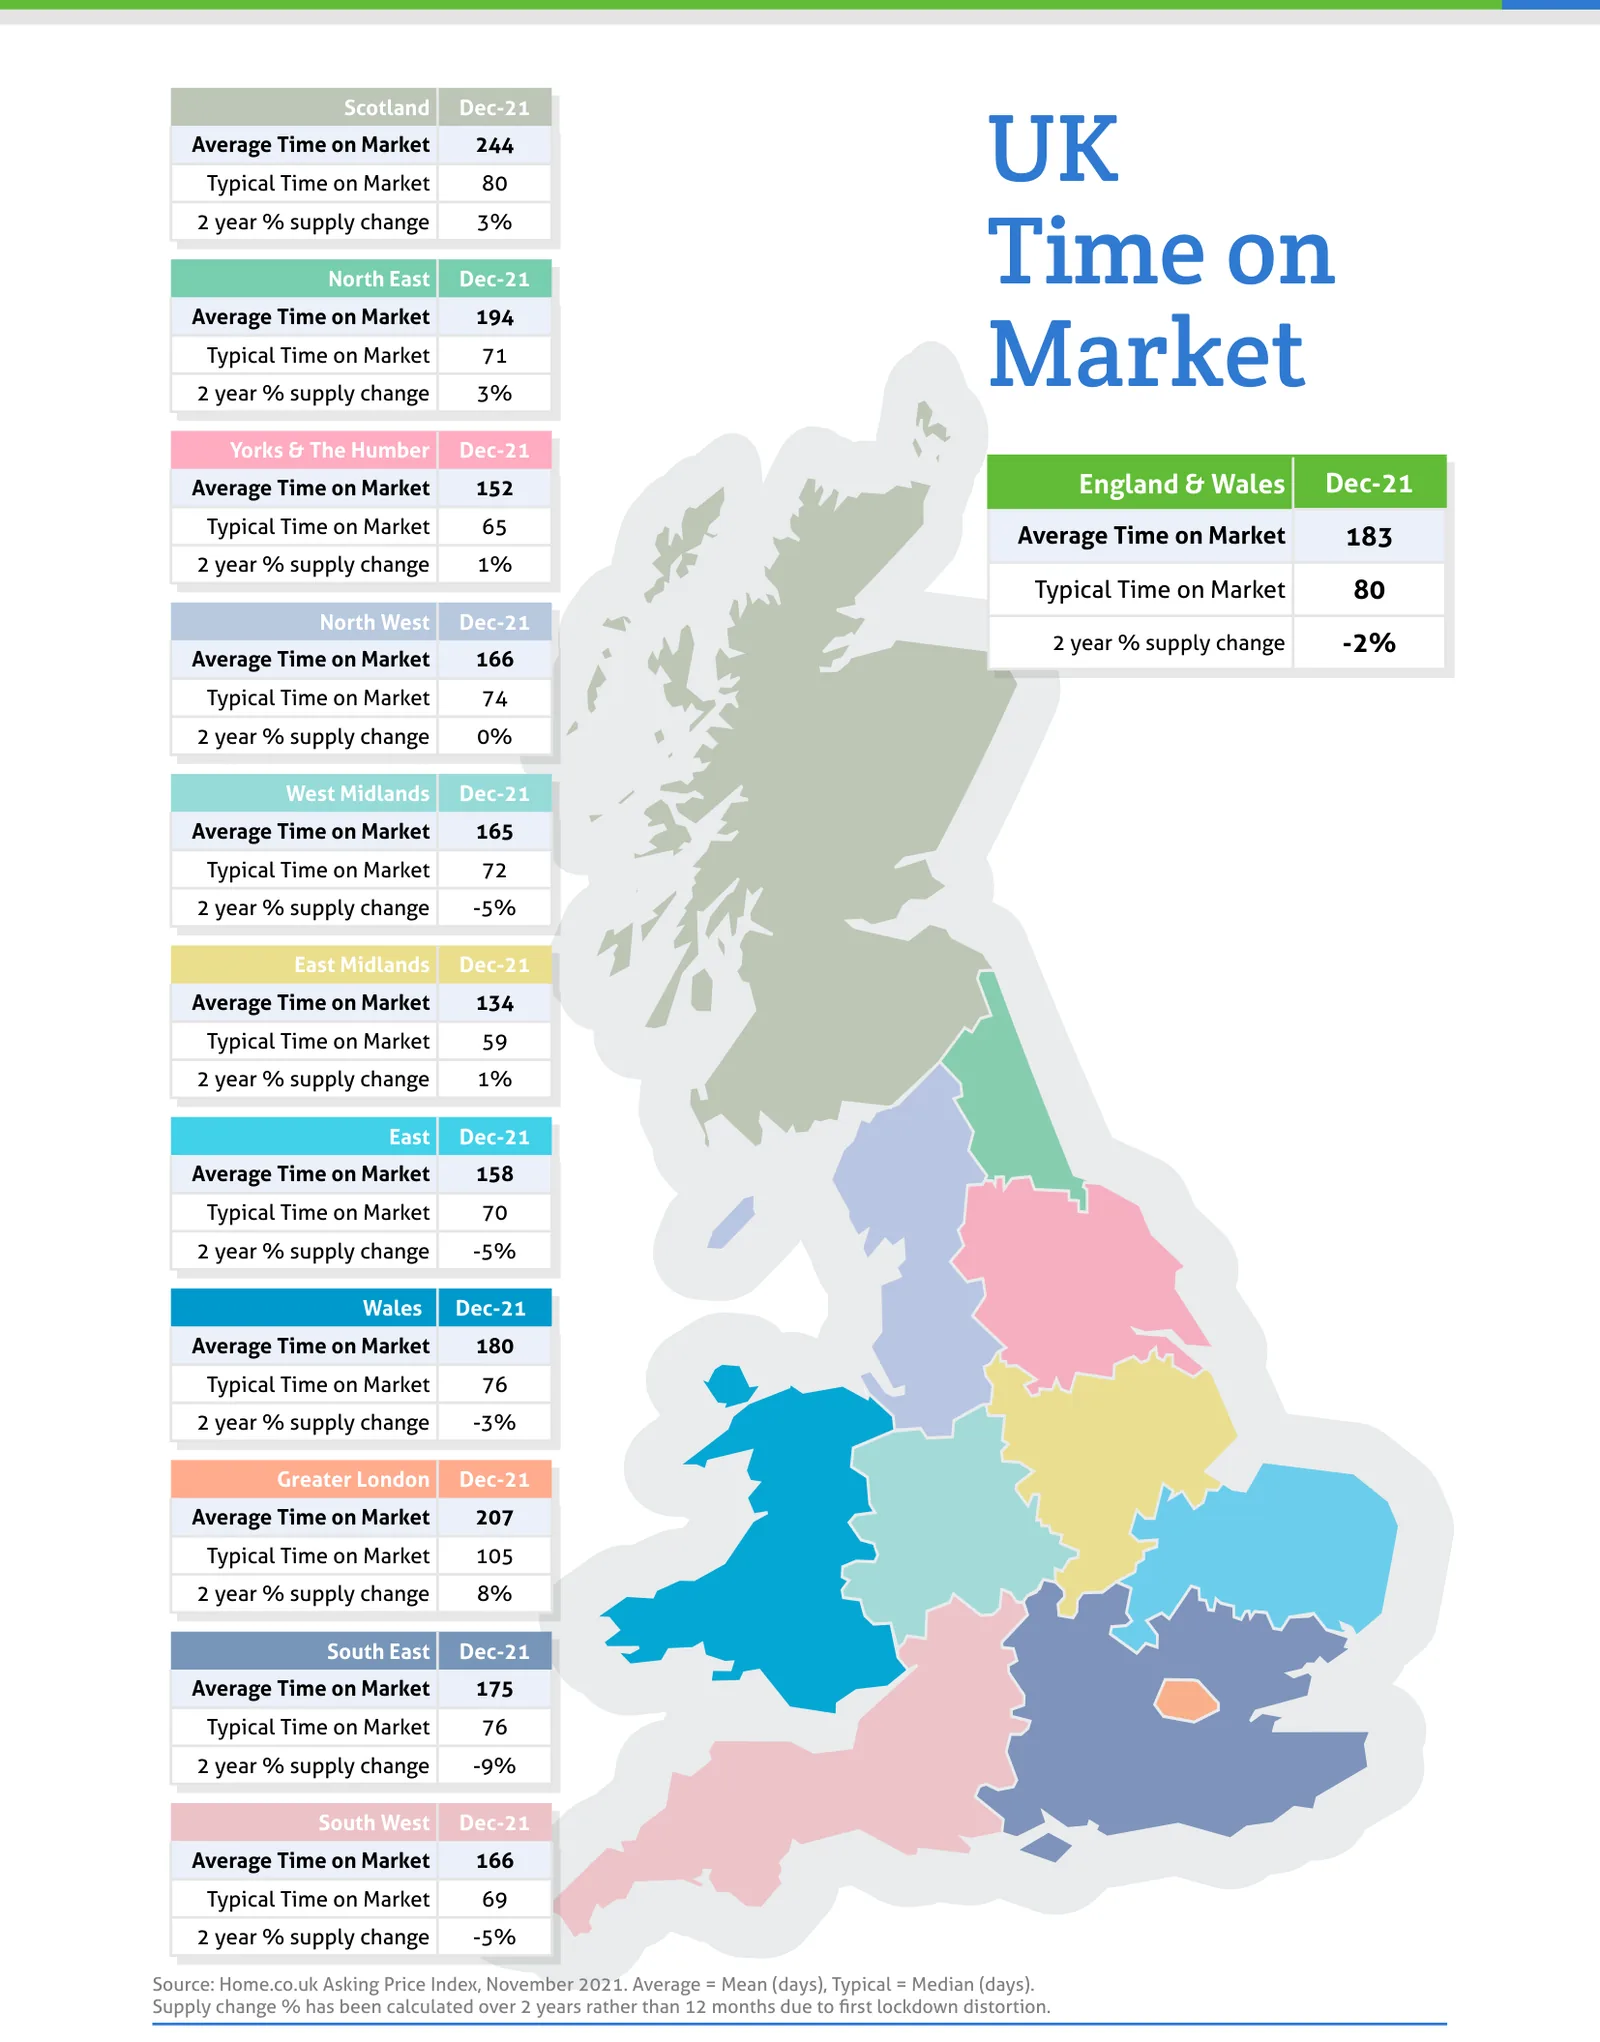
Source: Home.co.uk Asking Price Index, November 2021. Average = Mean (days), Typical = Median (days).
Regional tables
UK Asking Prices, Dec-21
| Region | Average Asking Price | Monthly % change | Annual % change |
|---|---|---|---|
| Scotland | £206,593 | -1.0% | 3.0% |
| North East | £174,316 | -1.5% | 2.5% |
| Yorks & The Humber | £227,247 | -0.5% | 2.7% |
| England & Wales | £342,754 | -0.4% | 6.9% |
| North West | £239,256 | -0.4% | 5.8% |
| West Midlands | £284,224 | -0.2% | 7.3% |
| East Midlands | £273,996 | -0.2% | 10.3% |
| East | £394,237 | -1.1% | 10.7% |
| Wales | £243,401 | 0.0% | 7.5% |
| Greater London | £550,263 | 0.0% | 4.1% |
| South East | £438,830 | -0.6% | 7.8% |
| South West | £362,247 | 0.0% | 9.5% |
UK Time on Market, Dec-21
| Region | Average Time on Market | Typical Time on Market | 2 year % supply change |
|---|---|---|---|
| Scotland | 244 | 80 | 3% |
| North East | 194 | 71 | 3% |
| Yorks & The Humber | 152 | 65 | 1% |
| England & Wales | 183 | 80 | -2% |
| North West | 166 | 74 | 0% |
| West Midlands | 165 | 72 | -5% |
| East Midlands | 134 | 59 | 1% |
| East | 158 | 70 | -5% |
| Wales | 180 | 76 | -3% |
| Greater London | 207 | 105 | 8% |
| South East | 175 | 76 | -9% |
| South West | 166 | 69 | -5% |
From the director's commentary
"So, inflation is here to stay as the central banks seem unwilling to bite the bullet and raise interest rates to put out the fire. What they are in fact achieving is a concerted devaluation of the major currencies."
Doug Shephard, Director at Home.co.uk
Read the full December 2021 edition (PDF, 9 pages)
About the Home Asking Price Index
The Home Asking Price Index measures the change in the prices sellers ask for residential property across England, Wales and Scotland. Today it is computed every month from around half a million advertised homes and is mix-adjusted, so a change in what happens to be on the market does not move the figure; earlier editions state the sample they were built from. Because an asking price is set months before a sale completes, the index runs around five months ahead of completed-sale measures such as the UK House Price Index.
Every edition in the archive, back to October 2006, is listed on the index page. How we measure the UK property market explains the listing data behind it, and today's figures by area are on house prices and rental prices.
Text and figures above are quoted from the December 2021 edition as published, with punctuation normalised for the web, and are not revised. Later editions may restate them.
More in What is happening to house prices: the Home guide
Thinking about your next move?
See what your home's worth in seconds, with the UK's longest-running property data behind it.
Get an instant valuation